PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2115039

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2115039
Oil Condition Monitoring - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
According to Mordor Intelligence, the oil condition monitoring market size is expected to grow from USD 1.88 billion in 2025 to USD 1.99 billion in 2026 and is forecast to reach USD 2.64 billion by 2031 at 5.78% CAGR over 2026-2031.
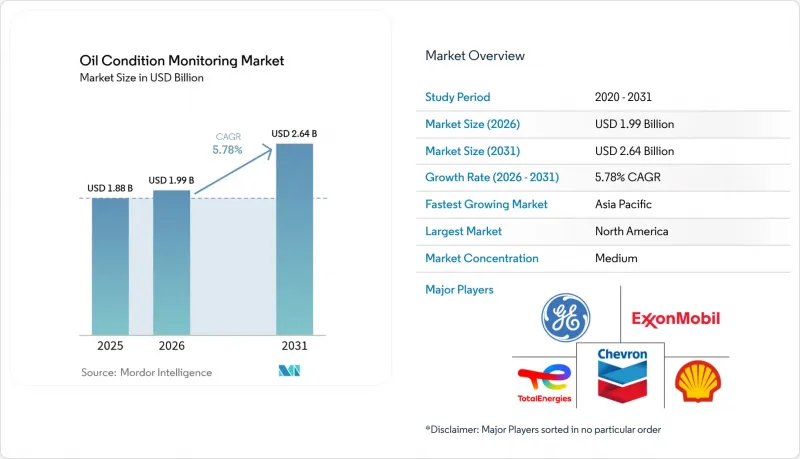
This report is Segmented by Sampling Type (On-Site, Off-Site), Product/Equipment Type (Turbines, Engines, Gear Systems, and More), Sensor/Measurement Type (Viscosity Sensors, Temperature Sensors, Pressure Sensors, and More), Service Offering (Hardware, Software, Laboratory Testing Services), End-User Industry, and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global Oil Condition Monitoring Market Trends and Insights
OEM warranty mandates
North American heavy-duty OEMs have started tying extended engine warranties to routine submission of oil spectrography reports, driving accelerated uptake of the oil condition monitoring market within dealer networks. The program reduces OEM liability by catching early contamination and wear, while fleet operators gain longer engine life and optimized drain intervals. Major Class-8 truck builders now bundle sensor kits with power-train service contracts, nudging independent maintenance shops toward cloud-based dashboards that can ingest OEM telematics feeds. As warranty cost avoidance is quantified in predictive models, CFOs reallocate budgets from reactive repairs to predictive analytics subscriptions. Adoption remains highest in fleets with 300-plus vehicles that amortize sensor investments quickly.
Offshore wind gearbox failures
Europe's offshore wind segment experiences gearbox replacement costs that exceed USD 200,000 per turbine, creating a robust business case for inline ferrous-debris monitors. Operators use real-time metal-particle counts to shift from calendar-based drains to data-dictated interventions, reducing crane-vessel deployments in harsh North Sea conditions. Sensor retrofits integrate with SCADA platforms and feed digital twins that model torque, vibration, and lubricant contamination concurrently. EU and UK subsidy structures penalize non-availability, so operators favor technologies that guarantee high service factors. Vendors offering pre-calibrated AI models gain traction because they reduce commissioning complexity, shrinking the payback period to under 18 months.
Capex Burden of Online Sensors for ASEAN SMEs
Small and medium enterprises across ASEAN markets face significant capital expenditure constraints that limit adoption of online oil condition monitoring systems, despite clear operational benefits. The ASEAN SME Policy Index 2024 highlights that SMEs contribute 64.6% of regional employment and 38.3% to GDP, yet face persistent challenges in accessing capital for technology investments. Online sensor systems typically require USD 5,000-15,000 initial investment per monitoring point, representing a substantial financial barrier for manufacturing SMEs operating on thin margins. The region's heavy reliance on fossil fuels, with oil demand expected to increase 20% by 2035 and annual import bills exceeding USD 200 billion, creates additional cost pressures that limit discretionary technology spending.
Other drivers and restraints analyzed in the detailed report include:
- LNG fleet expansion
- Digital-twin programs in Canadian oil sands
- Legacy SCADA Integration Issues in US Midstream Pipelines
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Off-site laboratory testing commanded 59.30% of the oil condition monitoring market in 2025 as heavy industry continued to rely on accredited labs for comprehensive elemental and contamination analyses. The model offers deep data sets but introduces lags between sampling and decision-making, sometimes leading to reactive maintenance. Large refineries and power plants maintain yearly contracts with regional labs covering ICP, FTIR, and ferrous density tests. However, courier delays and manual data entry remain pain points.
On-site systems are the fastest-growing segment, expanding at a 9.02% CAGR as IoT mini-labs shrink footprint and cost. Portable viscometers and infrared spectrometers now fit into ruggedized cases, allowing technicians to cut turnaround time from days to minutes. Plants with continuous processes appreciate the closed-loop feedback that lets them adjust load profiles or filtration regimes immediately. Subscription models offer calibration services and cloud dashboards that archive historic trends across multiple sites. By 2031, on-site deployments could erode the oil condition monitoring market share of external labs among mid-tier manufacturers while labs pivot toward data science services.
Engines remained the largest application, holding 31.80% of the oil condition monitoring market share in 2025. High-speed rotating parts create metal wear, soot, and acid that demand early detection. Commercial marine, mining haul trucks, and standby power gensets increasingly embed cylinder-liner wear models in enterprise maintenance planning. Extended drain intervals driven by low-sulfur and bio-blend fuels further underline the need for precise lubricant chemistry insights.
Hydraulic systems are projected to grow at 8.72% CAGR as factory automation and mobile equipment sophistication rise. Electrohydraulic actuators in injection-molding lines and precision presses rely on contaminant-free fluids to sustain micron-level tolerances. OEMs now pre-install 4-14 µm particle counters and moisture sensors that alert control-room PLCs in real time. With every unscheduled hydraulic failure reputed to cost USD 12,000 per hour in automotive stamping plants, operators justify sensor investments within a single incident avoidance. The oil condition monitoring market size for hydraulics will expand further as the global motion-control base broadens.
Complete Report Scope:
- By Sampling Type
- On-Site (On-board, Fixed Continuous Monitoring)
- Off-Site (Laboratory-based)
- By Product / Equipment Type
- Turbines
- Engines
- Gear Systems
- Hydraulic Systems
- Compressors
- By Sensor / Measurement Type
- Viscosity Sensors
- Temperature Sensors
- Pressure Sensors
- Dielectric Constant Sensors
- Ferrous Debris Counters
- TAN/TBN Analyzers
- Soot and Oxidation Meters
- Water and Fuel Dilution Detectors
- By Service Offering
- Hardware and Inline Instrumentation
- Software and Analytics Platforms
- Laboratory Testing Services
- By End-user Industry
- Transportation (Road, Rail, Aviation)
- Oil and Gas
- Industrial Manufacturing
- Mining
- Power Generation
- Marine
- Aerospace and Defense
- Renewable Energy (Wind, Solar Thermal)
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- United Kingdom
- Germany
- France
- Italy
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- South Korea
- Rest of Asia-Pacific
- Middle East
- Israel
- Saudi Arabia
- United Arab Emirates
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Egypt
- Rest of Africa
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
North America led the oil condition monitoring market with 34.55% revenue share in 2025. Stringent CAFE fuel-efficiency targets and forthcoming 2027 heavy-duty engine oil viscosity standards compel fleets to adopt real-time viscometers, bolstering supplier revenue. Legacy SCADA in midstream pipelines restrains sensor retrofits, yet federal funding for critical-infrastructure upgrades may unlock latent demand.
Europe remains the technology incubator, leveraging offshore wind deployment and circular-economy regulations to push oil-life-extension solutions. The EU CSRD forces manufacturers to disclose lubricant conservation metrics, turning compliance into a board-level priority. Scandinavian shipowners also prepare for the Arctic heavy-fuel-oil ban by Transport Canada, investing in condition monitoring to ensure alternative fuels maintain viscosity within safe ranges.
Asia-Pacific is the fastest-growing region at 8.05% CAGR as industrialization, LNG fleet growth, and mining automation converge. Governments raise safety standards in petrochemical complexes, creating opportunities for cloud-linked sensors. Yet small and mid-size enterprises face capital constraints, prompting vendors to roll out leasing schemes. In emerging ASEAN markets, off-site labs still dominate, although falling hardware costs will slowly tilt share toward in-plant online sensors, expanding the overall oil condition monitoring market.
- General Electric Company
- Shell plc
- Chevron Corporation
- BP plc (Castrol)
- Exxon Mobil Corporation
- TotalEnergies SE
- Parker-Hannifin Corporation
- Eaton Corporation plc
- Emerson Electric Co.
- SKF AB
- Spectro Scientific (AMETEK Inc.)
- Intertek Group plc
- SGS SA
- Bureau Veritas SA
- ALS Limited
- Techenomics International
- TestOil (Insight Services Inc.)
- C.C. Jensen A/S
- Poseidon Systems LLC
- WearCheck International
- Delta Services Industriels (DSi)
- Lubrication Engineers Inc.
- Hy-Pro Filtration
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 OEM Warranty Mandates Extending to Oil Analytics in North America
- 4.2.2 Offshore-Wind Gearbox Failures Accelerating Inline Debris Sensors (Europe)
- 4.2.3 LNG Carrier Fleet Growth Necessitating Real-time Lube Analytics (Asia and ME)
- 4.2.4 Digital-Twin Maintenance Programs in Canadian Oil Sands
- 4.2.5 Insurance Discounts for Mining Haul Trucks with Wear Counters (Chile and Peru)
- 4.2.6 EU CSRD-Driven Oil-Life Extension Targets in Industrial Plants
- 4.3 Market Restraints
- 4.3.1 Capex Burden of Online Sensors for ASEAN SMEs
- 4.3.2 Legacy SCADA Integration Issues in US Midstream Pipelines
- 4.3.3 Shortage of Tribologists in African Power Utilities
- 4.3.4 Ferrography Consumable Supply Disruptions in Eastern Europe
- 4.4 Value / Supply-Chain Analysis
- 4.5 Regulatory and Technological Outlook
- 4.6 Porter's Five Forces Analysis
- 4.6.1 Threat of New Entrants
- 4.6.2 Bargaining Power of Buyers
- 4.6.3 Bargaining Power of Suppliers
- 4.6.4 Threat of Substitutes
- 4.6.5 Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Sampling Type
- 5.1.1 On-Site (On-board, Fixed Continuous Monitoring)
- 5.1.2 Off-Site (Laboratory-based)
- 5.2 By Product / Equipment Type
- 5.2.1 Turbines
- 5.2.2 Engines
- 5.2.3 Gear Systems
- 5.2.4 Hydraulic Systems
- 5.2.5 Compressors
- 5.3 By Sensor / Measurement Type
- 5.3.1 Viscosity Sensors
- 5.3.2 Temperature Sensors
- 5.3.3 Pressure Sensors
- 5.3.4 Dielectric Constant Sensors
- 5.3.5 Ferrous Debris Counters
- 5.3.6 TAN/TBN Analyzers
- 5.3.7 Soot and Oxidation Meters
- 5.3.8 Water and Fuel Dilution Detectors
- 5.4 By Service Offering
- 5.4.1 Hardware and Inline Instrumentation
- 5.4.2 Software and Analytics Platforms
- 5.4.3 Laboratory Testing Services
- 5.5 By End-user Industry
- 5.5.1 Transportation (Road, Rail, Aviation)
- 5.5.2 Oil and Gas
- 5.5.3 Industrial Manufacturing
- 5.5.4 Mining
- 5.5.5 Power Generation
- 5.5.6 Marine
- 5.5.7 Aerospace and Defense
- 5.5.8 Renewable Energy (Wind, Solar Thermal)
- 5.6 By Geography
- 5.6.1 North America
- 5.6.1.1 United States
- 5.6.1.2 Canada
- 5.6.1.3 Mexico
- 5.6.2 Europe
- 5.6.2.1 United Kingdom
- 5.6.2.2 Germany
- 5.6.2.3 France
- 5.6.2.4 Italy
- 5.6.2.5 Rest of Europe
- 5.6.3 Asia-Pacific
- 5.6.3.1 China
- 5.6.3.2 Japan
- 5.6.3.3 India
- 5.6.3.4 South Korea
- 5.6.3.5 Rest of Asia-Pacific
- 5.6.4 Middle East
- 5.6.4.1 Israel
- 5.6.4.2 Saudi Arabia
- 5.6.4.3 United Arab Emirates
- 5.6.4.4 Turkey
- 5.6.4.5 Rest of Middle East
- 5.6.5 Africa
- 5.6.5.1 South Africa
- 5.6.5.2 Egypt
- 5.6.5.3 Rest of Africa
- 5.6.6 South America
- 5.6.6.1 Brazil
- 5.6.6.2 Argentina
- 5.6.6.3 Rest of South America
- 5.6.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global Overview, Market Overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)
- 6.4.1 General Electric Company
- 6.4.2 Shell plc
- 6.4.3 Chevron Corporation
- 6.4.4 BP plc (Castrol)
- 6.4.5 Exxon Mobil Corporation
- 6.4.6 TotalEnergies SE
- 6.4.7 Parker-Hannifin Corporation
- 6.4.8 Eaton Corporation plc
- 6.4.9 Emerson Electric Co.
- 6.4.10 SKF AB
- 6.4.11 Spectro Scientific (AMETEK Inc.)
- 6.4.12 Intertek Group plc
- 6.4.13 SGS SA
- 6.4.14 Bureau Veritas SA
- 6.4.15 ALS Limited
- 6.4.16 Techenomics International
- 6.4.17 TestOil (Insight Services Inc.)
- 6.4.18 C.C. Jensen A/S
- 6.4.19 Poseidon Systems LLC
- 6.4.20 WearCheck International
- 6.4.21 Delta Services Industriels (DSi)
- 6.4.22 Lubrication Engineers Inc.
- 6.4.23 Hy-Pro Filtration
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-need Assessment

