PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2115104

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2115104
Europe Aircraft Engine MRO - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
According to Mordor Intelligence, Europe aircraft engine MRO market size in 2026 is estimated at USD 9.98 billion, growing from 2025 value of USD 9.62 billion with 2031 projections showing USD 11.98 billion, growing at 3.73% CAGR over 2026-2031.
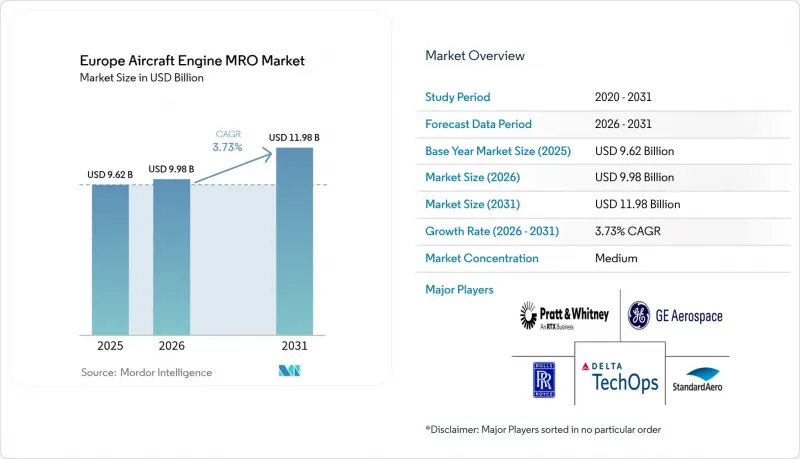
This report is Segmented by Engine Type (Turbine Engine and Piston Engine), Aviation (Commercial Aviation, Military Aviation, General Aviation, and More), Maintenance Provider Type (Airline In-House MRO, Independent Third-Party MRO, and OEM-Affiliated MRO), and Geography (United Kingdom, Germany, France, Italy, Spain, and More). The Market Forecasts are Provided in Terms of Value (USD).
Europe Aircraft Engine MRO Market Trends and Insights
Recovery in Flight Hours and Delivery Backlogs Increasing Engine Utilization
Daily traffic across European airspace rebounded to 31,000 to 34,000 flights in 2024, representing 95% of the 2019 levels, and pushing engines to accumulate cycles faster than pandemic-era forecasts had anticipated. IBA projects that regional shop visits will increase from 2,500 in 2024 to more than 3,500 in 2025, a 40% rise that strains available capacity. Delivery backlogs exceeding 14,000 aircraft worldwide keep older engines, such as the CFM56-7B, in service, while early LEAP-1A fleets enter their first performance-restoration events. Spare-engine lease rates for CFM56-7B rose to USD 100,000 per month in 2024, signaling operators' willingness to pay premiums to avoid aircraft-on-ground events.
Ageing European Aircraft Fleets Extending Engine Maintenance Cycles
A large share of A320ceo and B737NG aircraft operating in Europe has exceeded 15 years of service, and nearly half of the installed CFM56 base had not yet reached a first shop visit as of early 2024. Rolls-Royce forecasts 1,100 to 1,200 large-engine shop visits annually through the mid-term, sustaining demand despite the introduction of new-generation deliveries. Older engines also suffer more unscheduled removals, illustrated by Lufthansa Technik's 2025 uptick in surprise inductions, which further loads independent shops. Operators increasingly run end-of-lease assets to failure, transferring maintenance liability to lessors, who then source faster, lower-cost solutions.
Shortage of Skilled EASA-Certified Maintenance Personnel
EASA Part-66 licensure demands thousands of practical hours and multiple exams, creating a talent pipeline that cannot scale rapidly. Airbus forecasts that Europe will need 640,000 new technicians over the next 20 years. MTU is spending EUR 150 million (USD 175.99 million) to automate processes and expand apprenticeships in Germany, yet still warns of throughput limits. StandardAero built an in-house mechanic academy in San Antonio, a model that European shops now emulate. High-pressure turbine blade repair and non-destructive testing roles remain the hardest to fill.
Other drivers and restraints analyzed in the detailed report include:
- Adoption of Predictive Maintenance and Engine Health-Monitoring Systems
- EU Funding Programs Supporting Engine Efficiency and Emissions Retrofits
- Supply Chain Constraints in Life-Limited Parts and Forged Components
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Turbine engines generated 77.92% of Europe aircraft engine MRO market revenue in 2025 and are forecast to expand at a 4.39% CAGR through 2031, overtaking piston activity in absolute growth terms. Turbofans power the majority of narrowbody and widebody fleets, and LEAP shop visits are expected to triple by 2030. Hot and harsh operations compress on-wing life, further boosting demand. Safran and GE Aerospace are competing for next-generation turboshaft awards that will direct future MRO work to European hubs. Turbojet engines form a declining niche, while turboprops receive support from Avio Aero's Catalyst program. OEM-affiliated shops specialize in high-margin performance-restoration work, whereas independents compete on price and faster turnaround times. Rolls-Royce recorded an 11.6% operating margin on GBP 7.3 billion (USD 9.77 billion) civil revenue in 2023, underscoring the advantage of scale in turbine aftermarket economics.
A residual 22.08% share comes from piston engines, which serve fragmented general aviation fleets and record limited growth. Their maintenance activity remains distributed among small regional shops and does not materially alter aggregate forecasts for the Europe aircraft engine MRO market. However, hybrid-electric projects currently under EU research funding could revive interest in small-displacement piston designs configured as range extenders, potentially opening up longer-term specialization opportunities.
Complete Report Scope:
- By Engine Type
- Turbine Engine
- Turboprop Engine
- Turbofan Engine
- Turboshaft Engine
- Turbojet Engine
- Piston Engine
- Turbine Engine
- By Aviation
- Commercial Aviation
- Narrowbody
- Widebody
- Regional Jets
- Military Aviation
- Combat
- Transport
- Special Mission
- Helicopters
- General Aviation
- Business Jets
- Commercial Helicopters
- Unmanned Aerial Vehicles (UAVs)
- Commercial Aviation
- By Maintenance Provider Type
- Airline In-house MRO
- Independent Third-Party MRO
- OEM-Affiliated MRO
- By Geography
- United Kingdom
- Germany
- France
- Italy
- Spain
- Switzerland
- Rest of Europe
List of Companies Covered in this Report:
- Lufthansa Technik AG
- Rolls-Royce Holdings plc
- Pratt & Whitney (RTX Corporation)
- GE Aerospace (General Electric Company)
- Safran SA
- MTU Aero Engines AG
- Honeywell International Inc.
- Air France-KLM
- TAP Maintenance & Engineering
- IBERIA, L.A.E., S.A.
- SR Technics Switzerland Ltd.
- StandardAero Aviation Holdings, Inc.
- TARMAC AEROSAVE
- Aero Norway AS
- FL Technics
- Turkish Technic Inc.
- Industria de Turbo Propulsores, S.A.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Recovery in flight hours and delivery backlogs increasing engine utilization
- 4.2.2 Ageing European aircraft fleets extending engine maintenance cycles
- 4.2.3 Adoption of predictive maintenance and engine health monitoring systems
- 4.2.4 EU funding programs supporting engine efficiency and emissions retrofits
- 4.2.5 Open-access LEAP and GTF MRO licensing expanding independent MRO capacity
- 4.2.6 Growing aircraft leasing and fleet transitions increasing shop visit frequency
- 4.3 Market Restraints
- 4.3.1 Shortage of skilled EASA-certified maintenance personnel
- 4.3.2 Supply-chain constraints in life-limited parts and forged components
- 4.3.3 Uncertainty around SAF certification and retrofit costs for legacy engines
- 4.3.4 High energy and utility costs increasing MRO operating expenses
- 4.4 Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porters Five Forces Analysis
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Consumers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitute Products
- 4.7.5 Intensity of Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Engine Type
- 5.1.1 Turbine Engine
- 5.1.1.1 Turboprop Engine
- 5.1.1.2 Turbofan Engine
- 5.1.1.3 Turboshaft Engine
- 5.1.1.4 Turbojet Engine
- 5.1.2 Piston Engine
- 5.1.1 Turbine Engine
- 5.2 By Aviation
- 5.2.1 Commercial Aviation
- 5.2.1.1 Narrowbody
- 5.2.1.2 Widebody
- 5.2.1.3 Regional Jets
- 5.2.2 Military Aviation
- 5.2.2.1 Combat
- 5.2.2.2 Transport
- 5.2.2.3 Special Mission
- 5.2.2.4 Helicopters
- 5.2.3 General Aviation
- 5.2.3.1 Business Jets
- 5.2.3.2 Commercial Helicopters
- 5.2.4 Unmanned Aerial Vehicles (UAVs)
- 5.2.1 Commercial Aviation
- 5.3 By Maintenance Provider Type
- 5.3.1 Airline In-house MRO
- 5.3.2 Independent Third-Party MRO
- 5.3.3 OEM-Affiliated MRO
- 5.4 By Geography
- 5.4.1 United Kingdom
- 5.4.2 Germany
- 5.4.3 France
- 5.4.4 Italy
- 5.4.5 Spain
- 5.4.6 Switzerland
- 5.4.7 Rest of Europe
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 Lufthansa Technik AG
- 6.4.2 Rolls-Royce Holdings plc
- 6.4.3 Pratt & Whitney (RTX Corporation)
- 6.4.4 GE Aerospace (General Electric Company)
- 6.4.5 Safran SA
- 6.4.6 MTU Aero Engines AG
- 6.4.7 Honeywell International Inc.
- 6.4.8 Air France-KLM
- 6.4.9 TAP Maintenance & Engineering
- 6.4.10 IBERIA, L.A.E., S.A.
- 6.4.11 SR Technics Switzerland Ltd.
- 6.4.12 StandardAero Aviation Holdings, Inc.
- 6.4.13 TARMAC AEROSAVE
- 6.4.14 Aero Norway AS
- 6.4.15 FL Technics
- 6.4.16 Turkish Technic Inc.
- 6.4.17 Industria de Turbo Propulsores, S.A.
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-need Assessment

