PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2115136

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2115136
North America Aircraft Engine MRO - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
According to Mordor Intelligence, the North America aircraft engine MRO market size was valued at USD 11.23 billion in 2025 and estimated to grow from USD 11.8 billion in 2026 to reach USD 15.09 billion by 2031, at a CAGR of 5.05% during the forecast period (2026-2031).
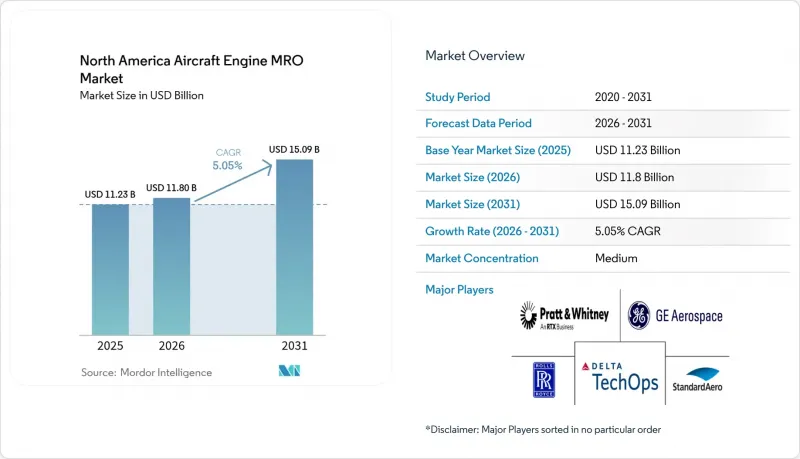
This report is Segmented by Engine Type (Turbine Engine and Piston Engine), Aviation (Commercial Aviation, Military Aviation, General Aviation, and More), Maintenance Provider Type (Airline In-House MRO, Independent Third-Party MRO, and OEM-Affiliated MRO), and Geography (United States, Canada, and Mexico). The Market Forecasts are Provided in Terms of Value (USD).
North America Aircraft Engine MRO Market Trends and Insights
Peak Fleet Aging Driving Increased Heavy Engine Maintenance Demand
More than 3,200 US narrowbody aircraft delivered between 2010 and 2015 are now 12 to 15 years old, a milestone that triggers the first complete overhauls of their CFM56-7B and V2500-A5 engines. Approximately 6,400 power plants are expected to cycle through shops over the next four years, potentially crowding capacity and increasing lease-pool demand. Airlines are also postponing retirements because of OEM delivery delays, which compresses maintenance windows and lifts the strategic value of power-by-the-hour agreements. Larger, vertically integrated MROs can fund both legacy tooling and LEAP/GTF capability, widening the gap with smaller independents. Elevated shop volumes resulting from peak aging will continue to drive turbine-engine work as the main growth driver through 2028.
Expansion of OEM Open Service Agreements Enhancing MRO Shop Accessibility
Pratt & Whitney's Certified Maintenance Provider program accepts 12 independent shops for PW1000G module work, while maintaining proprietary data control. GE Aerospace's EngineWise analytics reduce unscheduled removals by 18 to 22%, but require airlines to share operational data that deepens OEM insight into fleet usage. Safran's modular LEAP repair option reduces the cost of single visits by up to 30% and drives more frequent, lower-value interventions that anchor long-term revenue. These selective partnerships expand geographic coverage and alleviate near-term capacity bottlenecks, directing more traffic into OEM-approved channels and accelerating vertical integration in the aftermarket.
Shortage of Certified Aircraft Maintenance Technicians Increasing Turnaround Times
Retirements outpaced new FAA A&P certifications three-to-one in 2024, and the workforce is projected to shrink 6% by 2026. Experienced engine specialists now command salaries of USD 85,000 to USD 110,000 in major hubs, 20 to 25% higher than in 2022, which squeezes margins for independents. Training pipelines require 18 to 30 months, so capacity cannot be ramped up quickly when demand spikes. Automation aids parts cleaning and documentation, yet core disassembly and rebuild tasks remain labor-intensive. Persistent staffing gaps lengthen shop cycles and force operators to defer non-critical work, tempering overall market growth despite robust demand.
Other drivers and restraints analyzed in the detailed report include:
- Stricter FAA and ICAO Emissions and Noise Regulations Driving Engine Retrofit Activity
- Early-Life Reliability Issues in LEAP and GTF Engines Increasing Maintenance Visits
- Supply Chain Delays in Life-Limited Parts and Forged Components Constraining MRO Capacity
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Turbine engines generated 75.68% of the North America aircraft engine MRO market in 2025 and are forecasted to grow at a 5.99% CAGR to 2031. The North America aircraft engine MRO market size for turbine categories is therefore rising faster than overall expenditure, reflecting the heavy concentration of CFM56, LEAP, V2500, and PW1000G powerplants on narrowbody aircraft. High-thrust designs increase inspection frequency for advanced materials such as ceramic matrix composites, driving specialized repair demand that favors facilities with proprietary tooling and OEM data access.
Additive repair of turbine blades, as disclosed by GE Aerospace in 2024, reduces scrap rates and enables affiliated shops to increase throughput. Turboprop and turboshaft engines support regional airlines, offshore energy operations, and emergency medical services, where reliability takes precedence over cost. Piston powerplants serve flight training and general aviation; their more straightforward upkeep keeps most work at fixed-base operators rather than dedicated overhaul centers. Despite utilization gains in general aviation, piston activity accounts for a small portion of the North America aircraft engine MRO market.
Complete Report Scope:
- By Engine Type
- Turbine Engine
- Turboprop Engine
- Turbofan Engine
- Turboshaft Engine
- Turbojet Engine
- Piston Engine
- Turbine Engine
- By Aviation
- Commercial Aviation
- Narrowbody
- Widebody
- Regional Jets
- Military Aviation
- Combat
- Transport
- Special Mission
- Helicopters
- General Aviation
- Business Jets
- Commercial Helicopters
- Unmanned Aerial Vehicles (UAVs)
- Commercial Aviation
- By Maintenance Provider Type
- Airline In-house MRO
- Independent Third-Party MRO
- OEM-Affiliated MRO
- By Geography
- United States
- Canada
- Mexico
List of Companies Covered in this Report:
- Delta TechOps (Delta Air Lines, Inc.)
- Rolls-Royce Holdings plc
- Pratt & Whitney (RTX Corporation)
- Safran SA
- GE Aerospace (General Electric Company)
- MTU Aero Engines AG
- AAR CORP.
- Honeywell International Inc.
- IAG Aero Group
- GKN Aerospace Services Limited (Melrose plc)
- StandardAero Aviation Holdings, Inc.
- Lufthansa Technik AG
- Chromalloy Gas Turbine LLC
- Spirit AeroSystems, Inc.
- American Airlines, Inc.
- MHI RJ Aviation ULC
- GA Telesis LLC
- United Airlines, Inc.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Peak fleet aging driving increased heavy engine maintenance demand
- 4.2.2 Expansion of OEM open-service agreements enhancing MRO shop accessibility
- 4.2.3 Stricter FAA and ICAO emissions and noise regulations driving engine retrofit activity
- 4.2.4 Early-life reliability issues in LEAP and GTF engines increasing maintenance visits
- 4.2.5 Limited availability of used serviceable material driving engine and module swap-outs
- 4.2.6 Insurance-mandated post-severe weather inspections increasing unscheduled MRO events
- 4.3 Market Restraints
- 4.3.1 Shortage of certified aircraft maintenance technicians increasing turnaround times
- 4.3.2 Supply chain delays in life-limited parts and forged components constraining MRO capacity
- 4.3.3 Rising weather-related engine and nacelle damage increasing maintenance complexity
- 4.3.4 OEM controlled data access limiting cost competitiveness for independent MROs
- 4.4 Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Bargaining Power of Consumers
- 4.7.2 Bargaining Power of Suppliers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitute Products
- 4.7.5 Intensity of Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Engine Type
- 5.1.1 Turbine Engine
- 5.1.1.1 Turboprop Engine
- 5.1.1.2 Turbofan Engine
- 5.1.1.3 Turboshaft Engine
- 5.1.1.4 Turbojet Engine
- 5.1.2 Piston Engine
- 5.1.1 Turbine Engine
- 5.2 By Aviation
- 5.2.1 Commercial Aviation
- 5.2.1.1 Narrowbody
- 5.2.1.2 Widebody
- 5.2.1.3 Regional Jets
- 5.2.2 Military Aviation
- 5.2.2.1 Combat
- 5.2.2.2 Transport
- 5.2.2.3 Special Mission
- 5.2.2.4 Helicopters
- 5.2.3 General Aviation
- 5.2.3.1 Business Jets
- 5.2.3.2 Commercial Helicopters
- 5.2.4 Unmanned Aerial Vehicles (UAVs)
- 5.2.1 Commercial Aviation
- 5.3 By Maintenance Provider Type
- 5.3.1 Airline In-house MRO
- 5.3.2 Independent Third-Party MRO
- 5.3.3 OEM-Affiliated MRO
- 5.4 By Geography
- 5.4.1 United States
- 5.4.2 Canada
- 5.4.3 Mexico
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 Delta TechOps (Delta Air Lines, Inc.)
- 6.4.2 Rolls-Royce Holdings plc
- 6.4.3 Pratt & Whitney (RTX Corporation)
- 6.4.4 Safran SA
- 6.4.5 GE Aerospace (General Electric Company)
- 6.4.6 MTU Aero Engines AG
- 6.4.7 AAR CORP.
- 6.4.8 Honeywell International Inc.
- 6.4.9 IAG Aero Group
- 6.4.10 GKN Aerospace Services Limited (Melrose plc)
- 6.4.11 StandardAero Aviation Holdings, Inc.
- 6.4.12 Lufthansa Technik AG
- 6.4.13 Chromalloy Gas Turbine LLC
- 6.4.14 Spirit AeroSystems, Inc.
- 6.4.15 American Airlines, Inc.
- 6.4.16 MHI RJ Aviation ULC
- 6.4.17 GA Telesis LLC
- 6.4.18 United Airlines, Inc.
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-Need Assessment

