PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2115140

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2115140
Industrial Centrifuges - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
According to Mordor Intelligence, the industrial centrifuges market size is estimated at USD 9.19 billion in 2026, and is expected to reach USD 12.59 billion by 2031, at a CAGR of 6.49% during the forecast period (2026-2031).
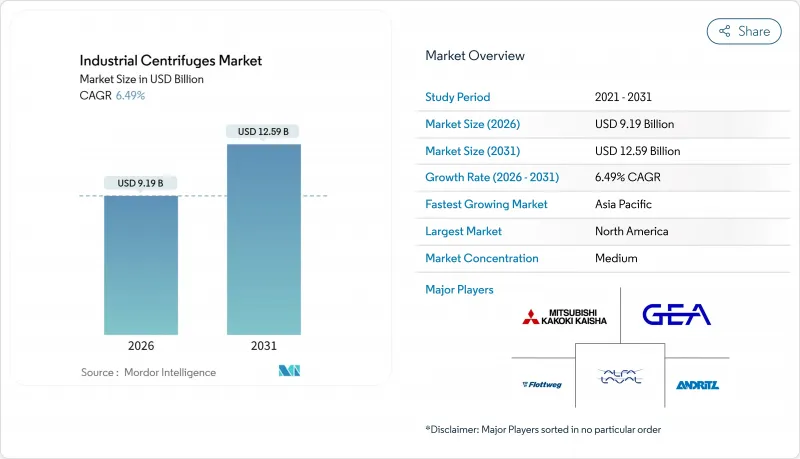
This report is Segmented by Type (Sedimentation and Filtering), Design (Horizontal and Vertical), Operation Mode (Batch and Continuous), Industry (Food and Beverages, Pharmaceutical and Biotech, Water and Wastewater Treatment, Chemical, Metals and Mining, Power Generation, Pulp and Paper, and Other Industries), and Geography (North America, Europe, Asia-Pacific, South America, and Middle East and Africa)
Global Industrial Centrifuges Market Trends and Insights
Stringent Wastewater Regulations
EPA's 40 CFR Part 437 limits are forcing centralized waste-treatment operators to adopt decanter centrifuges that yield drier cake and lower disposal volumes. China's updated Water Pollution Prevention and Control Law drives Zero Liquid Discharge installations in chemical parks, favoring compact vertical designs able to handle saline brines. In the EU, Industrial Emissions Directive updates require pulp-and-paper mills to cut suspended solids, spurring retrofits with disc-stack separators that achieve turbidity below 10 NTU. Brownfield space constraints give vertical machines an edge, while compliance deadlines stretching to 2028 anchor multi-year aftermarket demand.
Capacity Expansion in Pharma & Biotech
AGC Biologics doubled its Copenhagen capacity in 2025 and installed automated disc-stack separators that trim harvest cycle time by 40%. Grifols' FDA-approved plasma line in North Carolina employs tubular-bowl centrifuges to reach 98% immunoglobulin purity. Modular cleanrooms and single-use bioreactors fuel demand for skid-mounted vertical centrifuges, allowing contract manufacturers to switch campaigns within 72 hours. Biosimilar ramp-ups in India and South Korea extend growth, as filtering centrifuges deliver tighter particle-size control critical for bioavailability.
High Capital Expenditure
A mining-tailings decanter can cost more than USD 2 million, and installation adds up to 40% on top, pressuring operators in South America and Southeast Asia to delay purchases. European suppliers now offer pay-per-tonne contracts that shift capex onto the OEM, but uptake remains low outside pharma. Custom bowl materials push lead times past 12 months, stretching project-finance windows.
Other drivers and restraints analyzed in the detailed report include:
- Demand from F&B Clarification
- Industrial Wastewater-Reuse Mandates
- Elevated Operating & Energy Cost
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Sedimentation equipment retained 56.6% of the industrial centrifuge market share in 2025, thanks to entrenched use in mining, municipal sludge, and edible oil refining. Continuous decanters in copper-tailings ponds treat 100 m3/h and yield cake at 22% solids, while clarifiers in dairy achieve turbidity under 1 NTU. Filtering machines are forecast to grow 7.2% annually, capturing API crystallization, lithium-carbonate refining, and specialty-chemical purification. Basket units suit small-batch drug intermediates, whereas pusher designs run continuous adipic-acid crystals. Peeler centrifuges in battery-grade lithium facilities automate cake discharge and shield operators from caustic spray. As ISO 14644 cleanroom rules tighten, vertical filtering models that integrate clean-in-place features are becoming the standard in Grade C and D suites.
Both categories will coexist: sedimentation variants dominate where throughput, robustness, and low opex rule; filtering types win where purity, wash efficiency, and cake dryness directly influence product value. These divergent requirements underpin a balanced demand outlook and ensure no single technology displaces the other over the forecast window.
Horizontal layouts held 60.1% of the industrial centrifuge market in 2025, driven by mining, wastewater, and shipboard installations where floor space is abundant and low center-of-gravity designs curb vibration. Decanters process 24/7 with minimal oversight, and horizontal disc-stack models in marine fuel-oil purification prevent sludge accumulation. Vertical machines, however, are set to compound 7.6% a year, propelled by cleanroom economics that price space at USD 5,000-10,000 per square meter. AGC Biologics' Copenhagen site realized a 40% footprint saving by selecting vertical disc stacks, enabling two extra bioreactor trains within the same envelope. Vertical peeler centrifuges boost solvent containment, mitigating explosion hazards in flammable-solvent API plants. Battery-recycling lines favor vertical decanters because overhead conveyors feed slurry directly into top-mounted inlets.
The industrial centrifuge market will likely see convergence as suppliers refine hybrid geometries, tilted bowls, or modular frames that blend the space and maintenance advantages of both forms, smoothing adoption barriers across end-use sectors.
Complete Report Scope:
- By Type
- Sedimentation
- Clarifier/Thickener
- Decanter
- Disc-stack
- Hydrocyclone
- Other Sedimentation
- Filtering
- Basket
- Scroll-screen
- Peeler
- Pusher
- Other Filtering
- Sedimentation
- By Design
- Horizontal
- Vertical
- By Operation Mode
- Batch
- Continuous
- By Industry
- Food and Beverages
- Pharmaceutical and Biotech
- Water and Wastewater Treatment
- Chemical
- Metals and Mining
- Power Generation
- Pulp and Paper
- Other Industries
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- NORDIC Countries
- Russia
- Rest of Europe
- Asia-Pacific
- China
- India
- Japan
- South Korea
- ASEAN Countries
- Australia and New Zealand
- Rest of Asia-Pacific
- South America
- Brazil
- Argentina
- Chile
- Colombia
- Rest of South America
- Middle East and Africa
- United Arab Emirates
- Saudi Arabia
- Egypt
- South Africa
- Nigeria
- Rest of Middle East and Africa
- North America
Geography Analysis
North America secured 36.7% of 2025 revenue, buoyed by federal infrastructure funds, battery gigafactory buildouts, and near-shoring of critical pharma actives. Li-Cycle's Rochester and BASF's planned South Carolina sites alone will need roughly 20 industrial centrifuges for black-mass and precursor processing. Alberta's oil-sands producers invest USD 500 million annually in tailings decanters to satisfy reclamation rules, while Mexico's API hubs add hermetic disc stacks to comply with FDA and EMA standards.
Asia-Pacific is projected to log a 7.5% CAGR, the fastest global clip. China's chemical parks deployed more than 300 new decanters across 2024-2025 to meet Zero Liquid Discharge obligations. India's Hyderabad-Ahmedabad pharma corridor adopts vertical disc stacks for biosimilar lines targeting Western export markets. Japan and South Korea retrofit municipal and industrial wastewater plants with energy-saving vertical separators, and ASEAN nations scale palm-oil and rubber centrifuge capacity amid sustainability incentives.
Europe retains a sizeable share as the Industrial Emissions Directive tightens limits and the revised Urban Wastewater Treatment Directive imposes nutrient caps, compelling clarifier upgrades in municipal facilities. Energy-intensive regions like Germany favor bowl designs with regenerative braking to offset high electricity tariffs. South America sees sporadic yet high-value orders in Chilean copper and Brazilian lithium mines, while MEA water-reuse projects in the UAE and Saudi Arabia rely on disc-stack separators for desalination brine. Africa's mining belts prefer refurbished units due to foreign-exchange hurdles, keeping sales volumes low but aftermarket services active.
- Alfa Laval AB
- Flottweg SE
- Multotec (Pty) Ltd
- Mitsubishi Kakoki Kaisha Ltd
- Pieralisi MAIP S.p.A
- IHI Rotating Machinery
- Hiller Separation & Process
- Flsmidth (Escher Wyss)
- Andritz AG
- Ferrum Ltd
- Thomas Broadbent & Sons Ltd
- Centrisys Corp.
- G-Tech Separation
- FLSmidth & Co. A/S
- Hutchison-Hayes Separation
- GEA Group AG
- MSE Hiller
- HAUS Centrifuge Technologies
- Siebtechnik Tema
- SPX FLOW (Seital)
- Suez Water Technologies
- Andritz-Frautech
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Stringent wastewater regulations
- 4.2.2 Capacity expansion in pharma & biotech
- 4.2.3 Demand from F&B clarification
- 4.2.4 Industrial wastewater reuse mandates
- 4.2.5 Surge in Li-ion battery recycling lines
- 4.2.6 Scale-up of algae-based biofuel plants
- 4.3 Market Restraints
- 4.3.1 High capital expenditure
- 4.3.2 Elevated operating & energy cost
- 4.3.3 Competition from membrane tech
- 4.3.4 Shortage of skilled centrifuge operators
- 4.4 Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Rivalry
5 Market Size & Growth Forecasts
- 5.1 By Type
- 5.1.1 Sedimentation
- 5.1.1.1 Clarifier/Thickener
- 5.1.1.2 Decanter
- 5.1.1.3 Disc-stack
- 5.1.1.4 Hydrocyclone
- 5.1.1.5 Other Sedimentation
- 5.1.2 Filtering
- 5.1.2.1 Basket
- 5.1.2.2 Scroll-screen
- 5.1.2.3 Peeler
- 5.1.2.4 Pusher
- 5.1.2.5 Other Filtering
- 5.1.1 Sedimentation
- 5.2 By Design
- 5.2.1 Horizontal
- 5.2.2 Vertical
- 5.3 By Operation Mode
- 5.3.1 Batch
- 5.3.2 Continuous
- 5.4 By Industry
- 5.4.1 Food and Beverages
- 5.4.2 Pharmaceutical and Biotech
- 5.4.3 Water and Wastewater Treatment
- 5.4.4 Chemical
- 5.4.5 Metals and Mining
- 5.4.6 Power Generation
- 5.4.7 Pulp and Paper
- 5.4.8 Other Industries
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 Europe
- 5.5.2.1 Germany
- 5.5.2.2 United Kingdom
- 5.5.2.3 France
- 5.5.2.4 Italy
- 5.5.2.5 Spain
- 5.5.2.6 NORDIC Countries
- 5.5.2.7 Russia
- 5.5.2.8 Rest of Europe
- 5.5.3 Asia-Pacific
- 5.5.3.1 China
- 5.5.3.2 India
- 5.5.3.3 Japan
- 5.5.3.4 South Korea
- 5.5.3.5 ASEAN Countries
- 5.5.3.6 Australia and New Zealand
- 5.5.3.7 Rest of Asia-Pacific
- 5.5.4 South America
- 5.5.4.1 Brazil
- 5.5.4.2 Argentina
- 5.5.4.3 Chile
- 5.5.4.4 Colombia
- 5.5.4.5 Rest of South America
- 5.5.5 Middle East and Africa
- 5.5.5.1 United Arab Emirates
- 5.5.5.2 Saudi Arabia
- 5.5.5.3 Egypt
- 5.5.5.4 South Africa
- 5.5.5.5 Nigeria
- 5.5.5.6 Rest of Middle East and Africa
- 5.5.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves (M&A, Partnerships, PPAs)
- 6.3 Market Share Analysis (Market Rank/Share for key companies)
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Products & Services, and Recent Developments)
- 6.4.1 Alfa Laval AB
- 6.4.2 Flottweg SE
- 6.4.3 Multotec (Pty) Ltd
- 6.4.4 Mitsubishi Kakoki Kaisha Ltd
- 6.4.5 Pieralisi MAIP S.p.A
- 6.4.6 IHI Rotating Machinery
- 6.4.7 Hiller Separation & Process
- 6.4.8 Flsmidth (Escher Wyss)
- 6.4.9 Andritz AG
- 6.4.10 Ferrum Ltd
- 6.4.11 Thomas Broadbent & Sons Ltd
- 6.4.12 Centrisys Corp.
- 6.4.13 G-Tech Separation
- 6.4.14 FLSmidth & Co. A/S
- 6.4.15 Hutchison-Hayes Separation
- 6.4.16 GEA Group AG
- 6.4.17 MSE Hiller
- 6.4.18 HAUS Centrifuge Technologies
- 6.4.19 Siebtechnik Tema
- 6.4.20 SPX FLOW (Seital)
- 6.4.21 Suez Water Technologies
- 6.4.22 Andritz-Frautech
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-need Assessment

