PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2115182

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2115182
Power Plant Control System - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
According to Mordor Intelligence, the power plant control system market size is estimated at USD 10.11 billion in 2026, and is expected to reach USD 14.04 billion by 2031, at a CAGR of 6.79% during the forecast period (2026-2031).
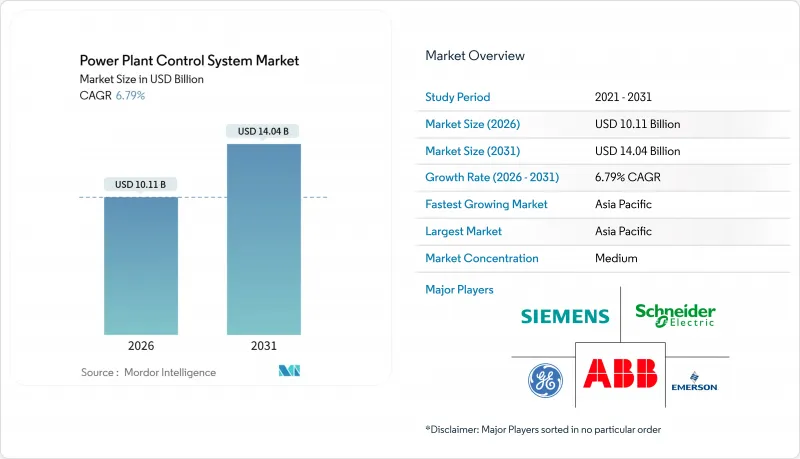
This report is Segmented by Solution (Supervisory Control and Data Acquisition, Distributed Control System, Plant Asset Management, and More), Component (Hardware and Software), Plant Type (Thermal, Nuclear, and Renewables), and Geography (North America, Europe, Asia-Pacific, South America, and Middle East and Africa). The Market Sizes and Forecasts are Provided in Terms of Value (USD).
Global Power Plant Control System Market Trends and Insights
Rising Integration of Renewables in Energy Mix
Variable renewables already provide more than 30% of installed capacity across OECD countries, exposing grid operators to 15-minute solar ramps of up to 40% that legacy governors cannot counteract. New SCADA deployments aggregate distributed solar, wind, and battery assets into dispatchable blocks, allowing control centers to issue ramp commands without on-site intervention. Utilities are migrating from serial links to IEC 61850 Ethernet backbones so that substations and generation units exchange data within sub-cycle intervals. The driver influence peaks between 2027 and 2029 as offshore wind in the North Sea and solar parks in Rajasthan adopt centralized control rooms.
Upgrade and Modernization of Aging Power Plants
Roughly 60% of coal-fired capacity in the United States and Europe exceeded 40 years in service by 2025, steering owners toward digital retrofits that extend life by up to two decades while achieving tighter emissions limits. Constellation Energy earmarked USD 167 million in January 2026 to replace analog panels with digital instrumentation at its Limerick nuclear station, enabling remote coolant monitoring and automated load following. The economic argument is compelling: retrofits that cost USD 50 million per 500 MW unit defer the USD 1 billion replacement expense.
High Capex and Complex Integration
Retrofitting a 500 MW coal unit typically costs USD 40-60 million, an outlay competing with cheaper renewable additions. Integrating new SCADA with 1990s-era PLCs requires custom middleware that adds 6-12 months to commissioning, as seen at Poland's Belchatow power station, where phased cutovers kept half the units on analog controls through 2025.
Other drivers and restraints analyzed in the detailed report include:
- Digitalization and IIoT Adoption Across Utilities
- AI-Driven Predictive Maintenance Analytics
- Semiconductor Supply-Chain Constraints
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
SCADA captured only 27.5% in 2025 but is forecast to grow at an 8.1% CAGR, the fastest among solutions, as utilities pursue wide-area visibility that balances renewables across portfolios. Distributed Control Systems retained 42.6% and remain indispensable for sub-second loop control in thermal and nuclear units. The Power Plant Control System market size for SCADA solutions is projected to reach USD 5.1 billion by 2031, reflecting the escalating need for virtual power plant coordination. Vendors such as GE Vernova now embed mixed-integer optimization in dispatch centers, enabling operators to adjust setpoints every five minutes. SCADA growth illustrates the market's shift from plant-centric automation to fleet-level orchestration.
The acceleration has strategic consequences. Utilities once focused on boiler or turbine efficiency; now they assemble 50-100 assets into a single dispatchable block. GE Vernova's 2025 installation in Saudi Arabia aggregated 12 GW of capacity, slashing peak-period fuel consumption by 7%. Such use cases were out of reach for traditional DCS that lacked the networking and compute muscle required for geographically dispersed assets. Consequently, SCADA is set to narrow the gap with DCS in the Power Plant Control System market through 2031.
Complete Report Scope:
- By Solution
- Supervisory Control and Data Acquisition (SCADA)
- Programmable Logic Controller (PLC)
- Distributed Control System (DCS)
- Plant Asset Management (PAM)
- Plant Lifecycle Management (PLM)
- By Component
- Hardware
- Software
- By Plant Type
- Thermal
- Nuclear
- Renewables
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- NORDIC Countries
- Russia
- Rest of Europe
- Asia-Pacific
- China
- India
- Japan
- South Korea
- ASEAN Countries
- Australia and New Zealand
- Rest of Asia-Pacific
- South America
- Brazil
- Argentina
- Colombia
- Rest of South America
- Middle East and Africa
- Saudi Arabia
- United Arab Emirates
- South Africa
- Egypt
- Rest of Middle East and Africa
- North America
Geography Analysis
Asia-Pacific led with a 37.1% share in 2025 and is projected to grow at a 7.9% CAGR. India's 500 GW renewable target and China's ultra-high-voltage backbone require millisecond coordination between provincial dispatch centers and plant-level controllers. NTPC's USD 180 million order for Bharat Heavy Electricals in 2025 retrofits six coal units with digital emissions monitors, showing that thermal modernization accompanies renewable additions. China's State Grid invested USD 4.5 billion to network 120 GW of distributed solar via Huawei's FusionSolar, enabling centralized curtailment during congestion.
North America leverages Infrastructure Investment and Jobs Act funds and DOE Grid Resilience grants to harden control layers against cyber threats under NERC CIP-013. Tennessee Valley Authority's 2025 Emerson deal integrates IEC 62443 segmentation and real-time intrusion detection. Europe mandates similar rigor; Germany requires digital automation for all >100 MW plants by 2027, and Siemens Energy secured EUR 1.5 billion in Middle East contracts by exporting European best practices. The emphasis across both regions is on lifecycle-management software and continuous patching.
The Middle East and Africa register high-single-digit growth as Saudi Arabia and the UAE diversify energy portfolios. South America trails due to policy volatility, yet Brazil's Eletrobras privatization unlocks capital for hydro-control upgrades. Mature economies prioritize cybersecurity and analytics, while emerging markets focus on hardware reliability paired with vendor financing, illustrating divergent regional procurement paths within the Power Plant Control System market.
- ABB Ltd
- Siemens AG
- General Electric Company
- Emerson Electric Co.
- Schneider Electric SE
- Honeywell International Inc.
- Mitsubishi Power Ltd.
- Yokogawa Electric Corporation
- Rockwell Automation Inc.
- Toshiba Energy Systems & Solutions
- Endress+Hauser AG
- Valmet Oyj
- Hitachi Energy Ltd.
- DF Power Systems Pvt. Ltd.
- Doosan Enerbility Co., Ltd.
- Bharat Heavy Electricals Ltd. (BHEL)
- Hyundai Electric & Energy Systems
- Fuji Electric Co., Ltd.
- Ingeteam Power Technology
- WAGO Kontakttechnik GmbH
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising integration of renewables in energy-mix
- 4.2.2 Upgrade & modernization of aging power plants
- 4.2.3 Digitalization & IIoT adoption across utilities
- 4.2.4 Government incentives for grid stability & emissions cuts
- 4.2.5 Mandatory cyber-security standards for critical infrastructure
- 4.2.6 AI-driven predictive maintenance analytics
- 4.3 Market Restraints
- 4.3.1 Growing shift toward distributed energy resources
- 4.3.2 High capex & complex integration
- 4.3.3 Semiconductor supply-chain constraints
- 4.3.4 Shortage of skilled digital-control operators
- 4.4 Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Competitive Rivalry
5 Market Size & Growth Forecasts
- 5.1 By Solution
- 5.1.1 Supervisory Control and Data Acquisition (SCADA)
- 5.1.2 Programmable Logic Controller (PLC)
- 5.1.3 Distributed Control System (DCS)
- 5.1.4 Plant Asset Management (PAM)
- 5.1.5 Plant Lifecycle Management (PLM)
- 5.2 By Component
- 5.2.1 Hardware
- 5.2.2 Software
- 5.3 By Plant Type
- 5.3.1 Thermal
- 5.3.2 Nuclear
- 5.3.3 Renewables
- 5.4 By Geography
- 5.4.1 North America
- 5.4.1.1 United States
- 5.4.1.2 Canada
- 5.4.1.3 Mexico
- 5.4.2 Europe
- 5.4.2.1 Germany
- 5.4.2.2 United Kingdom
- 5.4.2.3 France
- 5.4.2.4 Italy
- 5.4.2.5 Spain
- 5.4.2.6 NORDIC Countries
- 5.4.2.7 Russia
- 5.4.2.8 Rest of Europe
- 5.4.3 Asia-Pacific
- 5.4.3.1 China
- 5.4.3.2 India
- 5.4.3.3 Japan
- 5.4.3.4 South Korea
- 5.4.3.5 ASEAN Countries
- 5.4.3.6 Australia and New Zealand
- 5.4.3.7 Rest of Asia-Pacific
- 5.4.4 South America
- 5.4.4.1 Brazil
- 5.4.4.2 Argentina
- 5.4.4.3 Colombia
- 5.4.4.4 Rest of South America
- 5.4.5 Middle East and Africa
- 5.4.5.1 Saudi Arabia
- 5.4.5.2 United Arab Emirates
- 5.4.5.3 South Africa
- 5.4.5.4 Egypt
- 5.4.5.5 Rest of Middle East and Africa
- 5.4.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves (M&A, Partnerships, PPAs)
- 6.3 Market Share Analysis (Market Rank/Share for key companies)
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Products & Services, and Recent Developments)
- 6.4.1 ABB Ltd
- 6.4.2 Siemens AG
- 6.4.3 General Electric Company
- 6.4.4 Emerson Electric Co.
- 6.4.5 Schneider Electric SE
- 6.4.6 Honeywell International Inc.
- 6.4.7 Mitsubishi Power Ltd.
- 6.4.8 Yokogawa Electric Corporation
- 6.4.9 Rockwell Automation Inc.
- 6.4.10 Toshiba Energy Systems & Solutions
- 6.4.11 Endress+Hauser AG
- 6.4.12 Valmet Oyj
- 6.4.13 Hitachi Energy Ltd.
- 6.4.14 DF Power Systems Pvt. Ltd.
- 6.4.15 Doosan Enerbility Co., Ltd.
- 6.4.16 Bharat Heavy Electricals Ltd. (BHEL)
- 6.4.17 Hyundai Electric & Energy Systems
- 6.4.18 Fuji Electric Co., Ltd.
- 6.4.19 Ingeteam Power Technology
- 6.4.20 WAGO Kontakttechnik GmbH
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-need Assessment

