PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2115210

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2115210
Europe Frozen Snacks - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
According to Mordor Intelligence, Europe frozen snacks market size in 2026 is estimated at USD 34.24 billion, growing from 2025 value of USD 32.90 billion with 2031 projections showing USD 41.83 billion, growing at 4.08% CAGR over 2026-2031.
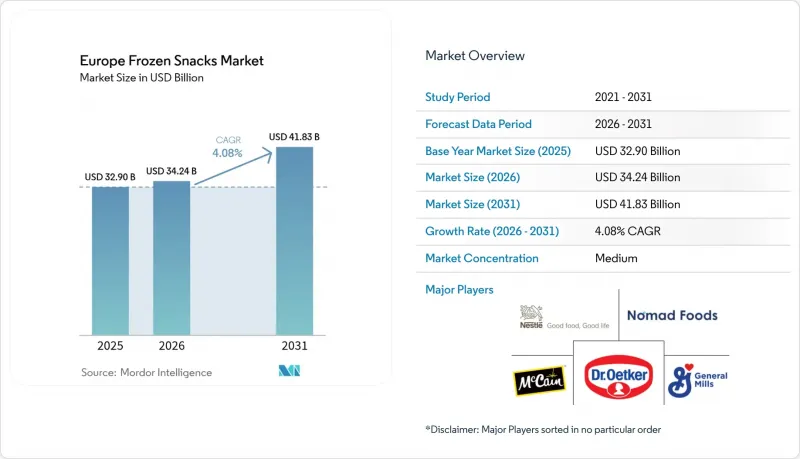
This report is Segmented by Type (Potato-Based, Meat and Poultry-Based, Seafood-Based, Fruit and Vegetable-Based, and More), Category (Conventional, Organic), Distribution Channel (HoReCa, Retail), and Geography (United Kingdom, Germany, France, Italy, Spain, Netherlands, Poland, and More). The Market Forecasts are Provided in Terms of Value (USD).
Europe Frozen Snacks Market Trends and Insights
Millennial and Gen Z Demand for On-the-Go Snacks
Millennials and Gen Z, with their fast-paced lifestyles, are driving the surge in demand for on-the-go snacks, propelling the Europe Frozen Snacks Market. These demographics prioritize convenience, gravitating towards quick meal solutions that seamlessly fit into their busy routines. With their extended shelf life, ease of storage, and simple preparation, frozen snacks have emerged as the go-to choice for these consumer groups. In 2024, the World Bank noted that 56% of the working population in Germany and 57% in the UK were female, highlighting a significant segment of consumers seeking convenient food options . The rising trend of snacking between meals, combined with a broader array of frozen options-from pizzas and pastries to finger foods-bolsters this market's expansion. Additionally, the growing diversity in product offerings caters to varying taste preferences and dietary needs, further enhancing market appeal. The retail sector's growth further amplifies this demand, ensuring frozen snacks are readily available in supermarkets, hypermarkets, and online platforms. This evolving consumer behavior underscores the pivotal influence of Millennials and Gen Z on Europe's frozen snacks landscape.
Rising Urbanization and Disposable Income
The increasing rate of urbanization and the rise in disposable income are significant drivers of the Europe frozen snacks market. According to World Bank data, urbanization in the European Union reached 76% in 2023, highlighting the growing shift of populations toward urban areas . This urban migration has led to a transformation in consumer lifestyles, with a heightened preference for convenient and ready-to-eat food products. Urban dwellers, particularly the working population, often face time constraints, making frozen snacks an appealing choice due to their ease of preparation and time-saving attributes. Additionally, higher disposable income levels across the region empower consumers to explore premium and diverse frozen snack options, further fueling market growth. The combination of these factors is expected to drive the expansion of the frozen snacks market in Europe during the forecast period.
Rising Consumer Scrutiny of Ultra-Processed Foods
Consumer awareness campaigns and scientific research are reshaping the landscape for traditional frozen snack formulations. As perceptions shift, manufacturers face the challenge of reformulating products to meet consumer expectations for taste and shelf stability. This scrutiny now extends beyond individual health concerns, with consumers increasingly weighing environmental and social responsibility in their food choices. In response, regulators are tightening labeling requirements and considering taxation mechanisms, both of which could influence product positioning and pricing. Yet, the research highlights a significant gap: many consumers struggle to accurately identify ultra-processed foods. This confusion opens doors for educational marketing and transparent communication. Manufacturers that swiftly adapt through reformulation and clear labeling stand to gain market share, outpacing competitors who cling to traditional formulations without evolving to meet these new consumer expectations.
Other drivers and restraints analyzed in the detailed report include:
- Growing Appetite for Ethnic and Global Flavors
- Boost in Potato Production Fuels Frozen Snack Expansion
- Increasing Inclination Toward Healthy Snacking Option
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
In 2025, potato-based snacks dominated the Europe frozen snacks market, capturing a 37.86% revenue share. This significant share highlights the strong consumer preference for potato-based products, driven by their versatility, taste, and widespread availability across the region. The segment benefits from continuous product innovation and the introduction of healthier options, catering to evolving consumer demands. Additionally, the convenience offered by frozen potato-based snacks, such as easy preparation and longer shelf life, has further contributed to their popularity. Key players in the market are focusing on launching new flavors and formats to attract a broader consumer base, ensuring sustained growth in this segment.
Meanwhile, fruit and vegetable-based snacks in the Europe frozen snacks market are projected to grow at a 5.56% CAGR through 2031. This growth is fueled by increasing consumer awareness of health and wellness, leading to a rising demand for nutrient-rich and natural snack options. The segment is also benefiting from the growing trend of plant-based diets, as consumers seek alternatives to traditional snack options. Manufacturers are focusing on expanding their product portfolios with innovative offerings, such as organic and minimally processed frozen snacks, to meet this growing demand. Furthermore, advancements in freezing technologies are helping to preserve the nutritional value and taste of fruit and vegetable-based snacks, enhancing their appeal to health-conscious consumers and driving the segment's expansion.
Complete Report Scope:
- By Type
- Potato-based Snacks
- Meat and Poultry-based Snacks
- Seafood-based Snacks
- Fruit- and Vegetable-based Snacks
- Cheese-based Snacks
- Bakery and Confectionery-based Snacks
- Other Types
- By Category
- Conventional
- Organic
- By Distribution Channel
- HoReCa
- Retail
- Supermarkets/Hypermarkets
- Convenience/Grocery Stores
- Online Retail Stores
- Other Retail Channel
- By Geography
- United Kingdom
- Germany
- France
- Italy
- Spain
- Netherlands
- Poland
- Sweden
- Russia
- Rest of Europe
List of Companies Covered in this Report:
- Nomad Foods Ltd
- McCain Foods Limited
- Dr Oetker Group
- Nestle S.A
- Iceland Foods
- General Mills Inc.
- Frosta AG
- Agrafrost GmbH & Co.KG
- Consort Frozen Foods,
- Delight Foods
- The Kraft Heinz Company
- Young's Seafood
- Unilever Plc
- SudZucker AG
- Conagra Brands Inc.
- Meadowvale Vake Foods
- Hain Celestial Group
- Waitrose & Partners
- Tyson Foods Inc
- Ajinomoto Co., Inc.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Millennial & Gen Z Demand for On-the-Go Snacks
- 4.2.2 Rising Urbanization and Disposable Income
- 4.2.3 Clean Label and Free-From Products Gain Traction
- 4.2.4 Boost in Potato Production Fuels Frozen Snack Expansion
- 4.2.5 Growing Appetite for Ethnic and Global Flavors
- 4.2.6 Advancements in Freezing Technologies
- 4.3 Market Restraints
- 4.3.1 Rising Consumer Scrutiny of Ultra-Processed Foods
- 4.3.2 Increasing Inclination Toward Healthy Snacking Option
- 4.3.3 Stringent EU Regulatiopm Limiting Additive Use
- 4.3.4 High Concerns Over High Trans Fat and Sodium Content
- 4.4 Regulatory Outlook
- 4.5 Technological Outlook
- 4.6 Porter's Five Forces
- 4.6.1 Threat of New Entrants
- 4.6.2 Bargaining Power of Buyers/Consumers
- 4.6.3 Bargaining Power of Suppliers
- 4.6.4 Threat of Substitutes
- 4.6.5 Intensity of Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Type
- 5.1.1 Potato-based Snacks
- 5.1.2 Meat and Poultry-based Snacks
- 5.1.3 Seafood-based Snacks
- 5.1.4 Fruit- and Vegetable-based Snacks
- 5.1.5 Cheese-based Snacks
- 5.1.6 Bakery and Confectionery-based Snacks
- 5.1.7 Other Types
- 5.2 By Category
- 5.2.1 Conventional
- 5.2.2 Organic
- 5.3 By Distribution Channel
- 5.3.1 HoReCa
- 5.3.2 Retail
- 5.3.2.1 Supermarkets/Hypermarkets
- 5.3.2.2 Convenience/Grocery Stores
- 5.3.2.3 Online Retail Stores
- 5.3.2.4 Other Retail Channel
- 5.4 By Geography
- 5.4.1 United Kingdom
- 5.4.2 Germany
- 5.4.3 France
- 5.4.4 Italy
- 5.4.5 Spain
- 5.4.6 Netherlands
- 5.4.7 Poland
- 5.4.8 Sweden
- 5.4.9 Russia
- 5.4.10 Rest of Europe
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials, Strategic Info, Market Rank/Share, Products and Services, Recent Developments)
- 6.4.1 Nomad Foods Ltd
- 6.4.2 McCain Foods Limited
- 6.4.3 Dr Oetker Group
- 6.4.4 Nestle S.A
- 6.4.5 Iceland Foods
- 6.4.6 General Mills Inc.
- 6.4.7 Frosta AG
- 6.4.8 Agrafrost GmbH & Co.KG
- 6.4.9 Consort Frozen Foods,
- 6.4.10 Delight Foods
- 6.4.11 The Kraft Heinz Company
- 6.4.12 Young's Seafood
- 6.4.13 Unilever Plc
- 6.4.14 SudZucker AG
- 6.4.15 Conagra Brands Inc.
- 6.4.16 Meadowvale Vake Foods
- 6.4.17 Hain Celestial Group
- 6.4.18 Waitrose & Partners
- 6.4.19 Tyson Foods Inc
- 6.4.20 Ajinomoto Co., Inc.
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK

