PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2115218

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2115218
Flare Gas Recovery System - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
According to Mordor Intelligence, flare gas recovery system market size in 2026 is estimated at USD 3.97 billion, growing from 2025 value of USD 3.67 billion with 2031 projections showing USD 5.84 billion, growing at 8.07% CAGR over 2026-2031.
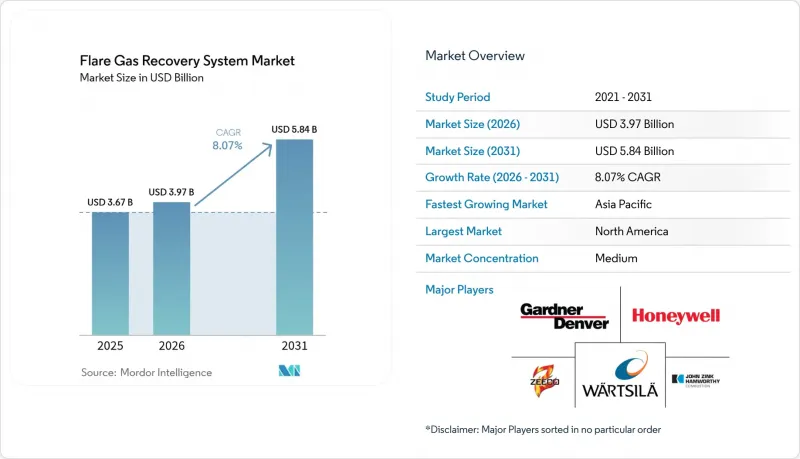
This report is Segmented by Technology (Compression-Only Systems, Membrane Separation, and More), Component (Compressors and Blowers, Instrumentation and Control Systems, and More), Capacity Range (Below 1 MMSCFD, Above 15 MMSCFD, and More), Application (Downstream, Downstream, LNG and Gas-Processing Plants, and Others), and Geography (North America, Europe, Asia-Pacific, South America, and More).
Global Flare Gas Recovery System Market Trends and Insights
Stricter global methane-emission penalties
Regulators shifted from voluntary guidelines to binding rules with escalating fees. The US EPA's NSPS OOOOb requires methane fees of USD 900-1,500 per metric ton, while the EU mandates quarterly leak-detection reports. California's amendments add a USD 40,000-per-day liability for repeat infractions, ensuring that flare gas recovery system market uptake now occurs during project design rather than after violations. Investors use methane intensity metrics in equity valuations, making recovery units essential for capital access.
Rising LNG liquefaction & FLNG projects
Asia-Pacific LNG capacity is expanding rapidly. Qatar's Joint Boil-Off Gas project integrates recovery units to reach 99.5% gas utilization. Modular "Fast LNG" plants from New Fortress Energy process 0.5-2.0 MMSCFD of waste gas, proving economically viable for small fields. Twelve FLNG vessels sanctioned in 2024 require compact, offshore-rated membranes and compressors, anchoring long-term demand.
High CAPEX vs. low associated-gas value in ultra-mature fields
Late-life offshore platforms face declining production and modest gas prices, making USD 2-5 million small-scale units hard to justify. Space constraints often double installation costs. Joint-platform sharing schemes ease the burden but rely on complex commercial agreements and short remaining asset lives.
Other drivers and restraints analyzed in the detailed report include:
- Carbon-pricing schemes linking flare credits to ESG funding
- Integration with small-scale blue-hydrogen units
- Limited cryogenic-grade gas quality in shale plays
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Compression-only systems retained 45.60% of the flare gas recovery system market share in 2025, owing to proven reliability and lower upfront costs. Membrane separation, however, is estimated to record a 12.18% CAGR, the fastest among technologies. The shift stems from tighter pipeline specifications and the ability of next-generation polymers to withstand sour-gas streams. Cryogenic condensation is a niche in ultra-high-purity applications but suffers from elevated energy demand. Absorption and adsorption maintain steady uptake in H2S-rich fields.
Hybrid solutions blending compression and membranes are gaining traction because operators optimize capex while achieving higher recovery yields. MTR's FuelSep(TM) system, deployed in the Eagle Ford in 2024, demonstrated 20% lower energy use than legacy skids while capturing C3+ liquids for resale. The flare gas recovery system market size for hybrid units is forecast to expand above the overall 8.07% baseline through 2031 as manufacturers introduce modular cartridges adaptable to changing gas quality.
Compressors and blowers dominated 39.60% of revenue in 2025, reflecting their indispensable role in creating suction and discharge pressure. Yet instrumentation and control systems will post the highest 12.05% CAGR to 2031 as facilities migrate from manual valves to autonomous loops governed by cloud analytics. Baker Hughes' flare.IQ enables operators to verify 98% combustion efficiency in real time, a capability now mandatory in several jurisdictions. Vapour recovery towers and knock-out drums follow market growth, while heat exchangers face substitution by energy-efficient chiller packages in low-temperature climates.
Complete Report Scope:
- By Technology
- Compression-only Systems
- Membrane Separation
- Cryogenic Condensation
- Absorption/Adsorption
- Hybrid (e.g., Compression + Membrane)
- By Component
- Compressors and Blowers
- Vapour Recovery Towers
- Knock-Out Drums and Separators
- Heat Exchangers/Chillers
- Instrumentation and Control Systems
- By Capacity Range
- Below 1 MMSCFD
- 1 to 5 MMSCFD
- 5 to 15 MMSCFD
- Above 15 MMSCFD
- By Application
- Upstream (Onshore and Offshore)
- Downstream (Refineries and Petrochemicals)
- LNG and Gas-processing Plants
- Others (Gas Storage, Terminals)
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- NORDIC Countries
- Russia
- Rest of Europe
- Asia-Pacific
- China
- India
- Japan
- South Korea
- ASEAN Countries
- Rest of Asia-Pacific
- South America
- Brazil
- Argentina
- Rest of South America
- Middle East and Africa
- Saudi Arabia
- United Arab Emirates
- Qatar
- South Africa
- Egypt
- Nigeria
- Rest of Middle East and Africa
- North America
Geography Analysis
North America holds 38.70% of the flare gas recovery system market size, supported by EPA rules, shale infrastructure, and readily available service networks. However, intermittent negative gas prices in the Permian Basin during 2024 prompted some operators to flare rather than sell, underlining the need for stricter enforcement. Canada's Clean Electricity Regulations and Mexico's emerging shale resources present incremental upside, though timelines diverge.
Asia-Pacific is the fastest-growing region at 11.35% CAGR. China is retrofitting refineries with carbon-capture and flare-recovery units, while India invests in gasification and LNG terminals. Southeast Asian FLNG projects and Japan and South Korea's compact-system innovations underpin sustained momentum. Government policies offering tax breaks for methane abatement further reduce payback times.
Europe shows steady uptake driven by the EU methane strategy and carbon pricing. Operators in the North Sea weigh retrofit costs against decommissioning obligations, yet many proceed because EU ETS allowances now represent a significant revenue stream. Germany's THG quota system for transport fuels creates another value pathway for recovered gas.
Middle East & Africa record selective growth. Saudi Arabia and UAE bundle flare-recovery requirements into concession agreements, ensuring early-phase deployment. Nigeria's updated commercialization programme and Iraq's GGIP establish large capture volumes. Nevertheless, financing and local-content mandates can slow procurement.
- John Zink Hamworthy Combustion LLC
- Zeeco Inc.
- Honeywell UOP
- Gardner Denver (Ingersoll Rand)
- Wartsila Oyj Abp
- Transvac Systems Ltd
- Aereon (ION Clean Air)
- Schlumberger Endura
- Air Liquide Global E&C
- MAN Energy Solutions
- Eisenmann Environmental
- SoEnergy International
- Zephyr Gas Recovery
- KPS Holdings
- Envent Corporation
- Cimarron Energy Inc.
- Cool Sorpt
- Sundyne LLC
- Ramesa Sistemas
- PetroGas Systems
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Stricter global methane-emission penalties
- 4.2.2 Rising LNG liquefaction & FLNG projects
- 4.2.3 Carbon-pricing schemes linking flare credits to ESG funding
- 4.2.4 Integration with small-scale blue-hydrogen units (syngas feed)
- 4.2.5 Mandatory flare-reduction targets in NOC production-sharing contracts
- 4.2.6 AI-enabled predictive vent-gas routing
- 4.3 Market Restraints
- 4.3.1 High CAPEX vs. low associated-gas value in ultra-mature fields
- 4.3.2 Limited cryogenic-grade gas quality in shale plays
- 4.3.3 Uncertain carbon-credit price floors (regulatory risk)
- 4.3.4 Scarcity of retrofit space on ageing offshore platforms
- 4.4 Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Competitive Rivalry
5 Market Size & Growth Forecasts
- 5.1 By Technology
- 5.1.1 Compression-only Systems
- 5.1.2 Membrane Separation
- 5.1.3 Cryogenic Condensation
- 5.1.4 Absorption/Adsorption
- 5.1.5 Hybrid (e.g., Compression + Membrane)
- 5.2 By Component
- 5.2.1 Compressors and Blowers
- 5.2.2 Vapour Recovery Towers
- 5.2.3 Knock-Out Drums and Separators
- 5.2.4 Heat Exchangers/Chillers
- 5.2.5 Instrumentation and Control Systems
- 5.3 By Capacity Range
- 5.3.1 Below 1 MMSCFD
- 5.3.2 1 to 5 MMSCFD
- 5.3.3 5 to 15 MMSCFD
- 5.3.4 Above 15 MMSCFD
- 5.4 By Application
- 5.4.1 Upstream (Onshore and Offshore)
- 5.4.2 Downstream (Refineries and Petrochemicals)
- 5.4.3 LNG and Gas-processing Plants
- 5.4.4 Others (Gas Storage, Terminals)
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 Europe
- 5.5.2.1 Germany
- 5.5.2.2 United Kingdom
- 5.5.2.3 France
- 5.5.2.4 Italy
- 5.5.2.5 NORDIC Countries
- 5.5.2.6 Russia
- 5.5.2.7 Rest of Europe
- 5.5.3 Asia-Pacific
- 5.5.3.1 China
- 5.5.3.2 India
- 5.5.3.3 Japan
- 5.5.3.4 South Korea
- 5.5.3.5 ASEAN Countries
- 5.5.3.6 Rest of Asia-Pacific
- 5.5.4 South America
- 5.5.4.1 Brazil
- 5.5.4.2 Argentina
- 5.5.4.3 Rest of South America
- 5.5.5 Middle East and Africa
- 5.5.5.1 Saudi Arabia
- 5.5.5.2 United Arab Emirates
- 5.5.5.3 Qatar
- 5.5.5.4 South Africa
- 5.5.5.5 Egypt
- 5.5.5.6 Nigeria
- 5.5.5.7 Rest of Middle East and Africa
- 5.5.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves (M&A, Partnerships, PPAs)
- 6.3 Market Share Analysis (Market Rank/Share for key companies)
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Products & Services, and Recent Developments)
- 6.4.1 John Zink Hamworthy Combustion LLC
- 6.4.2 Zeeco Inc.
- 6.4.3 Honeywell UOP
- 6.4.4 Gardner Denver (Ingersoll Rand)
- 6.4.5 Wartsila Oyj Abp
- 6.4.6 Transvac Systems Ltd
- 6.4.7 Aereon (ION Clean Air)
- 6.4.8 Schlumberger Endura
- 6.4.9 Air Liquide Global E&C
- 6.4.10 MAN Energy Solutions
- 6.4.11 Eisenmann Environmental
- 6.4.12 SoEnergy International
- 6.4.13 Zephyr Gas Recovery
- 6.4.14 KPS Holdings
- 6.4.15 Envent Corporation
- 6.4.16 Cimarron Energy Inc.
- 6.4.17 Cool Sorpt
- 6.4.18 Sundyne LLC
- 6.4.19 Ramesa Sistemas
- 6.4.20 PetroGas Systems
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-Need Assessment

