PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2116032

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2116032
Japan Thermal Power Plant - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
According to Mordor Intelligence, the Japan thermal power plant market size is expected to grow from 202.5 gigawatt in 2025 to 200.11 gigawatt in 2026 and is forecast to reach 188.45 gigawatt by 2031 at -1.18% CAGR over 2026-2031.
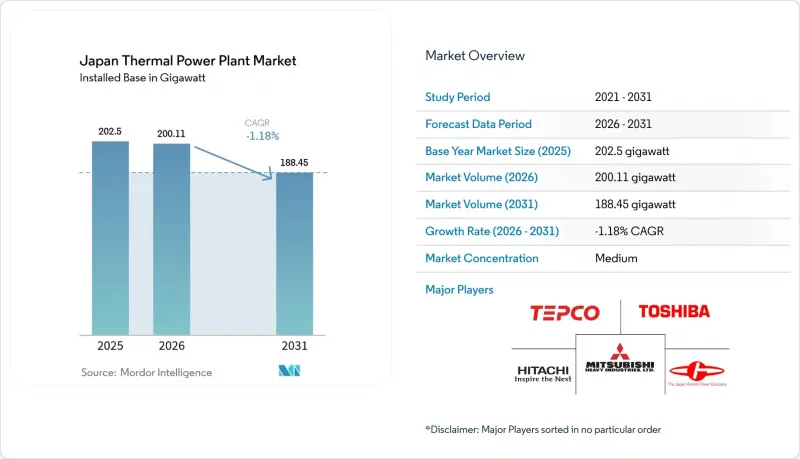
This report is Segmented by Fuel Type (Natural Gas-Fired Power Plants, and More), Technology (Steam Cycle-Based, Gas Turbine/Combined Cycle, and Combined Heat and Power), Combustion Method (Pulverized Fuel Combustion, Turbine-Based Combustion, Gasification, and More), and Application (Utility-Scale Thermal Plants, Industrial Captive Power Plants, Distributed Thermal Plants, and Peaker Plants).
Japan Thermal Power Plant Market Trends and Insights
Decommissioning of Aging Coal Fleet Accelerates Market Restructuring
Japan's thermal power plant market sees 22% of sub-critical coal units slated for closure by 2030, catalyzing demand for efficient replacements that meet tightening emission norms. Plant retirements converge with fossil-fuel levies, making shutdowns more economical than retrofits. Utilities in Kansai and Kyushu are fast-tracking CCGT and ultra-supercritical projects to secure reliable capacity and grid stability. As coal exits, investment shifts toward gas turbines that pair with battery storage and demand-response frameworks. The cycle creates construction opportunities for OEMs while lowering average fleet emissions intensity.
LNG-to-Power Capacity Additions Strengthen Energy Security Architecture
Three replacement projects delivered 6.66 GW between February 2024 and March 2025, reinforcing LNG's central role in the Japan thermal power plant market. JERA's annual procurement of 30 million t, 40% of the national supply, anchors price negotiations and hedging strategies. Coastal siting near existing terminals shortens lead times, and high-efficiency CCGTs lift fleet average thermal efficiency. Yet, domestic LNG demand dropped 25% since 2014, prompting utilities to re-export oversupply via regional trading hubs. This dual track balances domestic security with commercial flexibility.
Aggressive Renewable Capacity Targets Compress Thermal Utilization
Japan aims for renewables to exceed 36-38% of the mix by 2030, a goal led by Kyushu's solar and Tohoku's wind build-out.High penetration forces curtailment of mid-merit thermal units, shrinking run-hours, and squeezing spark-spreads. Utilities respond by mothballing older oil and sub-critical coal assets. Grid-enhancement projects, including HVDC links, aim to smooth regional imbalances yet further curtail thermal dispatch in high-renewables zones.
Other drivers and restraints analyzed in the detailed report include:
- Industrial Cogeneration Demand Driven by Manufacturing Resilience Requirements
- Carbon-Capture Pilot Incentives Create Pathways for Thermal Power Longevity
- Rising Carbon Pricing & ETS Costs Tilt Economics Away from Fossil Assets
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Natural gas accounts for 100.89 GW of the Japan thermal power market size and is projected to rise at a 1.18% CAGR to 2031. Coal retirements accelerate, illustrated by Hokkaido Electric's 600 MW closure plan, while oil units serve only emergency roles. JERA's 2.34 GW Goi plant and 1.32 GW Chita expansion anchor the shift. LNG over-contracting pressures margins, yet policy incentives and lower carbon intensity keep gas in a growth trajectory.
Despite 76% of the coal fleet being high-efficiency units, rising carbon costs and ammonia-supply uncertainty curb reinvestment appetite. If CCS pilots achieve sub-USD 100 per-tonne costs and capacity-market revenues remain stable, selected ultra-supercritical plants may survive beyond 2030.
Gas turbine/combined-cycle technology held a 48.38% share in 2025, led by HA-class turbines that reach 64% thermal efficiency. However, combined heat and power is the fastest-growing category, expanding at a 3.75% CAGR as manufacturers hedge against high tariffs. Projects by Hiroshima Gas and the Hyuga Biomass plant show 60-80% efficiency gains.
Small-to-medium CHP units from YANMAR and Aisin proliferate in chemical and steel clusters, while hydrogen household engines advance under METI's roadmap. Steam-cycle capacity declines in lockstep with coal shutdowns, and IGCC remains niche due to high levelized costs.
Complete Report Scope:
- By Fuel Type
- Coal-Fired Power Plants
- Natural Gas-Fired Power Plants
- Oil-Fired Power Plants
- By Technology
- Steam Cycle-Based
- Gas Turbine/Combined Cycle
- Combined Heat and Power (CHP)
- By Combustion Method
- Pulverized Fuel (PF) Combustion
- Fluidized Bed Combustion
- Gasification
- Internal Combustion Engines
- Turbine-Based Combustion
- By Application
- Utility-Scale Thermal Plants
- Industrial Captive Power Plants
- Distributed Thermal Plants
- Peaker Plants
List of Companies Covered in this Report:
- JERA Co., Inc.
- Kansai Electric Power Co.
- Kyushu Electric Power Co.
- Hokkaido Electric Power Co.
- Tohoku Electric Power Co.
- Chubu Electric Power Co.
- Tokyo Electric Power Company Holdings
- Electric Power Development (J-Power)
- Mitsubishi Heavy Industries Ltd.
- Toshiba Corporation
- Hitachi Ltd.
- Sumitomo Corp.
- Marubeni Corporation
- Idemitsu Kosan Co.
- ENEOS Holdings Inc.
- Osaka Gas Co. Ltd.
- Hirono IGCC Power GK
- The Chugoku Electric Power Co.
- Japan Atomic Power Company
- Sumitomo Electric Industries
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Decommissioning of aging coal fleet
- 4.2.2 LNG-to-power capacity additions
- 4.2.3 Industrial cogeneration demand
- 4.2.4 Hydrogen/Ammonia co-firing retrofits
- 4.2.5 Data-center-led baseload growth
- 4.2.6 Carbon-capture pilot incentives
- 4.3 Market Restraints
- 4.3.1 Aggressive renewable capacity targets
- 4.3.2 Rising carbon pricing & ETS costs
- 4.3.3 Coastal LNG terminal opposition
- 4.3.4 Global LNG price volatility
- 4.4 Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Bargaining Power of Suppliers
- 4.7.4 Threat of Substitutes
- 4.7.5 Competitive Rivalry
- 4.8 PESTLE Analysis
- 4.9 Key Projects (Existing/Pipeline/Upcoming)
5 Market Size & Growth Forecasts
- 5.1 By Fuel Type
- 5.1.1 Coal-Fired Power Plants
- 5.1.2 Natural Gas-Fired Power Plants
- 5.1.3 Oil-Fired Power Plants
- 5.2 By Technology
- 5.2.1 Steam Cycle-Based
- 5.2.2 Gas Turbine/Combined Cycle
- 5.2.3 Combined Heat and Power (CHP)
- 5.3 By Combustion Method
- 5.3.1 Pulverized Fuel (PF) Combustion
- 5.3.2 Fluidized Bed Combustion
- 5.3.3 Gasification
- 5.3.4 Internal Combustion Engines
- 5.3.5 Turbine-Based Combustion
- 5.4 By Application
- 5.4.1 Utility-Scale Thermal Plants
- 5.4.2 Industrial Captive Power Plants
- 5.4.3 Distributed Thermal Plants
- 5.4.4 Peaker Plants
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves (M&A, Partnerships, PPAs)
- 6.3 Market Share Analysis (Market Rank/Share for key companies)
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Products & Services, and Recent Developments)
- 6.4.1 JERA Co., Inc.
- 6.4.2 Kansai Electric Power Co.
- 6.4.3 Kyushu Electric Power Co.
- 6.4.4 Hokkaido Electric Power Co.
- 6.4.5 Tohoku Electric Power Co.
- 6.4.6 Chubu Electric Power Co.
- 6.4.7 Tokyo Electric Power Company Holdings
- 6.4.8 Electric Power Development (J-Power)
- 6.4.9 Mitsubishi Heavy Industries Ltd.
- 6.4.10 Toshiba Corporation
- 6.4.11 Hitachi Ltd.
- 6.4.12 Sumitomo Corp.
- 6.4.13 Marubeni Corporation
- 6.4.14 Idemitsu Kosan Co.
- 6.4.15 ENEOS Holdings Inc.
- 6.4.16 Osaka Gas Co. Ltd.
- 6.4.17 Hirono IGCC Power GK
- 6.4.18 The Chugoku Electric Power Co.
- 6.4.19 Japan Atomic Power Company
- 6.4.20 Sumitomo Electric Industries
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-Need Assessment

