PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2116052

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2116052
Power Management System - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
According to Mordor Intelligence, the power management system market size is expected to grow from USD 7.12 billion in 2025 to USD 7.61 billion in 2026 and is forecast to reach USD 10.62 billion by 2031 at 6.89% CAGR over 2026-2031.
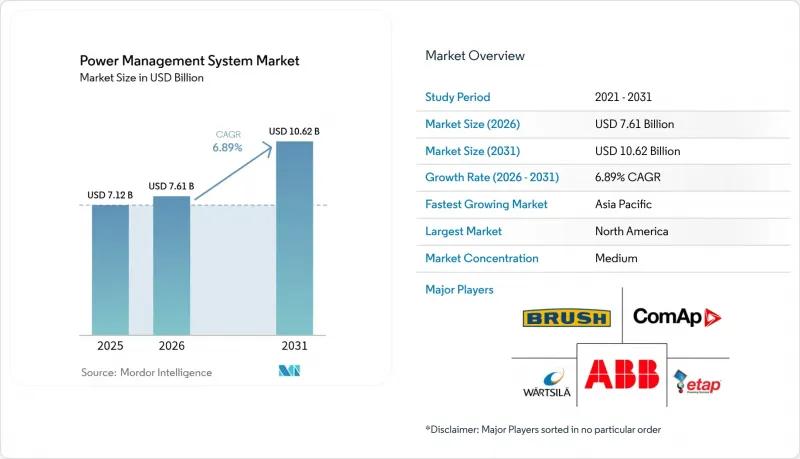
This report is Segmented by Component (Power Monitoring and Control, Load Shedding and Management, Data Historian/Advanced Analytics, and More), Power-Architecture (Centralised PMS, Distributed PMS, and Modular/Hybrid PMS), End-User Industry (Utilities, Data Centres, Oil and Gas, Marine and Offshore, and More), and Geography (North America, Europe, Asia Pacific, South America, and More).
Global Power Management System Market Trends and Insights
Regulatory Pressure for Industrial-Scale Energy Efficiency Programs
Minimum performance standards now apply to commercial furnaces in the United States, requiring 80% thermal efficiency for gas-fired units and 81% for oil-fired systems. Japan's Energy Efficiency Act obliges designated factories to appoint certified energy managers and submit annual performance reports, fostering systematic energy savings that have reached 26% in early deployments.Similar mandates across the EU accelerate digital retrofits and strengthen the power management system market as plants race to document real-time energy performance.
Rapid Renewable-Grid Integration Driving Grid-Stability Solutions
Intermittent solar and wind are forecast to supply 57% of global service-load electricity by 2050, challenging conventional frequency-control paradigms. Flexible AC transmission systems paired with hybrid storage deliver 30% stability improvements and cut total harmonic distortion below 2% compared with legacy designs. These technical gains stimulate procurement of advanced orchestration software that balances variable supply and demand across microgrids, bolstering the power management system market.
High Upfront System & Retrofit Costs
Budget constraints slow adoption in price-sensitive economies where capital recovery timelines exceed typical board expectations. Equipment plus integration outlays can exceed USD 1 million for a mid-sized plant, pressuring CFOs to delay digital retrofits. Government incentives mitigate some burden, yet financing gaps persist, temporarily tempering the expansion of the power management system market.
Other drivers and restraints analyzed in the detailed report include:
- Exponential Rise of Hyperscale & AI Data-Center Power Demand
- Wide-Bandgap (SiC/GaN) Semiconductors Slash Switching Losses
- Escalating Cyber-Security & Data-Sovereignty Risks
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Power Monitoring & Control booked USD 2.36 billion in 2025, equivalent to 33.10% of the power management system market size. Legacy SCADA platforms remain indispensable for breaker status and feeder metering; however, operators are increasingly overlaying historian databases that unlock cross-site benchmarking. Data Historian/Advanced Analytics is projected to have the quickest trajectory, with a 10.62% CAGR, reaching USD 2.66 billion by 2031, as AI-driven predictive models reduce unplanned downtime and cut energy waste. Load Shedding and Management tools leverage optimisation algorithms that trim load overcut by 30% compared to rule-based logic, sharpening industrial resiliency. Generator Controls gain relevance in microgrid deployments, with GE's PowerNode initiating protective load-sheds within 15 milliseconds while safeguarding cyber-perimeters through IEC 61850 GOOSE messaging.
Integrated suites now converge monitoring, historian, and optimisation modules into cloud-ready dashboards, steering the power management system market toward platform economics. Vendors embed secure APIs, allowing third-party developers to build applications on top of core data services. ABB's SACE Emax 3 breaker showcases this shift by exposing energy-quality metrics directly into historian pipelines. As decarbonisation mandates tighten, analytics modules quantify avoided emissions and monetise demand-response credits, elevating their share of new-build specifications.
Complete Report Scope:
- By Component
- Power Monitoring and Control
- Load Shedding and Management
- Energy Cost Accounting and Optimisation
- Switching and Safety Management
- Generator Controls
- Data Historian/Advanced Analytics
- By Power-Architecture
- Centralised PMS
- Distributed PMS
- Modular / Hybrid PMS
- By End-User Industry
- Utilities
- Data Centres
- Oil and Gas
- Marine and Offshore
- Metals and Mining
- Chemicals and Pharmaceuticals
- Others (Manufacturing, Healthcare, Telecom)
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- NORDIC Countries
- Russia
- Rest of Europe
- Asia Pacific
- China
- India
- Japan
- South Korea
- ASEAN Countries
- Rest of Asia Pacific
- South America
- Brazil
- Argentina
- Chile
- Rest of South America
- Middle East and Africa
- Saudi Arabia
- United Arab Emirates
- South Africa
- Nigeria
- Egypt
- Rest of Middle East and Africa
- North America
Geography Analysis
North America contributed 32.40% of 2025 revenue, underpinned by the Inflation Reduction Act and a pipeline of more than 30 GW in new data-center power agreements. Federal incentives have encouraged Schneider Electric to commit USD 700 million toward U.S. manufacturing expansion, enhancing domestic supply resilience. Canada's Industry Partnership for Energy Conservation sponsors ISO 50001 adoption grants, while Mexican transformer investments mitigate regional bottlenecks.
Europe maintains a stringent regulatory environment that mandates corporate sustainability reporting and tightens eco-design rules, sustaining steady demand across Germany, France, and the United Kingdom. Industrial automation upgrades in Germany deploy historian-driven OEE dashboards, whereas the U.K. pushes smart-grid pilots funded by Ofgem innovation programs. The Corporate Sustainability Reporting Directive drives enterprises to integrate granular energy data into ESG workflows, thereby strengthening the uptake of analytics throughout the power management system market.
Asia-Pacific region is poised for a 8.98% CAGR. China's national power market saw green-electricity trading exceed 220 TWh in early 2025, spurring utilities to adopt AI-enabled dispatch planning. India advances industrial energy efficiency under the Perform, Achieve, and Trade scheme and commits to achieving 11.4% transformer efficiency gains by 2027 through Japan's Top Runner collaboration. Japan's chemical clusters embrace factory-wide IIoT overlays, while Australia pilots integrated microgrids to support remote mining operations.
- ABB Ltd
- Siemens Energy
- Schneider Electric SE
- General Electric Vernova
- Mitsubishi Electric Corporation
- Eaton Corporation plc
- Emerson Electric Co.
- Wartsila Oyj Abp
- ComAp AS
- ETAP / Operation Technology Inc.
- Rockwell Automation
- Honeywell International Inc.
- Yokogawa Electric Corporation
- SEL Schweitzer Engineering Labs
- Kongsberg Gruppen ASA
- RH Marine Netherlands BV
- INTECH Process Automation Inc.
- Marine Control Services
- Delta Electronics Inc.
- Texas Instruments (PMIC business)
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Regulatory pressure for industrial?scale energy efficiency programs
- 4.2.2 Rapid renewable?grid integration driving grid-stability solutions
- 4.2.3 Exponential rise of hyperscale & AI data-center power demand
- 4.2.4 Digitalisation/IIoT enabling real-time optimisation & analytics
- 4.2.5 Wide-bandgap (SiC/GaN) semiconductors slash switching losses
- 4.2.6 Corporate PPAs create micro-grid complexity needing PMS orchestration
- 4.3 Market Restraints
- 4.3.1 High upfront system & retrofit costs
- 4.3.2 Escalating cyber-security & data-sovereignty risks
- 4.3.3 Transformer & switchgear supply-chain bottlenecks
- 4.3.4 Legacy OT/IT interoperability barriers
- 4.4 Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
5 Market Size & Growth Forecasts
- 5.1 By Component
- 5.1.1 Power Monitoring and Control
- 5.1.2 Load Shedding and Management
- 5.1.3 Energy Cost Accounting and Optimisation
- 5.1.4 Switching and Safety Management
- 5.1.5 Generator Controls
- 5.1.6 Data Historian/Advanced Analytics
- 5.2 By Power-Architecture
- 5.2.1 Centralised PMS
- 5.2.2 Distributed PMS
- 5.2.3 Modular / Hybrid PMS
- 5.3 By End-User Industry
- 5.3.1 Utilities
- 5.3.2 Data Centres
- 5.3.3 Oil and Gas
- 5.3.4 Marine and Offshore
- 5.3.5 Metals and Mining
- 5.3.6 Chemicals and Pharmaceuticals
- 5.3.7 Others (Manufacturing, Healthcare, Telecom)
- 5.4 By Geography
- 5.4.1 North America
- 5.4.1.1 United States
- 5.4.1.2 Canada
- 5.4.1.3 Mexico
- 5.4.2 Europe
- 5.4.2.1 Germany
- 5.4.2.2 United Kingdom
- 5.4.2.3 France
- 5.4.2.4 Italy
- 5.4.2.5 Spain
- 5.4.2.6 NORDIC Countries
- 5.4.2.7 Russia
- 5.4.2.8 Rest of Europe
- 5.4.3 Asia Pacific
- 5.4.3.1 China
- 5.4.3.2 India
- 5.4.3.3 Japan
- 5.4.3.4 South Korea
- 5.4.3.5 ASEAN Countries
- 5.4.3.6 Rest of Asia Pacific
- 5.4.4 South America
- 5.4.4.1 Brazil
- 5.4.4.2 Argentina
- 5.4.4.3 Chile
- 5.4.4.4 Rest of South America
- 5.4.5 Middle East and Africa
- 5.4.5.1 Saudi Arabia
- 5.4.5.2 United Arab Emirates
- 5.4.5.3 South Africa
- 5.4.5.4 Nigeria
- 5.4.5.5 Egypt
- 5.4.5.6 Rest of Middle East and Africa
- 5.4.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves (M&A, Partnerships, PPAs)
- 6.3 Market Share Analysis (Market Rank/Share for key companies)
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Products & Services, and Recent Developments)
- 6.4.1 ABB Ltd
- 6.4.2 Siemens Energy
- 6.4.3 Schneider Electric SE
- 6.4.4 General Electric Vernova
- 6.4.5 Mitsubishi Electric Corporation
- 6.4.6 Eaton Corporation plc
- 6.4.7 Emerson Electric Co.
- 6.4.8 Wartsila Oyj Abp
- 6.4.9 ComAp AS
- 6.4.10 ETAP / Operation Technology Inc.
- 6.4.11 Rockwell Automation
- 6.4.12 Honeywell International Inc.
- 6.4.13 Yokogawa Electric Corporation
- 6.4.14 SEL Schweitzer Engineering Labs
- 6.4.15 Kongsberg Gruppen ASA
- 6.4.16 RH Marine Netherlands BV
- 6.4.17 INTECH Process Automation Inc.
- 6.4.18 Marine Control Services
- 6.4.19 Delta Electronics Inc.
- 6.4.20 Texas Instruments (PMIC business)
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-Need Assessment

