PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2116279

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2116279
Veterinary Monitoring Equipment - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
According to Mordor Intelligence, the veterinary monitoring equipment market size is expected to grow from USD 2.46 billion in 2025 to USD 2.62 billion in 2026 and is forecast to reach USD 3.61 billion by 2031 at 6.59% CAGR over 2026-2031.
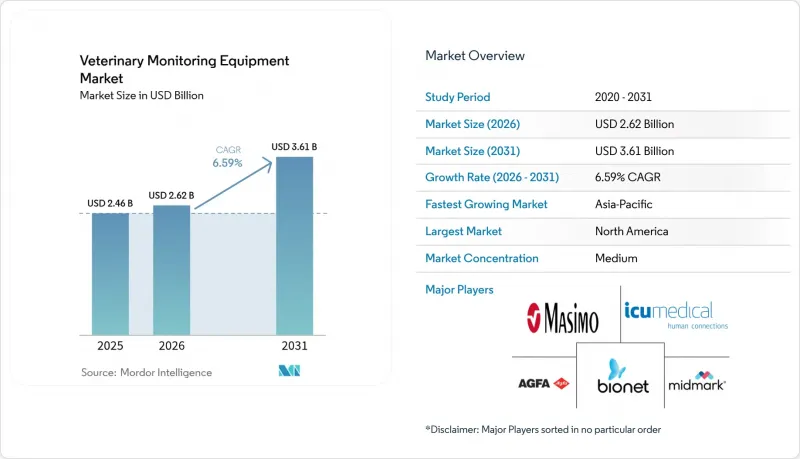
This report Segments the Industry Into by Equipment Type (Multi Parameter Monitors, Capnography Device and Oximetry Systems, and More), by Animal Type (Companion Animals and Livestock Anaimals More), by End User (Veterinary Clinics and Diagnostic Centers, and More), and Geography (North America, Europe and More). The Market Forecasts are Provided in Terms of Value (USD).
Global Veterinary Monitoring Equipment Market Trends and Insights
Rising Pet Ownership & Spending on Veterinary Care
Pet owners increasingly view animals as family and demand comprehensive, enabling clinics to position devices as wellness tools rather than episodic diagnostics. Continuous data streams reduce emergency costs and improve life-quality metrics, pushing the veterinary monitoring equipment market toward subscription-based models.
Increasing Prevalence of Chronic Animal Diseases
Diabetes, cardiac disorders, and osteoarthritis now mirror human chronic disease patterns in pets. AI-enabled collars such as PetPace 2.0 track long-term vitals and behavior, giving veterinarians granular trendlines for treatment adjustments. For cattle, early-warning systems lower mortality and feed wastage, creating multi-year device demand within the veterinary monitoring equipment market.
High Cost of Advanced Monitoring Equipment
Practice owners face equipment outlays exceeding USD 50,000 for full multi-parameter platforms and doubling ownership costs once software, maintenance, and training are included. These economics stall penetration across developing economies, tempering near-term growth in the veterinary monitoring equipment market.
Other drivers and restraints analyzed in the detailed report include:
- Technological Advances in Multi-Parameter & Wearable Monitors
- Growth in Livestock Production & Herd-Health Programs
- Limited Awareness & Adoption in Developing Regions
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Multi-parameter systems retained 35.05% veterinary monitoring equipment market share in 2025, owing to their role in anesthesia and critical-care workflows. The segment's robust clinical validation underpins purchasing, and portable form factors such as the 3-lb LifeWindow One broaden use beyond surgical suites. These platforms now integrate Wi-Fi and cloud dashboards, allowing remote specialists to review waveforms in real time. Procurement remains capital-intensive, yet leasing models and bundled service contracts sustain revenue visibility.
Wearable and remote units are the fastest-growing category at 6.88% CAGR, driving fresh penetration in home-care and extensive-farm settings. AI-driven collars, rumen boluses, and non-contact Doppler devices detect subtle physiological deviations hours before clinical symptoms appear, cutting intervention costs. Embedded telecom modules transmit encrypted data to practice management systems, embedding these devices within preventive-care plans. Battery-life breakthroughs and energy harvesting support multi-year deployment, cementing the segment's disruptive momentum within the veterinary monitoring equipment market.
Complete Report Scope:
- By Product Type (Value)
- Multi-parameter Monitors
- ECG Monitors
- Pulse-Oximeters
- Capnography Devices
- Blood-Pressure Monitors
- Wearable / Remote Monitors
- Other Products
- By Animal Type (Value)
- Companion Animals
- Dogs
- Cats
- Horses
- Others
- Livestock Animals
- Cattle
- Swine
- Poultry
- Sheep & Goats
- Others
- Companion Animals
- By End User (Value)
- Veterinary Hospitals & Clinics
- Research Institutes & Universities
- Home-care Settings
- Others
- By Geography (Value)
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- APAC
- China
- Japan
- India
- South Korea
- Australia
- Rest of APAC
- Middle East and Africa
- GCC
- South Africa
- Rest of Middle East and Africa
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
North America generated 41.95% of 2025 sales, sustained by high pet ownership rates, robust insurance penetration, and streamlined FDA pathways that encourage device launches . Companion-animal spend offsets soft clinical-visit traffic, as reflected in IDEXX's 7% organic growth and record premium-instrument placements. Canada's extensive beef and dairy sectors adopt bolus and ear-tag sensors, while Mexico's emerging middle class fuels companion-animal device uptake.
APAC is forecast to expand at 7.98% CAGR, undergirded by China's 106.2 billion-yuan pet medical market and rapid livestock modernization. Local manufacturing lowers price points, aiding diffusion across mid-tier clinics and midsize farms. Japan and South Korea advance next-gen sensor R&D, while India's dairy cooperatives pilot large-scale IoT herd-health systems. Regional governments allocate subsidies for food-safety traceability, reinforcing adoption across the veterinary monitoring equipment market.
Europe exhibits steady uptake, driven by stringent animal-welfare statutes and tele-medicine reimbursements. Germany anchors device manufacturing, the United Kingdom pioneers remote-consult frameworks, and France leverages cloud analytics to streamline dairy herd management. Eastern Europe presents greenfield opportunities as cost-optimized wearables gain traction amongst smallholder farms. Harmonized CE-marking procedures shorten time-to-market relative to other regulated regions.
- IDEXX
- Masimo
- Smiths Group
- Mindray
- Nonin Medical
- Vetland Medical
- Digicare Biomedical Technologies
- Covetrus
- Bionet America
- Midmark
- Burtons Medical Equipment
- Avante Health - DRE Veterinary
- Compumedics
- SonoScape Medical
- Vetcorder (Sentier)
- SunTech Medical
- Meridian Medical
- IMV Imaging
- Qingdao Kangjin
- Anaequip Medical
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising pet ownership & spending on veterinary care
- 4.2.2 Increasing prevalence of chronic animal diseases
- 4.2.3 Technological advances in multi-parameter & wearable monitors
- 4.2.4 Growth in livestock production & herd-health programs
- 4.2.5 AI-driven predictive analytics in monitoring devices
- 4.2.6 Regulatory push for tele-veterinary remote monitoring
- 4.3 Market Restraints
- 4.3.1 High cost of advanced monitoring equipment
- 4.3.2 Limited awareness & adoption in developing regions
- 4.3.3 Data-privacy & interoperability concerns
- 4.3.4 Battery-life & durability limits in large-animal wearables
- 4.4 Value / Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Suppliers
- 4.7.3 Bargaining Power of Buyers
- 4.7.4 Threat of Substitutes
- 4.7.5 Competitive Rivalry
5 Market Size & Growth Forecasts
- 5.1 By Product Type (Value)
- 5.1.1 Multi-parameter Monitors
- 5.1.2 ECG Monitors
- 5.1.3 Pulse-Oximeters
- 5.1.4 Capnography Devices
- 5.1.5 Blood-Pressure Monitors
- 5.1.6 Wearable / Remote Monitors
- 5.1.7 Other Products
- 5.2 By Animal Type (Value)
- 5.2.1 Companion Animals
- 5.2.1.1 Dogs
- 5.2.1.2 Cats
- 5.2.1.3 Horses
- 5.2.1.4 Others
- 5.2.2 Livestock Animals
- 5.2.2.1 Cattle
- 5.2.2.2 Swine
- 5.2.2.3 Poultry
- 5.2.2.4 Sheep & Goats
- 5.2.2.5 Others
- 5.2.1 Companion Animals
- 5.3 By End User (Value)
- 5.3.1 Veterinary Hospitals & Clinics
- 5.3.2 Research Institutes & Universities
- 5.3.3 Home-care Settings
- 5.3.4 Others
- 5.4 By Geography (Value)
- 5.4.1 North America
- 5.4.1.1 United States
- 5.4.1.2 Canada
- 5.4.1.3 Mexico
- 5.4.2 Europe
- 5.4.2.1 Germany
- 5.4.2.2 United Kingdom
- 5.4.2.3 France
- 5.4.2.4 Italy
- 5.4.2.5 Spain
- 5.4.2.6 Rest of Europe
- 5.4.3 APAC
- 5.4.3.1 China
- 5.4.3.2 Japan
- 5.4.3.3 India
- 5.4.3.4 South Korea
- 5.4.3.5 Australia
- 5.4.3.6 Rest of APAC
- 5.4.4 Middle East and Africa
- 5.4.4.1 GCC
- 5.4.4.2 South Africa
- 5.4.4.3 Rest of Middle East and Africa
- 5.4.5 South America
- 5.4.5.1 Brazil
- 5.4.5.2 Argentina
- 5.4.5.3 Rest of South America
- 5.4.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Market Share Analysis
- 6.3 Company Profiles (includes Global-level Overview, Market-level Overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products & Services, and Recent Developments)
- 6.3.1 IDEXX Laboratories
- 6.3.2 Masimo Corporation
- 6.3.3 Smiths Medical (ICU Medical)
- 6.3.4 Mindray Medical International
- 6.3.5 Nonin Medical
- 6.3.6 Vetland Medical
- 6.3.7 Digicare Biomedical
- 6.3.8 Covetrus
- 6.3.9 Bionet America
- 6.3.10 Midmark Corporation
- 6.3.11 Burtons Medical Equipment
- 6.3.12 Avante Health - DRE Veterinary
- 6.3.13 Compumedics
- 6.3.14 SonoScape Medical
- 6.3.15 Vetcorder (Sentier)
- 6.3.16 SunTech Medical
- 6.3.17 Meridian Medical
- 6.3.18 IMV Imaging
- 6.3.19 Qingdao Kangjin
- 6.3.20 Anaequip Medical
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-need Assessment

