PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2116342

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2116342
North America Drone Services - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
According to Mordor Intelligence, the North America drone services market size is expected to grow from USD 12.55 billion in 2025 to USD 15.02 billion in 2026 and is forecast to reach USD 36.76 billion by 2031 at 19.61% CAGR over 2026-2031.
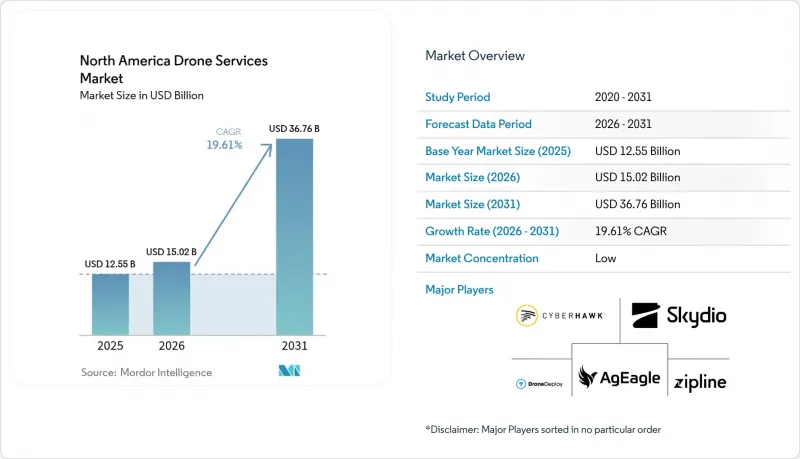
This report is Segmented by Service Type (Drone Platform Services, Maintenance, Repair and Overhaul (MRO), and More), End-User Industry (Construction and Infrastructure, Agriculture and Forestry, and More), Drone Type (Rotary-Wing, and More), Operating Range (Visual Line-Of-Sight (VLOS), and More) and Geography (United States, and More). The Market Forecasts are Provided in Terms of Value (USD).
North America Drone Services Market Trends and Insights
FAA Part 135 and BVLOS Waiver Expansion
Congressional direction required the FAA to finalize a Part 108 BVLOS framework within 20 months, transitioning from individual waivers to corporate oversight. The structure is expected to condense approval cycles from months to weeks and ultimately unlock scalable BVLOS services across the North American commercial drone services market.
Cost-Saving Construction and Infrastructure Inspection
Bridge and power-line inspections performed by drones resulted in up to 40% cost reductions and 75% faster cycle times, encouraging state transport agencies and utilities to replace crewed lifts. Georgia Power's in-house fleet of 200 drones cut inspection spending by 60% while tripling anomaly detection, reinforcing adoption in the North American commercial drone services market.
Patchwork State and Municipal Air-Rights Legislation
Local ordinances on air rights and privacy created a multilayered compliance burden that slowed multi-state roll-outs, particularly in densely populated corridors. Operators must map varying altitude limits and flight-over-people restrictions, which adds cost and dampens near-term growth in the North American commercial drone services market.
Other drivers and restraints analyzed in the detailed report include:
- Precision-Agriculture Adoption in Row-Crop Farming
- Scaling Medical and Retail Drone-Delivery Pilots
- Limited Skilled Remote-Pilot Labor Pool
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
The North American drone services market, for platform services, led with a 56.65% revenue share in 2025, reflecting the central role of piloting, data capture, and processing packages. Enterprises relied on turnkey flight teams and cloud analytics to streamline adoption, sustaining fee-based recurring revenue across energy, construction, and agriculture verticals. Hardware commoditization led providers to focus on value-added insights, and bundled service contracts contributed to expanding average deal sizes in 2025.
Training and simulation grew fastest at a 24.10% CAGR as labor shortfalls increased demand for scenario-based modules covering BVLOS procedures, swarm oversight, and advanced payload operation. Providers adopted mixed-reality simulators aligned with FAA Practical Test Standards, compressing time-to-currency and meeting insurers' proficiency requirements. As BVLOS rules mature, certification refresh programs are expected to accelerate, further lifting the North American commercial drone services market.
Construction and infrastructure held 31.62% of 2025 revenue, benefiting from measurable savings in bridge, transmission line, and pipeline inspections that reinforced steady renewal projects funded under the US Infrastructure Investment and Jobs Act. Tight labor markets and stringent safety mandates incentivized contractors to outsource aerial progress tracking, consolidating demand within the North American commercial drone services market.
Medical and parcel delivery registered the highest 25.10% CAGR. Distance-agnostic drones shortened fulfillment windows and reduced vehicle emissions, aligning with corporate ESG targets. Surgical supply networks, pharmacy chains, and mass-merchandise retailers expanded pilot programs into multi-state coverage zones after receiving route-based BVLOS authorizations, unlocking new addressable revenue streams for the North American commercial drone services industry.
Complete Report Scope:
- By Service Type
- Drone Platform Services
- Piloting and Operations
- Data Analytics
- Data Processing
- Maintenance, Repair and Overhaul (MRO)
- Training and Simulation
- Drone Platform Services
- By End User Industry
- Construction and Infrastructure
- Agriculture and Forestry
- Energy and Utilities
- Law Enforcement and Public Safety
- Medical and Parcel Delivery
- Others (Mining, Real-estate, Media)
- By Drone Type
- Rotary-wing
- Fixed-wing
- Hybrid VTOL
- By Operating Range
- Visual Line-of-Sight (VLOS)
- Beyond Visual Line-of-Sight (BVLOS)
- By Geography
- United States
- Canada
- Mexico
List of Companies Covered in this Report:
- DroneDeploy, Inc.
- Cyberhawk Innovations Limited
- Zipline International Inc.
- AgEagle Aerial Systems Inc.
- Skydio, Inc.
- SkySpecs, Inc.
- Volatus Aerospace Corp.
- DroneUp, LLC
- Aerodyne Group
- Phoenix Drone Services LLC
- Arch Aerial LLC
- Precision AI Inc.
- Sky Source Aerial
- Flytrex Inc.
- Wing Aviation LLC
- Dronegenuity, Inc.
- Agremo Ltd.
- Intertek Group plc
- Ondas Holdings Inc.
- Axon Enterprise, Inc.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 FAA Part 135 and BVLOS waiver expansion
- 4.2.2 Cost-saving construction and infrastructure inspection
- 4.2.3 Precision-agriculture adoption in row-crop farming
- 4.2.4 Scaling medical and retail drone-delivery pilots
- 4.2.5 Corporate ESG-driven shift to low-carbon aerial data
- 4.2.6 Edge-AI and 5G enabling real-time analytics as-a-service
- 4.3 Market Restraints
- 4.3.1 Patchwork state and municipal air-rights legislation
- 4.3.2 Limited skilled remote-pilot labor pool despite FAA Part 107 growth
- 4.3.3 Cyber-security vulnerabilities in C2 links deterring critical-infrastructure clients
- 4.3.4 Fragmented BVLOS regulation and waiver burden
- 4.4 Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Bargaining Power of Suppliers
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Service Type
- 5.1.1 Drone Platform Services
- 5.1.1.1 Piloting and Operations
- 5.1.1.2 Data Analytics
- 5.1.1.3 Data Processing
- 5.1.2 Maintenance, Repair and Overhaul (MRO)
- 5.1.3 Training and Simulation
- 5.1.1 Drone Platform Services
- 5.2 By End User Industry
- 5.2.1 Construction and Infrastructure
- 5.2.2 Agriculture and Forestry
- 5.2.3 Energy and Utilities
- 5.2.4 Law Enforcement and Public Safety
- 5.2.5 Medical and Parcel Delivery
- 5.2.6 Others (Mining, Real-estate, Media)
- 5.3 By Drone Type
- 5.3.1 Rotary-wing
- 5.3.2 Fixed-wing
- 5.3.3 Hybrid VTOL
- 5.4 By Operating Range
- 5.4.1 Visual Line-of-Sight (VLOS)
- 5.4.2 Beyond Visual Line-of-Sight (BVLOS)
- 5.5 By Geography
- 5.5.1 United States
- 5.5.2 Canada
- 5.5.3 Mexico
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 DroneDeploy, Inc.
- 6.4.2 Cyberhawk Innovations Limited
- 6.4.3 Zipline International Inc.
- 6.4.4 AgEagle Aerial Systems Inc.
- 6.4.5 Skydio, Inc.
- 6.4.6 SkySpecs, Inc.
- 6.4.7 Volatus Aerospace Corp.
- 6.4.8 DroneUp, LLC
- 6.4.9 Aerodyne Group
- 6.4.10 Phoenix Drone Services LLC
- 6.4.11 Arch Aerial LLC
- 6.4.12 Precision AI Inc.
- 6.4.13 Sky Source Aerial
- 6.4.14 Flytrex Inc.
- 6.4.15 Wing Aviation LLC
- 6.4.16 Dronegenuity, Inc.
- 6.4.17 Agremo Ltd.
- 6.4.18 Intertek Group plc
- 6.4.19 Ondas Holdings Inc.
- 6.4.20 Axon Enterprise, Inc.
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-Need Assessment

