PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2116353

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2116353
Asia-Pacific Healthcare Cold Chain Logistics - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
According to Mordor Intelligence, the Asia-Pacific healthcare cold chain logistics market size is expected to grow from USD 31.91 billion in 2025 to USD 33.47 billion in 2026 and is forecast to reach USD 42.5 billion by 2031 at 4.89% CAGR over 2026-2031.
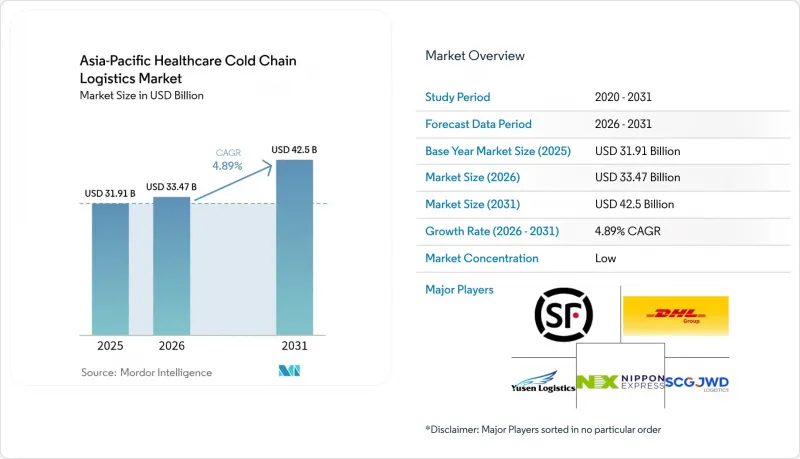
This report is Segmented by Services (Transportation, Warehousing and Distribution, Value-Added Services and Others), Temperature Type (Chilled, and More), Product (Biopharmaceuticals, Vaccines and Cell & Gene Therapies, and More), End User (Pharmaceutical Manufacturers, and More), and Geography (China, Japan, and More). The Market Forecasts are Provided in Terms of Value (USD).
Asia-Pacific Healthcare Cold Chain Logistics Market Trends and Insights
Strong Vaccine-Immunization Programs Post-COVID-19
Cold chain infrastructure built for pandemic vaccines is now redeployed for routine pharmaceuticals across the Asia Pacific healthcare cold chain logistics market. India targets USD 17 billion in vaccine revenue for 2025 amid bioeconomy expansion, supported by new vial-handling hubs, GDP-certified cross-docks, and large-scale fill-finish lines. The Philippines' Clark Freeport zone attracts more than USD 1 billion in logistics capital, providing dual-use freezer capacity for routine immunization drives and future outbreak response. DHL's global EUR 2 billion (USD 2.20 billion) healthcare program allocates 25% to Asia Pacific, underscoring corporate confidence in sustained biologics flow. These investments ensure predictive temperature monitoring, lane qualification, and redundancy, anchoring service reliability for vaccines, insulin, and specialty injectables. Governments, meanwhile, lock in long-term procurement contracts that stabilize volume demand and drive network density.
Accelerated Biologics & Cell/Gene-Therapy Pipelines
Japan cleared 43 new drugs in 2025, several being gene therapies that require below--20 °C storage, spurring specialized capacity additions at port-adjacent warehouses and express courier depots. South Korea's KoBIA supports export-ready biologics clusters near Incheon, pairing GMP manufacturing with GDP-compliant distribution corridors. Singapore's clinical-trial ecosystem relies on same-day "white-glove" transport for autologous CAR-T cells, pushing providers to integrate cryogenic dewars, data loggers, and chain-of-identity blockchain tags. Australia leverages its proximity to Asian pharma hubs, rerouting long-haul biologics freight through Sydney and Melbourne for time-critical last-mile dispatch. Collectively, these shifts elevate demand for ultra-low pallets, passive PCM packaging, and validated dry-shipper fleets, reinforcing the Asia Pacific healthcare cold chain logistics market.
Shortage of GDP-Qualified Reefer Drivers in ASEAN
Indonesia and Thailand expand paved road length yet struggle to staff trailers with GDP-trained personnel, creating a skills gap that constrains capacity during peak vaccine seasons. Certification courses demand mastery of SOPs for temperature mapping, data-logger handling, and deviation reporting, lengthening onboarding cycles compared to dry-van trucking. The Philippine market mirrors the challenge even as Clark Freeport adds modern docks; higher wages lure drivers into e-commerce, leaving fewer for pharma. Logistics firms therefore invest in accelerated training, telematics-enabled driver coaching, and retention bonuses, but near-term tightness persists, shaving throughput and damping the Asia Pacific healthcare cold chain logistics market's potential.
Other drivers and restraints analyzed in the detailed report include:
- Government Mandates on GDP-Compliant Distribution
- AI-Enabled Lane-Risk Modeling for Shipment Integrity
- High Inter-Island Freight Costs in Archipelagic Nations
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Transportation commanded 50.70% of Asia Pacific healthcare cold chain logistics market share in 2025, reflecting the indispensability of road, air, sea, and rail movement across 35,000 kilometers of maritime and land borders. Airfreight retains primacy for time-critical biologics, with Korean Air alone holding 6% of global temperature-sensitive air cargo lift. Sea logistics cater to bulk vaccines and IV solutions moving from Chinese or Indian factories to ASEAN buyers, while China's burgeoning high-speed rail corridors support 24-hour domestic pharma transits. Warehousing and distribution underpin long-haul nodes, yet value-added services temperature-validated packaging, regulatory paperwork, and control-tower analytics are slated to outpace at a 4.95% CAGR, capturing share as shippers outsource non-core compliance tasks.
Provider differentiation hinges on multimodal orchestration, GDP op-ex discipline, and tech-enabled visibility. UPS expanded cold-chain capacity by 22,000 square meters across Singapore and Australia in 2024, embedding on-site labs for pre-conditioned parcel packs. DHL integrates lane-risk dashboards into its mySupplyChain portal, delivering predictive ETA and excursion alerts. Start-ups supply SaaS overlays that consolidate passive and active tag data, enabling real-time interventions a service tier increasingly demanded across the Asia Pacific healthcare cold chain logistics market.
Chilled solutions between 0 °C and 5 °C represented 40.60% of Asia Pacific healthcare cold chain logistics market size in 2025, driven by the dominance of vaccines, insulin, and GLP-1 agonists that require narrow 2-8 °C ranges. Frozen products at -18 °C to 0 °C continue serving classical biologics, yet the ultra-low sub-segment below -20 °C registers a brisk 4.12% CAGR through 2031, propelled by cell and gene therapy clinical trial volumes. Cryoport's dry-shipper technology, which maintains -150 °C for 10 days, is in wide adoption among CAR-T sponsors shipping patient-specific doses.
Facility upgrades focus on redundant power, low-GWP refrigerants, and modular blast freezers to handle batch variability. China's refrigerant phase-out inflates CAPEX, yet accelerates adoption of R32 and CO2 trans-critical systems that offer lower energy intensity, aligning with ESG goals. Across the Asia Pacific healthcare cold chain logistics market, providers balance CAPEX efficiency with stringent mapping, pushing partnerships with OEMs for smart compressor analytics and rapid defrost cycles that preserve shelf life integrity.
Complete Report Scope:
- By Services
- Transportation
- Road
- Air
- Sea
- Rail
- Warehousing and Distribution
- Value-added Services and Others
- Transportation
- By Temperature Type
- Chilled (0-5 °C)
- Frozen (-18-0 °C)
- Ambient
- Deep-Frozen / Ultra-Low (less than-20 °C)
- By Product
- Biopharmaceuticals
- Vaccines and Cell and Gene Therapies
- Clinical Trial Materials
- Diagnostic and Laboratory Products
- Blood and Blood Products
- Others
- By End User
- Pharmaceutical Manufacturers
- Biotech and Biosimilar Manufacturers
- Hospitals and Retail Pharmacies
- Healthcare Distributors and Wholesalers
- Others
- By Country (Value)
- China
- Japan
- India
- South Korea
- Australia
- Thailand
- Indonesia
- Singapore
- Vietnam
- Rest of ASEAN
List of Companies Covered in this Report:
- DHL Group
- Yusen Logistics
- SF Express
- JWD Group
- Nippon Express
- Kerry Logistics
- Nichirei Logistics Group
- Kintetsu World Express
- YCH Group
- Sinotrans
- Sagawa Express Co., Ltd.
- Itochu Logistics Corp.
- JD Logistics
- Kuehne + Nagel
- UPS
- CEVA Logistics
- DSV
- Yamato Holdings Co., Ltd.
- Mitsubishi Logistics
- F2 Logistics Philippines
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Strong vaccine?immunization programs post-COVID-19
- 4.2.2 Accelerated biologics and cell-/gene-therapy pipelines
- 4.2.3 Government mandates on GDP-compliant distribution
- 4.2.4 Expansion of GDP-certified pharma hubs
- 4.2.5 AI-enabled lane-risk modelling for shipment integrity
- 4.2.6 Rapid GLP-1 drug boom needing 2-8 °C logistics
- 4.3 Market Restraints
- 4.3.1 Shortage of GDP-qualified reefer drivers in ASEAN
- 4.3.2 High inter-island freight costs in archipelagic nations
- 4.3.3 China's fluorocarbon-phase-out raising CAPEX
- 4.3.4 Vial-level e-pedigree compliance inflating costs
- 4.4 Value / Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
5 Market Size and Growth Forecasts
- 5.1 By Services
- 5.1.1 Transportation
- 5.1.1.1 Road
- 5.1.1.2 Air
- 5.1.1.3 Sea
- 5.1.1.4 Rail
- 5.1.2 Warehousing and Distribution
- 5.1.3 Value-added Services and Others
- 5.1.1 Transportation
- 5.2 By Temperature Type
- 5.2.1 Chilled (0-5 °C)
- 5.2.2 Frozen (-18-0 °C)
- 5.2.3 Ambient
- 5.2.4 Deep-Frozen / Ultra-Low (less than-20 °C)
- 5.3 By Product
- 5.3.1 Biopharmaceuticals
- 5.3.2 Vaccines and Cell and Gene Therapies
- 5.3.3 Clinical Trial Materials
- 5.3.4 Diagnostic and Laboratory Products
- 5.3.5 Blood and Blood Products
- 5.3.6 Others
- 5.4 By End User
- 5.4.1 Pharmaceutical Manufacturers
- 5.4.2 Biotech and Biosimilar Manufacturers
- 5.4.3 Hospitals and Retail Pharmacies
- 5.4.4 Healthcare Distributors and Wholesalers
- 5.4.5 Others
- 5.5 By Country (Value)
- 5.5.1 China
- 5.5.2 Japan
- 5.5.3 India
- 5.5.4 South Korea
- 5.5.5 Australia
- 5.5.6 Thailand
- 5.5.7 Indonesia
- 5.5.8 Singapore
- 5.5.9 Vietnam
- 5.5.10 Rest of ASEAN
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global Level Overview, Market Level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 DHL Group
- 6.4.2 Yusen Logistics
- 6.4.3 SF Express
- 6.4.4 JWD Group
- 6.4.5 Nippon Express
- 6.4.6 Kerry Logistics
- 6.4.7 Nichirei Logistics Group
- 6.4.8 Kintetsu World Express
- 6.4.9 YCH Group
- 6.4.10 Sinotrans
- 6.4.11 Sagawa Express Co., Ltd.
- 6.4.12 Itochu Logistics Corp.
- 6.4.13 JD Logistics
- 6.4.14 Kuehne + Nagel
- 6.4.15 UPS
- 6.4.16 CEVA Logistics
- 6.4.17 DSV
- 6.4.18 Yamato Holdings Co., Ltd.
- 6.4.19 Mitsubishi Logistics
- 6.4.20 F2 Logistics Philippines
7 Market Opportunities and Future Outlook
- 7.1 White-Space and Unmet-Need Assessment

