PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2116441

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2116441
UV Spectroscopy - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
According to Mordor Intelligence, UV spectroscopy market size in 2026 is estimated at USD 22.58 billion, growing from 2025 value of USD 21.52 billion with 2031 projections showing USD 28.69 billion, growing at 4.92% CAGR over 2026-2031.
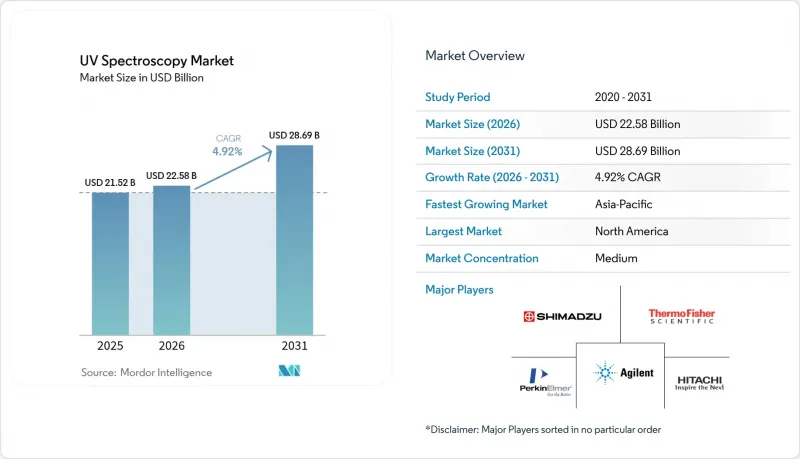
This report is Segmented by Instrument Type (Benchtop Spectrophotometers, and More), Technology (Single-Beam, and More), Application (Drug Quality Control & Release Testing, and More), End User (Pharmaceutical & Biotech Companies, and More), and Geography (North America, Europe, Asia-Pacific, Middle East & Africa, South America). The Market Forecasts are Provided in Terms of Value (USD).
Global UV Spectroscopy Market Trends and Insights
Escalating Demand for Biologics Quality Assurance
Biologics pipelines now dominate late-stage drug development, pushing the UV spectroscopy market toward higher-sensitivity protein analytics. Variable-pathlength instruments such as the Solo VPE allow direct measurement of antibody concentrations up to 300 mg/mL without sample dilution, cutting assay time from hours to minutes. Inline UV monitoring of Protein A chromatography improves host-cell-protein clearance and yields, aligning with regulators' Quality by Design expectations for real-time control. Vendors respond by integrating chemometric models that deliver concentration and purity outputs in a single scan, reducing operator workload and improving batch release speeds. As biomanufacturers scale continuous-processing platforms, demand for rugged, cleanroom-compatible UV probes should continue to rise, lifting average selling prices within the UV spectroscopy market.
Expanding Point-of-Care Diagnostic Testing Needs
Demographic shifts and the quest for faster clinical decisions are accelerating adoption of compact UV devices in decentralized settings. Microvolume nano-spectrophotometers quantify urinary albumin and creatinine at detection limits suitable for early diabetic kidney disease screening, a test traditionally confined to central laboratories. Start-ups have paired UV optics with AI algorithms to deliver bacteriological contamination results for cell therapies in under 30 minutes, replacing the 14-day sterility window typical of membrane filtration. Governments in Asia-Pacific back POC deployment to relieve hospital congestion, and instrument makers are introducing rechargeable, Bluetooth-enabled units that sync with electronic health-record platforms. This convergence between optics, microfluidics, and machine learning enlarges the UV spectroscopy market beyond classic pharmaceutical quality control.
High Capital Expenditure for GMP-Compliant Instruments
Full GMP qualification packages, 21 CFR Part 11 software, and USP <857> traceability requirements elevate upfront costs for UV platforms. A benchtop system bundled with wavelength validation kits can exceed USD 85,000, a hurdle for small manufacturers and public-sector laboratories. Even refurbished units offered under certified pre-owned programs incur added spend on re-qualification and documentation, often matching the purchase price. Emerging-market firms face higher import duties and scarce local validation expertise, extending payback periods. Unless financing tools or leasing models proliferate, these economics will curb unit penetration in the most price-sensitive tiers of the UV spectroscopy market.
Other drivers and restraints analyzed in the detailed report include:
- Regulatory Emphasis on Pharma Data Integrity
- Growth in Clinical Research and CRO Outsourcing
- Limited Skilled Workforce in Clinical Spectroscopy
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Benchtop units dominated sales with 55.12% of the UV spectroscopy market size in 2025 thanks to their superior photometric accuracy, robust qualification kits, and broad accessory ecosystems. Large pharma plants prefer standardized dual-beam platforms because they harmonize method transfer across multiple sites and align with FDA method-verification requirements. Portable/hand-held devices, however, posted the fastest unit growth at a 7.12% CAGR, fueled by POC diagnostics, on-site water testing, and raw-material verification in continuous-manufacturing suites. Vendors have improved optical layouts using micro-electromechanical mirrors and broadband frequency combs, achieving resolving power of up to 10 million-performance once limited to flagship benchtop instruments.
Competitive dynamics favor companies that combine miniaturized optics with rugged casings able to withstand cleanroom disinfectants. Cloud-ready firmware that streams encrypted spectra to centralized servers reduces data-aggregation time, a feature gaining regulatory favor. As decentralized healthcare models mature, portable formats will become mainstream, although benchtop units will keep commanding the lion's share of the UV spectroscopy market in highly regulated batch-release environments.
Dual-beam optics continued to hold 41.10% revenue share in 2025, admired for baseline stability during long analytical runs typical of stability studies. Diode-array configurations nonetheless logged a 7.33% CAGR and are positioned to outpace other designs through 2031. Their ability to capture entire spectra in milliseconds supports peak-purity checks and forced-degradation profiling, activities integral to ICH Q1 guidelines. Single-beam instruments survive in cost-sensitive labs, while deep-UV variants, operating below 200 nm, meet rising demand for high-extinction protein detection in gene-therapy research.
Instrument makers invest heavily in stray-light suppression, using holographic gratings that retain linearity even at extremely high absorbance values. Software advances embed spectral-library matching powered by machine learning, reducing manual data review by up to 40%. The blend of hardware precision and algorithmic analytics strengthens differentiation, sustaining premium price bands in this slice of the UV spectroscopy market.
Complete Report Scope:
- By Instrument Type
- Benchtop Spectrophotometers
- Microvolume Nano-Spectrophotometers
- Portable / Hand-Held Devices
- In-Line Process Sensors
- By Technology
- Single-Beam
- Dual-Beam
- Diode-Array
- Deep-UV Systems
- By Application
- Drug Quality Control & Release Testing
- Clinical Diagnostics (Blood & Urine Analysis)
- Genomics & Proteomics Quantification
- Bioprocess Monitoring & PAT
- Academic & Translational Research
- By End User
- Pharmaceutical & Biotech Companies
- Contract Research & Manufacturing Organizations (CROs/CDMOs)
- Hospitals & Diagnostic Laboratories
- Academic Medical Centers
- Public Health & Regulatory Agencies
- Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- Australia
- South Korea
- Rest of Asia-Pacific
- Middle East & Africa
- GCC
- South Africa
- Rest of Middle East & Africa
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
North America maintained the largest contribution to global revenue with 42.00% in 2025 due to robust biopharma infrastructure, stringent FDA oversight, and local manufacturing bases for major analytical brands. Government stimulus-such as the CHIPS and Science Act-further encourages domestic production of precision optics, reinforcing supply-chain resilience. Europe follows closely, propelled by harmonized EMA regulations and an expanding biologics contract-manufacturing network.
Asia-Pacific, however, delivered the strongest growth momentum at a 6.18% CAGR and is expected to account for over one-third of incremental instrument demand by 2030. India's Production-Linked Incentive scheme and China's multi-billion-dollar provincial grants for advanced therapeutics are accelerating greenfield plant construction. Shimadzu's decision to build a Karnataka factory capable of producing 10,000 UV-visible units annually from 2027 exemplifies the localization trend. Japan and South Korea sustain high unit value through continued innovation in gene and cell-therapy pipelines, while Southeast Asian states prioritize POC deployment in rural clinics.
Middle East & Africa and South America remain early-stage but show rising interest as local regulators strengthen pharmacovigilance frameworks. Brazilian ANVISA guidelines now reference USP <857>performance checks, prompting replacement of aging single-beam models. Gulf Cooperation Council countries invest in biologics fill-finish facilities within free-trade zones, driving initial orders for integrated UV monitoring skids. Collectively, these dynamics ensure the geographic spread of the UV spectroscopy market will broaden over the next five years.
- Agilent Technologies
- Thermo Fisher Scientific
- Shimadzu
- PerkinElmer
- Hitachi
- Bruker
- JASCO Inc.
- Analytik Jena GmbH
- Mettler Toledo (Implen)
- Hach Company
- Ocean Insight
- Biochrom Ltd.
- Cecil Instruments Ltd.
- Buck Scientific Inc.
- Cole-Parmer (Antylia)
- Scinco Co., Ltd.
- Metrohm
- Malvern Panalytical
- Jeol Ltd.
- Edinburgh Instruments
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Escalating Demand for Biologics Quality Assurance
- 4.2.2 Expanding Point-of-Care Diagnostic Testing Needs
- 4.2.3 Regulatory Emphasis on Pharma Data Integrity
- 4.2.4 Growth In Clinical Research and CRO Outsourcing
- 4.2.5 Integration of UV Microvolume Nano-Spectroscopy in Genomics
- 4.2.6 Adoption of Continuous Manufacturing With in-Line PAT Sensors
- 4.3 Market Restraints
- 4.3.1 High Capital Expenditure for GMP-Compliant Instruments
- 4.3.2 Limited Skilled Workforce in Clinical Spectroscopy
- 4.3.3 Stringent Validation and Calibration Protocols
- 4.3.4 Competition from Label-Free Optical Biosensors
- 4.4 Regulatory Landscape
- 4.5 Porter's Five Forces Analysis
- 4.5.1 Threat of New Entrants
- 4.5.2 Bargaining Power of Buyers
- 4.5.3 Bargaining Power of Suppliers
- 4.5.4 Threat of Substitutes
- 4.5.5 Competitive Rivalry
5 Market Size & Growth Forecasts (Value, USD)
- 5.1 By Instrument Type
- 5.1.1 Benchtop Spectrophotometers
- 5.1.2 Microvolume Nano-Spectrophotometers
- 5.1.3 Portable / Hand-Held Devices
- 5.1.4 In-Line Process Sensors
- 5.2 By Technology
- 5.2.1 Single-Beam
- 5.2.2 Dual-Beam
- 5.2.3 Diode-Array
- 5.2.4 Deep-UV Systems
- 5.3 By Application
- 5.3.1 Drug Quality Control & Release Testing
- 5.3.2 Clinical Diagnostics (Blood & Urine Analysis)
- 5.3.3 Genomics & Proteomics Quantification
- 5.3.4 Bioprocess Monitoring & PAT
- 5.3.5 Academic & Translational Research
- 5.4 By End User
- 5.4.1 Pharmaceutical & Biotech Companies
- 5.4.2 Contract Research & Manufacturing Organizations (CROs/CDMOs)
- 5.4.3 Hospitals & Diagnostic Laboratories
- 5.4.4 Academic Medical Centers
- 5.4.5 Public Health & Regulatory Agencies
- 5.5 Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 Europe
- 5.5.2.1 Germany
- 5.5.2.2 United Kingdom
- 5.5.2.3 France
- 5.5.2.4 Italy
- 5.5.2.5 Spain
- 5.5.2.6 Rest of Europe
- 5.5.3 Asia-Pacific
- 5.5.3.1 China
- 5.5.3.2 Japan
- 5.5.3.3 India
- 5.5.3.4 Australia
- 5.5.3.5 South Korea
- 5.5.3.6 Rest of Asia-Pacific
- 5.5.4 Middle East & Africa
- 5.5.4.1 GCC
- 5.5.4.2 South Africa
- 5.5.4.3 Rest of Middle East & Africa
- 5.5.5 South America
- 5.5.5.1 Brazil
- 5.5.5.2 Argentina
- 5.5.5.3 Rest of South America
- 5.5.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Market Share Analysis
- 6.3 Company Profiles (Includes Global Level Overview, Market Level Overview, Core Segments, Financials As Available, Strategic Information, Market Rank/Share, Products & Services, Recent Developments)
- 6.3.1 Agilent Technologies, Inc.
- 6.3.2 Thermo Fisher Scientific, Inc.
- 6.3.3 Shimadzu Corporation
- 6.3.4 PerkinElmer Inc.
- 6.3.5 Hitachi High-Tech Corporation
- 6.3.6 Bruker Corporation
- 6.3.7 JASCO Inc.
- 6.3.8 Analytik Jena GmbH
- 6.3.9 Mettler Toledo (Implen)
- 6.3.10 Hach Company
- 6.3.11 Ocean Insight
- 6.3.12 Biochrom Ltd.
- 6.3.13 Cecil Instruments Ltd.
- 6.3.14 Buck Scientific Inc.
- 6.3.15 Cole-Parmer (Antylia)
- 6.3.16 Scinco Co., Ltd.
- 6.3.17 Metrohm AG
- 6.3.18 Malvern Panalytical
- 6.3.19 Jeol Ltd.
- 6.3.20 Edinburgh Instruments
7 Market Opportunities & Future Outlook
- 7.1 White-Space & Unmet-Need Assessment

