PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2116639

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2116639
Global Tacrolimus - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
According to Mordor Intelligence, the tacrolimus market size was valued at USD 7.39 billion in 2025 and estimated to grow from USD 7.75 billion in 2026 to reach USD 9.86 billion by 2031, at a CAGR of 4.92% during the forecast period (2026-2031).
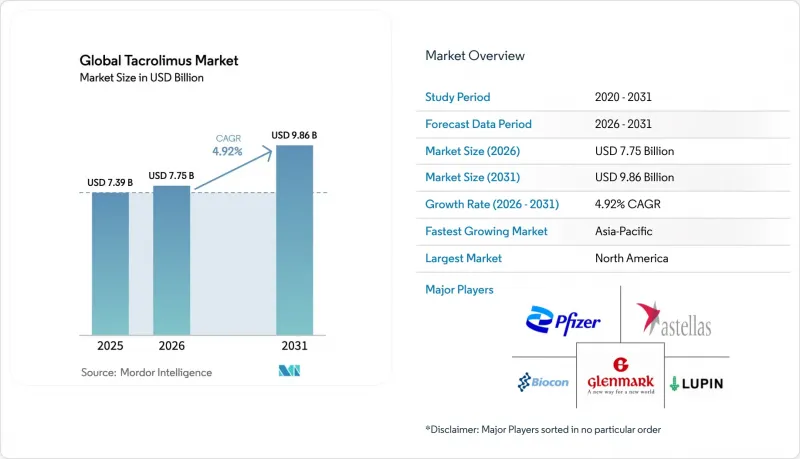
This report is Segmented by Formulation (Extended Release, Topical Ointment, Intravenous, Oral, Others), Application (Organ Transplant, Autoimmune Diseases, Dermatological Conditions), End-User (Hospitals & Transplant Centers, Specialty Clinics, Dermatology Clinics, Ambulatory Surgery Centers), and Geography (North America, Europe, and More). The Market Forecasts are Provided in Terms of Value (USD).
Global Tacrolimus Market Trends and Insights
Surging Post-Transplant Survival Rates Boost Long-Term Drug Use
Ten-year kidney graft survival now exceeds 85%, giving patients much longer exposure to maintenance immunosuppression. Higher survival translates into 40-60% more lifetime tacrolimus doses per recipient, enlarging recurring revenue streams for both innovators and generics. Clinicians increasingly choose once-daily extended-release variants, which improve adherence by simplifying complex pill schedules. Parallel growth in digital TDM platforms allows remote dose adjustment and reduces hospitalization linked to toxicity. Together, these shifts secure durable volume gains for tacrolimus through at least the next decade.
Therapeutic Migration from Cyclosporine to Tacrolimus
Large meta-analyses confirm lower acute rejection, reduced nephrotoxicity, and fewer cardiovascular events when tacrolimus replaces cyclosporine. In response, global transplant guidelines have revised first-line protocols, and more than 80% of liver-graft centers now open with tacrolimus. Rapid generic entry in Asia-Pacific removes historical cost barriers, enabling lower-income health systems to modernize regimens quickly. Hospitals also report shorter post-operative stays because tacrolimus minimizes early complications, freeing scarce ICU beds. These clinical and economic advantages sustain the formulation's steady capture of cyclosporine share.
TDM Cost Burden
Tacrolimus requires a narrow therapeutic-index check, and monthly assays cost USD 100-200 per test, straining payer budgets in price-sensitive systems. These cumulative expenses can surpass drug acquisition costs within five years for many transplant patients. Rural hospitals across Latin America and Africa often lack calibrated chromatography platforms, forcing patients to travel long distances for blood draws. Dried-blood-spot kits reduce logistics hurdles but still rely on centralized laboratories, offering only partial relief. Until affordable point-of-care analyzers scale globally, high monitoring charges will continue to curb tacrolimus adoption in developing regions.
Other drivers and restraints analyzed in the detailed report include:
- Rapid Regulatory Acceptance of Extended-Release Variants
- Escalating Autoimmune Disease Prevalence
- Extended-Release Patent Moats Slow Price Erosion
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Extended-release variants held 28.56% of tacrolimus market share in 2025 and generated USD 2.11 billion of tacrolimus market size that year. Superior pharmacokinetics flatten peak-to-trough swings, lowering rejection episodes and supporting once-daily adherence. Intravenous preparations, though smaller in value, are advancing at a 8.79% CAGR on wider adoption for peri-operative induction in kidney and liver grafts. Immediate-release oral generics defend volume in maintenance therapy but feel price pressure as payers bundle purchasing contracts.
Manufacturers are investing in nanocapsule suspensions, transdermal patches, and biodegradable ocular implants that promise week-long or month-long release. Coating lines capable of real-time dissolution analytics allow innovators to lock in quality differentiation and deter rapid generic replication. Pilots with 3-D-printed mini-tablets show accurate micro-dosing for paediatric use, an area still underserved by current capsule strengths. Regulatory agencies have signalled willingness to use adaptive review pathways for such technologies, provided plasma-level variability remains within established bioequivalence limits. These innovations collectively raise the technical bar for market entry while enlarging the future addressable base of complex-need patients.
Complete Report Scope:
- By Formulation (Value)
- Extended Release
- Topical Ointment
- Intravenous
- Oral
- Others
- By Application (Value)
- Organ Transplant
- Kidney Transplant
- Liver Transplant
- Heart Transplant
- Lung Transplant
- Autoimmune Diseases
- Rheumatoid Arthritis
- Lupus Nephritis
- Ulcerative Colitis
- Psoriasis
- Dermatological Conditions
- Atopic Dermatitis
- Dry Eye Disease
- Organ Transplant
- By End-user (Value)
- Hospitals & Transplant Centers
- Specialty Clinics
- Dermatology Clinics
- Ambulatory Surgery Centers
- By Geography (Value)
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- India
- Japan
- South Korea
- Australia
- Rest of Asia-Pacific
- South America
- Brazil
- Argentina
- Rest of South America
- Middle East and Africa
- GCC
- South Africa
- Rest of Middle East and Africa
- North America
Geography Analysis
North America accounted for 39.74% of tacrolimus market size in 2025. Established transplant infrastructure, comprehensive insurance coverage, and strict bioequivalence standards favor suppliers with strong quality systems. The FDA's February 2025 downgrade of Accord's generic from AB to BX underscored the reputational stakes tied to manufacturing rigor.
Asia-Pacific is the fastest-growing region at 9.21% CAGR. China's NMPA shortened review cycles for complex generics, enabling Biocon's January 2025 approval of three strengths in one filing. Japan emphasizes local production and post-marketing surveillance, supporting domestic suppliers, whereas India leverages cost-efficient fermenters to feed global demand.
Europe grows steadily under universal healthcare and harmonized EMA pathways. Germany, the United Kingdom, and France dominate volumes, while Eastern European markets expand as transplant programs mature. South America and Middle East & Africa progress more slowly because reimbursement gaps and limited donor networks constrain procedure counts, yet Brazil's public-private partnerships hint at faster adoption ahead.
- Astellas Pharma
- Novartis
- Dr. Reddy's Laboratories Ltd.
- Sun Pharmaceuticals Industries
- Lupin
- Cipla
- Biocon
- Teva Pharmaceutical Industries
- Sandoz Group AG
- Viatris
- Accord Healthcare Ltd.
- Aurobindo Pharma Ltd.
- Glenmark Pharmaceuticals
- Zydus Lifesciences Ltd.
- Strides Pharma Science Ltd.
- Apotex
- Amneal Pharmaceuticals
- Panacea Biotec Ltd.
- Asahi Kasei
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Surging post-transplant survival rates boosting long-term immunosuppressant use
- 4.2.2 Shift from cyclosporine to tacrolimus in solid-organ transplants
- 4.2.3 Regulatory approvals for extended-release formulations
- 4.2.4 Rising autoimmune disease burden in Asia-Pacific & Europe (mainstream)
- 4.2.5 Innovative drug-delivery platforms (nano-eye-drops, biodegradable implants) (under-radar)
- 4.2.6 Precision-dosing software integrated into therapeutic drug-monitoring (TDM) systems (under-radar)
- 4.3 Market Restraints
- 4.3.1 Narrow therapeutic index necessitating costly TDM
- 4.3.2 Patent-protected LP-10/veloxis ER forms delaying price erosion
- 4.3.3 High nephro- & neuro-toxicity profile versus next-gen agents
- 4.3.4 Supply-chain vulnerability due to single-strain fermentation inputs (under-radar)
- 4.4 Value / Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Suppliers
- 4.7.3 Bargaining Power of Buyers
- 4.7.4 Threat of Substitutes
- 4.7.5 Competitive Rivalry
5 Market Size & Growth Forecasts
- 5.1 By Formulation (Value)
- 5.1.1 Extended Release
- 5.1.2 Topical Ointment
- 5.1.3 Intravenous
- 5.1.4 Oral
- 5.1.5 Others
- 5.2 By Application (Value)
- 5.2.1 Organ Transplant
- 5.2.1.1 Kidney Transplant
- 5.2.1.2 Liver Transplant
- 5.2.1.3 Heart Transplant
- 5.2.1.4 Lung Transplant
- 5.2.2 Autoimmune Diseases
- 5.2.2.1 Rheumatoid Arthritis
- 5.2.2.2 Lupus Nephritis
- 5.2.2.3 Ulcerative Colitis
- 5.2.2.4 Psoriasis
- 5.2.3 Dermatological Conditions
- 5.2.3.1 Atopic Dermatitis
- 5.2.3.2 Dry Eye Disease
- 5.2.1 Organ Transplant
- 5.3 By End-user (Value)
- 5.3.1 Hospitals & Transplant Centers
- 5.3.2 Specialty Clinics
- 5.3.3 Dermatology Clinics
- 5.3.4 Ambulatory Surgery Centers
- 5.4 By Geography (Value)
- 5.4.1 North America
- 5.4.1.1 United States
- 5.4.1.2 Canada
- 5.4.1.3 Mexico
- 5.4.2 Europe
- 5.4.2.1 Germany
- 5.4.2.2 United Kingdom
- 5.4.2.3 France
- 5.4.2.4 Italy
- 5.4.2.5 Spain
- 5.4.2.6 Rest of Europe
- 5.4.3 Asia-Pacific
- 5.4.3.1 China
- 5.4.3.2 India
- 5.4.3.3 Japan
- 5.4.3.4 South Korea
- 5.4.3.5 Australia
- 5.4.3.6 Rest of Asia-Pacific
- 5.4.4 South America
- 5.4.4.1 Brazil
- 5.4.4.2 Argentina
- 5.4.4.3 Rest of South America
- 5.4.5 Middle East and Africa
- 5.4.5.1 GCC
- 5.4.5.2 South Africa
- 5.4.5.3 Rest of Middle East and Africa
- 5.4.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Market Share Analysis
- 6.3 Company Profiles {(includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products & Services, Recent Developments)}
- 6.3.1 Astellas Pharma Inc.
- 6.3.2 Novartis AG
- 6.3.3 Dr. Reddy's Laboratories Ltd.
- 6.3.4 Sun Pharmaceutical Industries Ltd.
- 6.3.5 Lupin Limited
- 6.3.6 Cipla Ltd.
- 6.3.7 Biocon Limited
- 6.3.8 Teva Pharmaceutical Industries Ltd.
- 6.3.9 Sandoz Group AG
- 6.3.10 Viatris Inc.
- 6.3.11 Accord Healthcare Ltd.
- 6.3.12 Aurobindo Pharma Ltd.
- 6.3.13 Glenmark Pharmaceuticals Ltd.
- 6.3.14 Zydus Lifesciences Ltd.
- 6.3.15 Strides Pharma Science Ltd.
- 6.3.16 Apotex Inc.
- 6.3.17 Amneal Pharmaceuticals Inc.
- 6.3.18 Panacea Biotec Ltd.
- 6.3.19 Asahi Kasei
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-need Assessment

