PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2116866

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2116866
Global Marine Battery - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
According to Mordor Intelligence, the marine battery market size is expected to grow from USD 0.90 billion in 2025 to USD 0.97 billion in 2026 and is forecast to reach USD 1.45 billion by 2031 at 8.29% CAGR over 2026-2031.
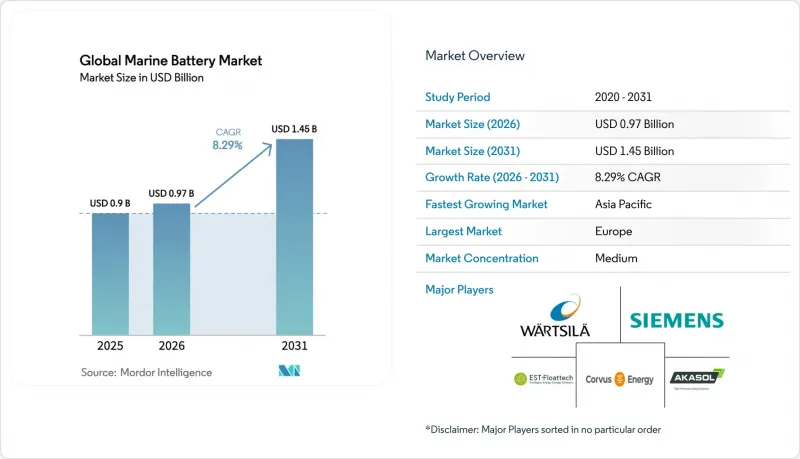
This report is Segmented by Battery Type (Lithium-Ion, Lead-Acid, and More), Propulsion Type (Hybrid Electric, Fully Electric, and More), Ship Type (Commercial and Defense), Function (Deep-Cycle, Dual-Purpose, and More), Capacity Range, and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global Marine Battery Market Trends and Insights
IMO 2020 & EU Fit-for-55 Emission Mandates Accelerating Electrification
Global and regional climate policies have aligned, making marine batteries an essential compliance tool. From 2025, FuelEU Maritime forces ships at berth to connect to shore power or use zero-emission technologies, and the IMO sets a 20% greenhouse-gas reduction target by 2030 . Operators, therefore, see battery packs as a direct route to avoid escalating carbon penalties, protect port access, and unlock lower running costs over the vessel's life.
Rapid Cost Decline of LFP/LTO Chemistries Improves TCO for Short-Sea Vessels
Cell prices for lithium iron phosphate and lithium titanate oxide continue to fall despite metal volatility, with a 40-50% drop expected by 2030. Real-world ferry data shows electric boats run for EUR 600-800 per year versus EUR 3,000-4,000 for similar diesel craft, cutting operating costs by up to 80%. The long cycle life, inherent safety, and lower maintenance of LFP-based packs deliver compelling economics on routes below 100 nautical miles.
Scarce Shipyard Capacity for Retrofits Causing Installation Bottlenecks
Yards that handle offshore wind and LNG carrier orders are close to capacity, pushing day rates up to USD 350,000 for specialized vessels and lengthening booking windows. Ferry operators now face multi-year waits for battery conversions, which defers near-term demand for the marine battery market .
Other drivers and restraints analyzed in the detailed report include:
- European Green-Port Incentives for Zero-Emission Berthing
- Expansion of Inland-Waterway Logistics Corridors in China & U.S. Pushes Battery Barges
- Thermal-Runaway Safety Concerns for Large Battery Rooms
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Lithium-ion chemistry held 65.62% revenue share in 2025 and remains the baseline for ferry and short-sea electrification. The marine battery market size for lithium-ion systems is projected to expand at high single-digit rates through 2031 as pack prices decline and cycle life improves. Solid-state variants, however, present a 9.14% CAGR opportunity by delivering up to triple energy density and an inherently safer solid electrolyte. Demonstrator modules charging to 80% in under 15 minutes are now entering pilot ferries, signaling an inflection point for the marine battery market.
Greater tolerance to temperature swings and elimination of liquid electrolytes reduce the need for bulky cooling gear in tight engine rooms. Several large shipyards expect production-scale solid-state packs to reach USD 100 per kWh around 2029, which should narrow the upfront premium. Lead-acid systems persist in backup roles where cost sensitivity outweighs weight penalties, while nickel-cadmium remains limited to niche defense programs. Fuel-cell hybrids, although promising for trans-ocean routes, continue to trail batteries in capital efficiency for sub-1,000 nautical-mile operations.
Hybrid-electric configurations captured 63.72% marine battery market share in 2025 because they cut fuel burn by up to 25% while retaining diesel range. Fleet data shows crew familiarization, class-approval processes, and port-charging windows are simpler when combustion engines remain on board. Still, fully electric newbuilds post a 10.39% CAGR thanks to rapidly expanding shore infrastructure and the falling cost of high-capacity packs. The marine battery market, therefore, follows a two-speed path where hybrids dominate retrofits and fully electric designs lead newbuilds on fixed ferry routes.
Energy-management software now orchestrates battery, generator, and hotel loads in real time, improving asset utilization and reducing maintenance. Conversion projects in Northern Europe demonstrate that once ports install megawatt-scale chargers, owners often plan to switch from hybrid to full electric within the first dry-dock cycle. Modular DC-hub architecture further simplifies the transition by allowing extra racks to be slotted in without major rewiring.
Complete Report Scope:
- By Battery Type
- Lithium-ion
- LFP
- NMC/NCA
- LTO
- Lead-acid
- Nickel-cadmium
- Fuel Cell (PEM, SOFC)
- Solid-state
- Lithium-ion
- By Propulsion Type
- Hybrid Electric
- Fully Electric
- Auxiliary / Hotel Loads
- By Ship Type
- Commercial
- Ferries & RoPax
- Cargo & Container
- Offshore Support & Wind SOV
- Inland Waterway & Barges
- Passenger & Leisure Craft
- Defense
- Naval Surface Combatants
- Submarines & UUVs
- Commercial
- By Function
- Starting
- Deep-cycle
- Dual-purpose
- By Capacity Range
- Less than 1 MWh
- 1 - 5 MWh
- Greater than 5 MWh
- By Geography
- North America
- United States
- Canada
- Rest of North America
- South America
- Brazil
- Chile
- Rest of South America
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- South Korea
- India
- Australia
- Rest of Asia-Pacific
- Middle East and Africa
- United Arab Emirates
- Saudi Arabia
- Israel
- South Africa
- Rest of Middle East and Africa
- North America
Geography Analysis
Europe commanded 42.20% revenue share in 2025 owing to legally binding greenhouse-gas caps and generous port subsidies. The marine battery market in the bloc benefits from a dense short-sea network where ferries and feeders call at ports several times a day, making shore-charging practical. Northern Europe tops early adoption, yet Mediterranean yards are now inserting battery rooms into cruise-ferry newbuilds to meet the 2030 berth-emission rule.
Asia-Pacific posts the fastest 11.36% CAGR for the marine battery market, led by China's zero-carbon Yangtze program and the launch of a 50 MWh electric container ship. South Korean and Japanese yards contribute design know-how and domestic lithium supply. ASEAN countries follow, with Malaysia's planned Johor plant targeting regional demand for fishing boats, tugs, and inter-island ferries.
North America shows steady growth on the back of defense contracts and state ferry upgrades in Washington, Alaska, and New York. Inland waterways add further momentum, as barge operators trial battery push-boats on fixed grain and coal routes. Latin America and Africa remain small today but possess lithium resources and new port modernization plans that could lift long-term uptake. Middle Eastern offshore operators also explore battery-hybrid service craft to cut emissions near rigs.
- Corvus Energy
- Siemens AG
- EST-Floattech B.V
- Wartsila Corporation
- Akasol AG
- Saft Batteries
- EnerSys
- Tesvolt Ocean GmbH
- AYK Energy
- Leclanche SA
- Shift Clean Energy (PBES)
- Echandia Marine
- CATL Marine
- Kokam (SolarEdge)
- Rolls-Royce Power Systems (MTU)
- ABB Ltd
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 IMO 2020 & EU Fit-for-55 Emission Mandates Accelerating Electrification
- 4.2.2 Rapid Cost Decline of LFP/LTO Chemistries Improves TCO for Short-Sea Vessels
- 4.2.3 European Green-Port Incentives for Zero-Emission Berthing
- 4.2.4 Expansion of Inland-Waterway Logistics Corridors in China & U.S. Pushes Battery Barges
- 4.2.5 Defense Navies Investing in Silent-Running Battery Submarines
- 4.2.6 Offshore-Wind Service Vessels Adopting Battery-Hybrid Propulsion for Dynamic Positioning
- 4.3 Market Restraints
- 4.3.1 Scarce Shipyard Capacity for Retrofits Causing Installation Bottlenecks
- 4.3.2 Thermal-Runaway Safety Concerns for Large Battery Rooms
- 4.3.3 High Capex of Marine-Certified Battery-Management Systems
- 4.3.4 Lithium Supply-Chain Exposure to South-American Geopolitical Risks
- 4.4 Value / Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Bargaining Power of Suppliers
- 4.7.4 Threat of Substitute Products
- 4.7.5 Intensity of Competitive Rivalry
5 Market Size & Growth Forecasts (Value, USD)
- 5.1 By Battery Type
- 5.1.1 Lithium-ion
- 5.1.1.1 LFP
- 5.1.1.2 NMC/NCA
- 5.1.1.3 LTO
- 5.1.2 Lead-acid
- 5.1.3 Nickel-cadmium
- 5.1.4 Fuel Cell (PEM, SOFC)
- 5.1.5 Solid-state
- 5.1.1 Lithium-ion
- 5.2 By Propulsion Type
- 5.2.1 Hybrid Electric
- 5.2.2 Fully Electric
- 5.2.3 Auxiliary / Hotel Loads
- 5.3 By Ship Type
- 5.3.1 Commercial
- 5.3.1.1 Ferries & RoPax
- 5.3.1.2 Cargo & Container
- 5.3.1.3 Offshore Support & Wind SOV
- 5.3.1.4 Inland Waterway & Barges
- 5.3.1.5 Passenger & Leisure Craft
- 5.3.2 Defense
- 5.3.2.1 Naval Surface Combatants
- 5.3.2.2 Submarines & UUVs
- 5.3.1 Commercial
- 5.4 By Function
- 5.4.1 Starting
- 5.4.2 Deep-cycle
- 5.4.3 Dual-purpose
- 5.5 By Capacity Range
- 5.5.1 Less than 1 MWh
- 5.5.2 1 - 5 MWh
- 5.5.3 Greater than 5 MWh
- 5.6 By Geography
- 5.6.1 North America
- 5.6.1.1 United States
- 5.6.1.2 Canada
- 5.6.1.3 Rest of North America
- 5.6.2 South America
- 5.6.2.1 Brazil
- 5.6.2.2 Chile
- 5.6.2.3 Rest of South America
- 5.6.3 Europe
- 5.6.3.1 Germany
- 5.6.3.2 United Kingdom
- 5.6.3.3 France
- 5.6.3.4 Italy
- 5.6.3.5 Spain
- 5.6.3.6 Rest of Europe
- 5.6.4 Asia-Pacific
- 5.6.4.1 China
- 5.6.4.2 Japan
- 5.6.4.3 South Korea
- 5.6.4.4 India
- 5.6.4.5 Australia
- 5.6.4.6 Rest of Asia-Pacific
- 5.6.5 Middle East and Africa
- 5.6.5.1 United Arab Emirates
- 5.6.5.2 Saudi Arabia
- 5.6.5.3 Israel
- 5.6.5.4 South Africa
- 5.6.5.5 Rest of Middle East and Africa
- 5.6.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (Includes Global Level Overview, Market Level Overview, Core Segments, Financials as Available, Strategic Information, Market Rank/Share for Key Companies, Products & Services, and Recent Developments)
- 6.4.1 Corvus Energy
- 6.4.2 Siemens AG
- 6.4.3 EST-Floattech B.V
- 6.4.4 Wartsila Corporation
- 6.4.5 Akasol AG
- 6.4.6 Saft Batteries
- 6.4.7 EnerSys
- 6.4.8 Tesvolt Ocean GmbH
- 6.4.9 AYK Energy
- 6.4.10 Leclanche SA
- 6.4.11 Shift Clean Energy (PBES)
- 6.4.12 Echandia Marine
- 6.4.13 CATL Marine
- 6.4.14 Kokam (SolarEdge)
- 6.4.15 Rolls-Royce Power Systems (MTU)
- 6.4.16 ABB Ltd
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-need Assessment

