PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2117218

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2117218
Europe Postal Services - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
According to Mordor Intelligence, Europe postal services market size in 2026 is estimated at USD 184.59 billion, growing from 2025 value of USD 181.34 billion with 2031 projections showing USD 201.76 billion, growing at 1.79% CAGR over 2026-2031.
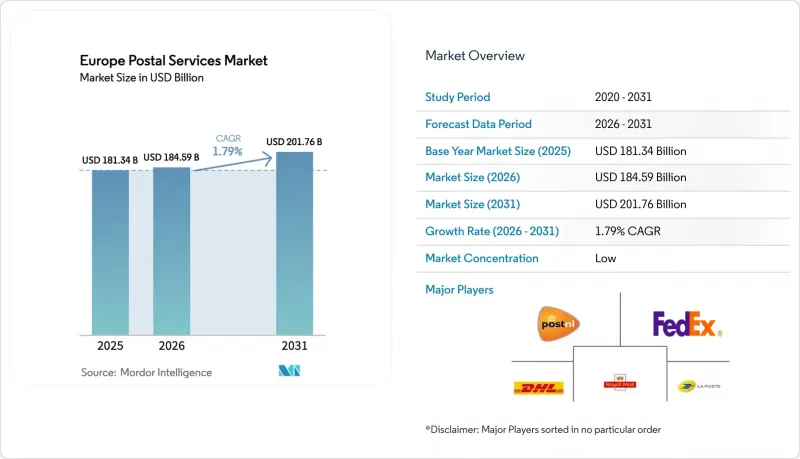
This report is Segmented by Service Type (Express Postal Service and Standard Postal Service), by Item Type (Letters and Parcels), by Destination (Domestic and International), by Country (Germany, United Kingdom, France, Italy, Spain, Netherlands, Nordics (Sweden, Denmark, Norway, Finland) and Rest of Europe (incl. Eastern Europe & Balkans)). The Market Forecasts are Provided in Terms of Value (USD).
Europe Postal Services Market Trends and Insights
E-commerce Boom Driving Parcel Volumes in Germany & the UK
Parcel volumes in Germany rose 9 % year-on-year during Q2 2024 even as consumer spending moderated. The United Kingdom echoes this pattern, with e-commerce holding 26 % of retail in 2024 and set to reach 31 % by 2028. This demand imbalance between parcels and letters is producing asymmetric network utilisation that nudges operators to repurpose letter routes for parcel pickups. A fresh inference is that suburban depots originally designed for mail sorting are quietly morphing into parcel micro-fulfilment hubs, unlocking hidden asset productivity.
EU Carbon Regulations Accelerating Fleet Electrification Investments
Stricter emission caps have accelerated electric-vehicle roll-outs, with UPS deploying more than 100 new EVs in Paris and planning 600 across Europe by end-2024 . Bpost doubled its electric van fleet, while PostNL logged 82 % emission-free delivery kilometres in 2023. The underlying inference is that early movers can price carbon-neutral delivery at a modest premium, creating a two-tier service catalogue that hedges against regulatory costs.
Declining Traditional Letter Volumes in Nordic Region
PostNord notes that 76 % of Nordic consumers now purchase cross-border online, diverting attention from domestic mail services. Letter declines accelerate cost-to-serve, forcing operators to trim headcount; Posti's recent layoffs confirm this restructuring path. The inference is that the Nordic region may pioneer hybrid public-private funding models to keep universal service afloat.
Other drivers and restraints analyzed in the detailed report include:
- Cross-Border Single Market Initiatives Simplifying Customs for SMEs
- Ageing Population Sustaining Letter-Mail Demand for Government Correspondence
- High Labor Costs & Unionization in Western Europe
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Express services hold a Europe Postal Services market size that is forecast to expand at 6.96 % CAGR from 2026-2031, significantly faster than standard services, which still command 52.35 % market share in 2025. The widening spread highlights how premium time-definite products monetise consumer willingness to pay for speed. A current inference is that network design is pivoting toward later collection cut-offs and earlier morning delivery waves, squeezing utilisation out of existing fleets.
Standard services, although lower growth, remain indispensable for regulatory service obligations and nationwide coverage. Germany's revised Postal Act extends permissible delivery time to three business days for 95 % of letters starting 2025, freeing operators to batch deliveries. This regulatory slack implies that standard services will increasingly serve as the cost-optimised backbone, while express layers generate surplus cash.
Complete Report Scope:
- By Service Type
- Express Postal Service
- Standard Postal Service
- By Item Type
- Letters
- Parcels
- By Destination
- Domestic
- International
- By Country
- Germany
- United Kingdom
- France
- Italy
- Spain
- Netherlands
- Nordics (Sweden, Denmark, Norway, Finland)
- Rest of Europe (incl. Eastern Europe & Balkans)
List of Companies Covered in this Report:
- Deutsche Post DHL Group
- La Poste SA (DPDgroup/GeoPost)
- Royal Mail Group plc
- United Parcel Service Inc. (UPS)
- FedEx Corp. (incl. TNT Express)
- Poste Italiane SpA
- PostNL NV
- Swiss Post AG
- Bpost SA/NV
- PostNord AB
- GLS Group
- Hermes Europe GmbH (Evri)
- Asendia Management SAS
- DPD HL LLP (Russia)
- CTT Correios de Portugal SA
- Bring (Norwegian Posten)
- Omniva (Eesti Post AS)
- Correos y Telegrafos SA
- InPost SA
- Russian Post*
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 E-commerce Boom Driving Parcel Volumes in Germany & the UK
- 4.2.2 EU Carbon Regulations Accelerating Fleet Electrification Investments
- 4.2.3 Cross-Border Single Market Initiatives Simplifying Customs for SMEs
- 4.2.4 Ageing Population Sustaining Letter-Mail Demand for Government Correspondence
- 4.2.5 Same-Day Delivery Expectations Propelling Express Service Premiums
- 4.2.6 Logistics Automation Adoption Reducing Sortation Cost per Piece
- 4.3 Market Restraints
- 4.3.1 Declining Traditional Letter Volumes in Nordic Region
- 4.3.2 High Labor Costs & Unionization in Western Europe
- 4.3.3 Urban Congestion & Access Restrictions Increasing Last-Mile Costs
- 4.3.4 Digital Substitutes (e-Billing, Messaging) Eroding Letter Revenues
- 4.4 Value / Supply-Chain Analysis
- 4.5 Regulatory & Technological Outlook
- 4.6 Porter's Five Forces
- 4.6.1 Threat of New Entrants
- 4.6.2 Bargaining Power of Buyers/Consumers
- 4.6.3 Bargaining Power of Suppliers
- 4.6.4 Threat of Substitute Products
- 4.6.5 Intensity of Competitive Rivalry
- 4.7 Impact of Geo-Political Events in the market
5 Market Size & Growth Forecasts (Value)
- 5.1 By Service Type
- 5.1.1 Express Postal Service
- 5.1.2 Standard Postal Service
- 5.2 By Item Type
- 5.2.1 Letters
- 5.2.2 Parcels
- 5.3 By Destination
- 5.3.1 Domestic
- 5.3.2 International
- 5.4 By Country
- 5.4.1 Germany
- 5.4.2 United Kingdom
- 5.4.3 France
- 5.4.4 Italy
- 5.4.5 Spain
- 5.4.6 Netherlands
- 5.4.7 Nordics (Sweden, Denmark, Norway, Finland)
- 5.4.8 Rest of Europe (incl. Eastern Europe & Balkans)
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products & Services, Recent Developments)
- 6.4.1 Deutsche Post DHL Group
- 6.4.2 La Poste SA (DPDgroup/GeoPost)
- 6.4.3 Royal Mail Group plc
- 6.4.4 United Parcel Service Inc. (UPS)
- 6.4.5 FedEx Corp. (incl. TNT Express)
- 6.4.6 Poste Italiane SpA
- 6.4.7 PostNL NV
- 6.4.8 Swiss Post AG
- 6.4.9 Bpost SA/NV
- 6.4.10 PostNord AB
- 6.4.11 GLS Group
- 6.4.12 Hermes Europe GmbH (Evri)
- 6.4.13 Asendia Management SAS
- 6.4.14 DPD HL LLP (Russia)
- 6.4.15 CTT Correios de Portugal SA
- 6.4.16 Bring (Norwegian Posten)
- 6.4.17 Omniva (Eesti Post AS)
- 6.4.18 Correos y Telegrafos SA
- 6.4.19 InPost SA
- 6.4.20 Russian Post*
7 Market Opportunities & Future Outlook

