PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2125604

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2125604
North America Postal Services - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
According to Mordor Intelligence, North America postal services market size market size in 2026 is estimated at USD 88.8 billion, growing from 2025 value of USD 87.88 billion with 2031 projections showing USD 93.56 billion, growing at 1.05% CAGR over 2026-2031.
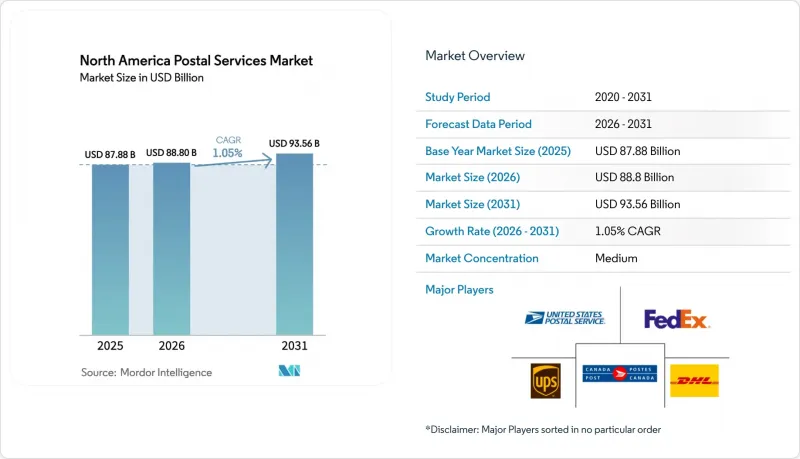
This report Segments the Industry Into by Type (Standard Postal Services and Express Postal Services), by Items (Letters and Parcels), by Destination (Domestic and International), by End-User (Business-To-Business (B2B), Business-To-Consumer (B2C) and More), by Delivery Mode (Road, Air and More) and by Country (United States, and More). The Market Forecasts are Provided in Terms of Value (USD).
North America Postal Services Market Trends and Insights
E-commerce Parcel Volume Boom Driven by Same-Day Delivery Demands
Parcel traffic reached 21.7 billion pieces in the United States during 2023 and is projected to climb toward 29 billion by 2029, adding pressure on postal operators to prioritise parcel capacity over letter routes. Operators are now favouring predictable two-to-three-day windows over ultra-fast promises because reliability has become the key buying criterion for online shoppers. USPS upgraded seasonal processing to about 60 million parcels per day for the 2024 holiday peak, reflecting a permanent shift toward parcel-centric networks.
SMB Adoption of Hybrid Mail & Fulfilment APIs in the United States
Small and midsize businesses now contribute 28.9% of total U.S. postal volume, catalysed by easy-to-integrate shipping APIs offered by USPS and private carriers. Web Tools updates released during 2024 add end-to-end tracking and harmonised customs data, enabling even micro-merchants to print compliant labels directly from e-commerce dashboards. This digital bridge is democratising enterprise-grade logistics capabilities and sustaining higher-margin traffic across the network.
First-Class Mail Volume Decline from Digital Substitution in U.S. Government Agencies
First-Class Mail fell by 50% between FY 2008 and FY 2023, eroding one of USPS's most profitable revenue streams. Government bodies that once mailed tax notices and benefits statements are now defaulting to digital delivery, deepening revenue pressure. Even with higher parcel income, USPS posted a USD 6.5 billion net loss in FY 2023, and further declines in physical correspondence threaten funding for universal-service mandates.
Other drivers and restraints analyzed in the detailed report include:
- U.S. Postal Service's Network Modernization Increasing Processing Capacity
- Canada Post's Parcel Expansion Hubs Enhancing Cross-Border Reach
- Chronic Labor Shortages & Rising Union Wage Pressures at National Posts
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Express services recorded a 3.55% CAGR for 2026-2031, surpassing overall market momentum. The benefits from premium pricing as businesses pay for predictable arrival windows. Continuous Producer Price Index gains for couriers confirm sustained demand, and major operators bolster time-definite lanes with later cut-offs and earlier clearances.
Standard services, although covering the broadest addressable base, wrestle with secular mail decline. Yet they still commanded 62.85% of the North America postal services market share in 2025 due to universal-service obligations that entrench nationwide delivery networks. USPS is recalibrating standards so 75% of First-Class Mail maintains a 1-5-day window and 14% gains faster service, aligning commitments with real-world transport flows.
Parcels held 58.05% share in 2025, generating the lion's share of revenue for the North America postal services market. Operators expanded mechanised sortation and shifted labour from letter plants to parcel lanes, enabling single-piece handling rates as low as 20 seconds per unit during peak periods. The North America postal services market size tied to parcel business is forecast to grow at 3.65% CAGR on the back of expanding e-commerce categories such as oversized home goods and temperature-controlled groceries.
Letter volumes, in contrast, continue their downtrend. Between 2008 and 2023, First-Class Mail halved, and the North America postal services market share for letters slipped accordingly. Still, legal documents, voter materials, and direct-mail marketing keep a rump demand that supports selective investments in high-speed letter sorting technology meant to safeguard remaining profitability.
Complete Report Scope:
- By Type
- Standard Postal Services
- Express Postal Services
- By Item
- Letters
- Parcels
- By Destination
- Domestic
- International
- By End-User
- Business-to-Business (B2B)
- Business-to-Consumer (B2C)
- Consumer-to-Consumer (C2C)
- By Delivery Mode
- Road
- Air
- Sea
- Rail
- By Country
- United States
- Canada
- Mexico
List of Companies Covered in this Report:
- United States Postal Service (USPS)
- Canada Post Corporation
- FedEx Corporation
- United Parcel Service Inc. (UPS)
- Deutsche Post DHL Group (DHL Express)
- Purolator Inc.
- OnTrac Logistics
- LaserShip / OnTrac Group
- Pitney Bowes Inc.
- Stamps.com (Auctane)
- Correos de Mexico (SEPOMEX)
- SCI Group
- Spee-Dee Delivery Service
- GLS-US (formerly GSO)
- RR Donnelley Logistics
- Neopost (Quadient)
- Sendle USA
- ShipBob Inc.*
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 E-commerce Parcel Volume Boom Driven by Same-Day Delivery Demands
- 4.2.2 SMB Adoption of Hybrid Mail & Fulfilment APIs in the United States
- 4.2.3 U.S. Postal Service's Network Modernization Increasing Processing Capacity
- 4.2.4 Canada Post's Parcel Expansion Hubs Enhancing Cross-Border Reach
- 4.2.5 Mexico's Logistics-Park Near-shoring Surge Raising Mailroom Outsourcing
- 4.2.6 State-Level Sustainability Mandates Accelerating Fleet Electrification
- 4.3 Market Restraints
- 4.3.1 First-Class Mail Volume Decline from Digital Substitution in U.S. Gov. Agencies
- 4.3.2 Chronic Labor Shortages & Rising Union Wage Pressures at National Posts
- 4.3.3 Airport & Border Capacity Bottlenecks Slowing Cross-Border Parcel Flows
- 4.3.4 Mexican Rural Addressing Gaps Increasing Last-Mile Delivery Costs
- 4.4 Value / Supply-Chain Analysis
- 4.5 Regulatory Outlook
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces
- 4.7.1 Competitive Rivalry
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Bargaining Power of Suppliers
- 4.7.4 Threat of Substitutes
- 4.7.5 Threat of New Entrants
5 Market Size & Growth Forecasts (Value)
- 5.1 By Type
- 5.1.1 Standard Postal Services
- 5.1.2 Express Postal Services
- 5.2 By Item
- 5.2.1 Letters
- 5.2.2 Parcels
- 5.3 By Destination
- 5.3.1 Domestic
- 5.3.2 International
- 5.4 By End-User
- 5.4.1 Business-to-Business (B2B)
- 5.4.2 Business-to-Consumer (B2C)
- 5.4.3 Consumer-to-Consumer (C2C)
- 5.5 By Delivery Mode
- 5.5.1 Road
- 5.5.2 Air
- 5.5.3 Sea
- 5.5.4 Rail
- 5.6 By Country
- 5.6.1 United States
- 5.6.2 Canada
- 5.6.3 Mexico
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles {(includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products & Services, and Recent Developments)}
- 6.4.1 United States Postal Service (USPS)
- 6.4.2 Canada Post Corporation
- 6.4.3 FedEx Corporation
- 6.4.4 United Parcel Service Inc. (UPS)
- 6.4.5 Deutsche Post DHL Group (DHL Express)
- 6.4.6 Purolator Inc.
- 6.4.7 OnTrac Logistics
- 6.4.8 LaserShip / OnTrac Group
- 6.4.9 Pitney Bowes Inc.
- 6.4.10 Stamps.com (Auctane)
- 6.4.11 Correos de Mexico (SEPOMEX)
- 6.4.12 SCI Group
- 6.4.13 Spee-Dee Delivery Service
- 6.4.14 GLS-US (formerly GSO)
- 6.4.15 RR Donnelley Logistics
- 6.4.16 Neopost (Quadient)
- 6.4.17 Sendle USA
- 6.4.18 ShipBob Inc.*
7 Market Opportunities & Future Outlook

