PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2117246

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2117246
Europe Inland Water Freight Transport - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
According to Mordor Intelligence, the Europe inland water freight transport market size was valued at USD 44.10 billion in 2025 and estimated to grow from USD 45.73 billion in 2026 to reach USD 54.82 billion by 2031, at a CAGR of 3.69% during the forecast period (2026-2031).
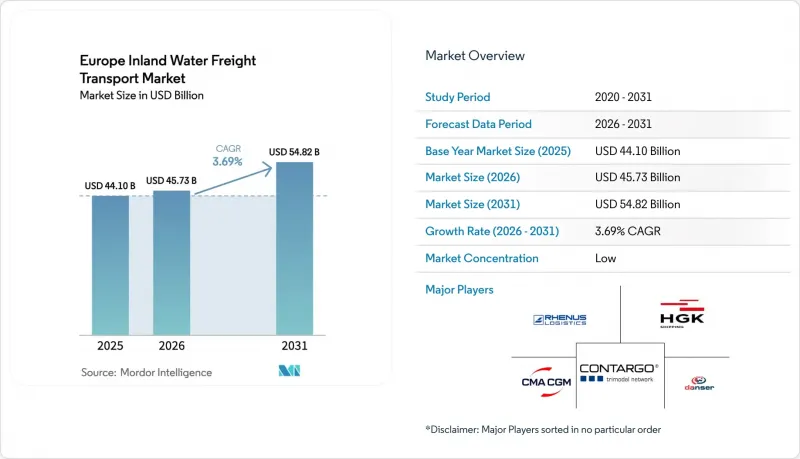
This report Segments the Industry Into by Type of Transportation(Liquid Bulk Transportation, Dry Bulk Transportation, Containerized Freight and More), by End User Industry (Agriculture & Food, Metallurgy & Mining, Petroleum and Chemicals, Construction and More), by Geography (Netherlands, Germany, Belgium, France, and More). The Market Forecasts are Provided in Terms of Value (USD).
Europe Inland Water Freight Transport Market Trends and Insights
EU Green Deal Driving Modal Shift to Waterways
The European Green Deal aims for a 90 % reduction in transport-related greenhouse-gas emissions by 2050, and its Sustainable and Smart Mobility Strategy calls for inland waterway freight volumes to climb 25 % by 2030 and 50 % by 2050. As ETS fees scale up for shipping emissions, the gap between the carbon cost of barges and trucks widens, strengthening the modal-shift argument in national freight strategies. Operators are already reporting stronger demand inquiries for container slots on the Rhine-Dutch delta, implying that the targets are influencing day-to-day routing decisions well before the 2030 milestone. An immediate inference is that modal-shift subsidies may taper sooner than expected because cost competitiveness alone progressively favours waterways.
Rhine-Danube Corridor Capacity Upgrades Accelerating Barge Demand
European Union investments to eliminate bottlenecks along the Rhine-Danube corridor include deeper draught sections, taller bridges, and modernised locks in Slovakia, Hungary, and Romania. Completion of these works raises baseline payloads during variable river conditions, thereby reducing the "empty kilometres" problem that once stifled profitability. Private operators such as Contargo have responded by enlarging their dedicated barge fleets and ordering hybrid-propulsion vessels to secure early mover advantages. From these patterns one can infer that barge charter rates along the Danube will trend upward as shippers compete for newly reliable capacity.
Chronic Low-Water Events on Rhine & Danube Disrupting Load Factors
Climate-driven low-water spells forced barges on the Rhine to sail at partial loads for several consecutive weeks in 2024, cutting German industrial output by roughly 1 % during the affected month. Similarly, parts of the Danube fell to 1.5 m depth, compelling convoys to idle or re-route. Operators mitigate with shallow-draught hull designs and dynamic cargo-allocation software, but residual uncertainty dents service reliability. From this evidence one can infer that risk-adjusted freight pricing will favour multi-hull vessels capable of continuing service at reduced draughts, even if capital costs are marginally higher.
Other drivers and restraints analyzed in the detailed report include:
- Tightening CO2 / Pollutant Norms Favouring Low-Emission Barges
- Digitisation via RIS & DINA Improving Supply-Chain Visibility
- Ageing Barge Fleet Facing Capex-Intensive Retrofit Mandates
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Dry bulk commands the largest Europe Inland Water Freight Transport market share at 53.62 % in 2025, carrying commodities such as coal, steel inputs, and construction aggregates on high-capacity Rhine barges equivalent to 220 trucks. The segment benefits from low handling complexity, enabling steady utilisation even during economic lulls. A notable inference is that anticipated coal-phase-out policies will gradually shift barge tonne-kilometres toward biomass and recycled-metal flows, altering hold-cleaning protocols and port terminal equipment.
Containerised freight, while currently smaller, is forecast to grow at a 6.98 % CAGR from 2026-2031, significantly outpacing overall market expansion. Operators such as Contargo already field 13,498 TEU of barge capacity and plan to deploy electric-propulsion units in 2024. Liquid bulk retains stable volumes thanks to dedicated chemical park jetties, whereas roll-on/roll-off craft gain traction in city-distribution trials. An arising inference is that port planners will allocate more quay space to barge-mounted gantries capable of side-loading containers in tidal or variable river conditions.
Complete Report Scope:
- By Type of Transportation
- Liquid Bulk Transportation
- Dry Bulk Transportation
- Containerised Freight
- Dry
- Reefer
- Roll-On / Roll-Off Cargo
- By End-Use Industry
- Agriculture & Food
- Metallurgy & Mining
- Petroleum & Chemicals
- Construction
- Energy (Biomass & Coal)
- Consumer Goods & Retail
- Others
- By Geography
- Netherlands
- Germany
- Belgium
- France
- Romania
- Bulgaria
- Rest of Europe
List of Companies Covered in this Report:
- Rhenus Group
- HGK Shipping GmbH
- Contargo GmbH & Co. KG
- Danser Group
- CMA CGM Inland Services
- Imperial Logistics International
- Sogestran Group / CFT
- Van den Bosch Transporten BV
- Stolt-Nielsen Inland Tanker Service
- Deutsche Binnenreederei AG
- Blue Line Logistics
- VTG AG (Tanktainer / Barges)
- DP World Inland Europe
- Swire Bulk Europe
- PortLiner
- AWT Group
- Cobelfret Barge NV
- De Poli Tankers Inland
- Planco Shipping BV
- Danubia Krems GmbH*
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 EU Green Deal Driving Modal Shift to Waterways
- 4.2.2 Rhine-Danube Corridor Capacity Upgrades Accelerating Barge Demand
- 4.2.3 Tightening CO2 / Pollutant Norms Favouring Low-Emission Barges
- 4.2.4 Digitisation via RIS & DINA Improving Supply-Chain Visibility
- 4.2.5 Rise of Urban Logistics Pilots in Paris, Amsterdam & Antwerp
- 4.2.6 Fuel-Cost Differential vs. Road Transport Widening After ETS-II
- 4.3 Market Restraints
- 4.3.1 Chronic Low-Water Events on Rhine & Danube Disrupting Load Factors
- 4.3.2 Ageing Barge Fleet Facing Capex-Intensive Retrofit Mandates
- 4.3.3 Port & Lock Bottlenecks Limiting Vessel Size on Secondary Canals
- 4.3.4 Competitive Pressure from Electrified Rail Freight in Central Europe
- 4.4 Value / Supply-Chain Analysis
- 4.5 Regulatory Outlook
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Competitive Rivalry
- 4.8 Insights into Transshipment Trade
- 4.9 Insights into Containerised vs. Non-Containerised Shipments
- 4.10 Freight Rates & Maritime Transport Costs
- 4.11 Insights into Intermodal / Container Utilisation
- 4.12 Demand-Supply Analysis
- 4.13 Impact of Geo-Political events on the Market
5 Market Size & Growth Forecasts (Value, USD)
- 5.1 By Type of Transportation
- 5.1.1 Liquid Bulk Transportation
- 5.1.2 Dry Bulk Transportation
- 5.1.3 Containerised Freight
- 5.1.3.1 Dry
- 5.1.3.2 Reefer
- 5.1.4 Roll-On / Roll-Off Cargo
- 5.2 By End-Use Industry
- 5.2.1 Agriculture & Food
- 5.2.2 Metallurgy & Mining
- 5.2.3 Petroleum & Chemicals
- 5.2.4 Construction
- 5.2.5 Energy (Biomass & Coal)
- 5.2.6 Consumer Goods & Retail
- 5.2.7 Others
- 5.3 By Geography
- 5.3.1 Netherlands
- 5.3.2 Germany
- 5.3.3 Belgium
- 5.3.4 France
- 5.3.5 Romania
- 5.3.6 Bulgaria
- 5.3.7 Rest of Europe
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products & Services, and Recent Developments)
- 6.4.1 Rhenus Group
- 6.4.2 HGK Shipping GmbH
- 6.4.3 Contargo GmbH & Co. KG
- 6.4.4 Danser Group
- 6.4.5 CMA CGM Inland Services
- 6.4.6 Imperial Logistics International
- 6.4.7 Sogestran Group / CFT
- 6.4.8 Van den Bosch Transporten BV
- 6.4.9 Stolt-Nielsen Inland Tanker Service
- 6.4.10 Deutsche Binnenreederei AG
- 6.4.11 Blue Line Logistics
- 6.4.12 VTG AG (Tanktainer / Barges)
- 6.4.13 DP World Inland Europe
- 6.4.14 Swire Bulk Europe
- 6.4.15 PortLiner
- 6.4.16 AWT Group
- 6.4.17 Cobelfret Barge NV
- 6.4.18 De Poli Tankers Inland
- 6.4.19 Planco Shipping BV
- 6.4.20 Danubia Krems GmbH*
7 Market Opportunities & Future Outlook

