PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2117300

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2117300
Vitamin D Testing - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
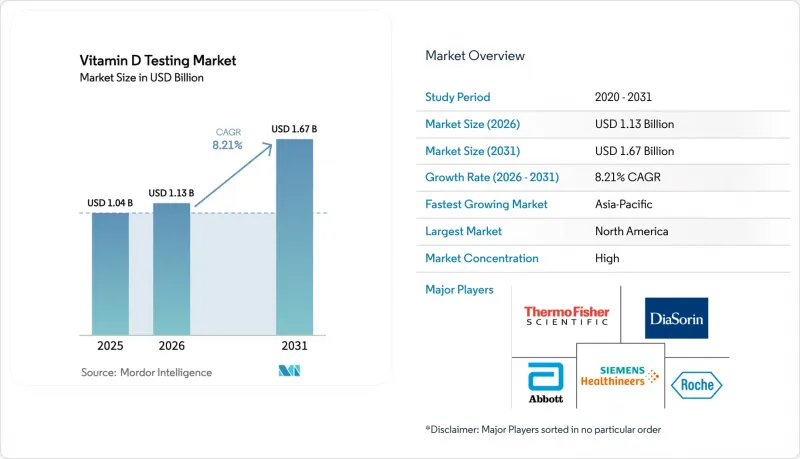
According to Mordor Intelligence, the vitamin d testing market size is expected to grow from USD 1.04 billion in 2025 to USD 1.13 billion in 2026 and is forecast to reach USD 1.67 billion by 2031 at 8.21% CAGR over 2026-2031.
This report is Segmented by Product Type (Reagent & Kits, Instruments, Services), Technology (LC-MS/MS, Chemiluminescence Immunoassay, ELISA, Radio-Immunoassay, Others), End User (Diagnostic Laboratories, Hospitals & Clinics, and More), Sample Type (Serum/Plasma, Whole Blood, and More), and Geography (North America, Europe, and More). The Market Forecasts are Provided in Terms of Value (USD).
Global Vitamin D Testing Market Trends and Insights
Rising Burden of Vitamin-D Deficiency Diagnoses
Roughly 1 billion people live with inadequate vitamin D levels, with prevalence soaring to 82.1% among Black Americans and 69.2% in Latino communities. Clinical guidelines published by the Endocrine Society in 2024 created precise testing criteria for high-risk populations, which paradoxically expanded targeted demand even while discouraging universal screening. Providers increasingly embed vitamin D assessment in chronic-disease management programs for diabetes, cardiovascular disease, and osteoporosis, sustaining growth of the Vitamin D testing market. The confluence of aging populations, limited sun exposure in urban lifestyles, and malabsorption disorders further reinforces systematic screening in many regions. Government surveillance linked to food-fortification programs adds another steady testing stream, translating population-health priorities into laboratory demand.
Shift to Preventive Healthcare & Routine Screening
Value-based reimbursement models encourage early detection, making vitamin D measurement a routine metric in preventive health check-ups covered by Medicare Advantage plans and a growing list of private insurers. Direct-to-consumer laboratory spending is poised to surpass USD 9 billion by 2033, giving consumers unprecedented power to order tests without physician mediation. Employers embed vitamin D tracking in corporate wellness dashboards, encouraging regular employee monitoring that generates predictable sample volumes. Senior-care programs integrate deficiency checks into fall-prevention initiatives, enhancing adherence to supplementation regimens. Collectively these behavioral and policy shifts underpin sustained expansion of the Vitamin D testing market.
Pricing Pressure from Bundled Wellness Panels
Volume-based contracting has encouraged insurers to reimburse comprehensive metabolic screens that include vitamin D for a single all-in price, compressing margins on individual assays. Consolidated national labs can leverage scale, but regional independents often absorb lower reimbursement, forcing them to renegotiate supplier contracts. Consumer-direct platforms mirror this pressure by marketing multi-analyte panels at discount prices to gain share, intensifying price competition in the Vitamin D testing market. Larger players counteract by automating workflows and cross-selling allergy or hormone panels to maintain profitability.
Other drivers and restraints analyzed in the detailed report include:
- CLIA Automation Lowering Per-Test Cost
- Emerging Reimbursement Codes in Europe & U.S.
- Regulatory Scrutiny over Direct-to-Consumer Claims
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
The services arm of the Vitamin D testing market expanded at an 8.87% CAGR toward 2031, propelled by hospital outsourcing and reference-lab consolidation. Reagents and kits still delivered 45.05% Vitamin D testing market share in 2025, yet their revenue margins tightened because automated systems consume fewer consumables per assay. Instruments represent the smallest revenue slice, but every analyzer placement establishes a long-tail reagent annuity that underpins supplier profitability. Laboratories unable to fund automation increasingly subcontract specialized vitamin D panels to service providers, reinforcing service-segment momentum. Acquisitions like Quest Diagnostics' USD 1 billion LifeLabs deal highlight the race for network scale that amplifies purchasing leverage and geographic reach.
Reagent manufacturers respond by innovating high-sensitivity chemistries compatible with both CLIA and emerging LC-MS/MS platforms, safeguarding demand even as per-test consumption falls. Digital integration services that link analyzers to laboratory information systems deliver incremental revenue while differentiating suppliers. Meanwhile, point-of-care service models flourish in primary-care clinics where rapid readouts inform supplementation decisions during a single visit, extending the Vitamin D testing market beyond central laboratories.
Complete Report Scope:
- By Product Type (Value)
- Reagent & Kits
- Instruments
- Services
- By Technology (Value)
- LC-MS/MS
- Chemiluminescence Immunoassay (CLIA)
- ELISA
- Radio-Immunoassay (RIA)
- Others
- By End User (Value)
- Diagnostic Laboratories
- Hospitals & Clinics
- Home-care & Remote Testing
- Others
- By Sample Type (Value)
- Serum / Plasma
- Whole Blood
- Dried Blood Spot
- Others
- By Geography (Value)
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- India
- Japan
- South Korea
- Australia
- Rest of Asia-Pacific
- South America
- Brazil
- Argentina
- Rest of South America
- Middle East and Africa
- GCC
- South Africa
- Rest of Middle East and Africa
- North America
Geography Analysis
North America generated 41.80% of 2025 revenue thanks to broad insurance coverage and advanced automation infrastructure. Asia-Pacific, however, is the growth engine with a 10.74% CAGR anchored by urbanization, rising middle-class health awareness, and private-sector diagnostic investment. Organized lab networks in India penetrate tier-3 towns, while Chinese demand swells alongside nutraceutical consumption trends. Europe continues steady expansion through fortification-driven surveillance programs and aging demographics, but reimbursement austerity limits upside. Middle East and Africa markets show early promise as governments modernize healthcare and grapple with surprisingly high deficiency in sun-rich climates.
- Abbott Laboratories
- Roche
- Siemens Healthineers
- Danaher
- Thermo Fisher Scientific
- DiaSorin
- Quest Diagnostics
- bioMerieux
- Bio-Rad Laboratories
- Ortho Clinical Diagnostics Holdings plc
- Grifols
- Randox Laboratories
- Mindray
- Tosoh
- Sysmex
- Eurofins
- ARUP Laboratories
- Cerba HealthCare SAS
- Unilabs AB
- Biomerica Inc.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising burden of vitamin-D deficiency diagnoses (mainstream)
- 4.2.2 Shift to preventive healthcare & routine screening (mainstream)
- 4.2.3 CLIA automation lowering per-test cost (mainstream)
- 4.2.4 Emerging reimbursement codes in Europe & U.S. (mainstream)
- 4.2.5 AI-enabled at-home micro-sample kits (under-the-radar)
- 4.2.6 National fortification policies prompting surveillance testing (under-the-radar)
- 4.3 Market Restraints
- 4.3.1 Pricing pressure from bundled wellness panels (mainstream)
- 4.3.2 Variability between assay methods (mainstream)
- 4.3.3 Dried-blood-spot sample stability concerns (under-the-radar)
- 4.3.4 Regulatory scrutiny over direct-to-consumer claims (under-the-radar)
- 4.4 Value / Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Suppliers
- 4.7.3 Bargaining Power of Buyers
- 4.7.4 Threat of Substitutes
- 4.7.5 Competitive Rivalry
5 Market Size & Growth Forecasts
- 5.1 By Product Type (Value)
- 5.1.1 Reagent & Kits
- 5.1.2 Instruments
- 5.1.3 Services
- 5.2 By Technology (Value)
- 5.2.1 LC-MS/MS
- 5.2.2 Chemiluminescence Immunoassay (CLIA)
- 5.2.3 ELISA
- 5.2.4 Radio-Immunoassay (RIA)
- 5.2.5 Others
- 5.3 By End User (Value)
- 5.3.1 Diagnostic Laboratories
- 5.3.2 Hospitals & Clinics
- 5.3.3 Home-care & Remote Testing
- 5.3.4 Others
- 5.4 By Sample Type (Value)
- 5.4.1 Serum / Plasma
- 5.4.2 Whole Blood
- 5.4.3 Dried Blood Spot
- 5.4.4 Others
- 5.5 By Geography (Value)
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 Europe
- 5.5.2.1 Germany
- 5.5.2.2 United Kingdom
- 5.5.2.3 France
- 5.5.2.4 Italy
- 5.5.2.5 Spain
- 5.5.2.6 Rest of Europe
- 5.5.3 Asia-Pacific
- 5.5.3.1 China
- 5.5.3.2 India
- 5.5.3.3 Japan
- 5.5.3.4 South Korea
- 5.5.3.5 Australia
- 5.5.3.6 Rest of Asia-Pacific
- 5.5.4 South America
- 5.5.4.1 Brazil
- 5.5.4.2 Argentina
- 5.5.4.3 Rest of South America
- 5.5.5 Middle East and Africa
- 5.5.5.1 GCC
- 5.5.5.2 South Africa
- 5.5.5.3 Rest of Middle East and Africa
- 5.5.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Market Share Analysis
- 6.3 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products & Services, and Recent Developments)
- 6.3.1 Abbott Laboratories
- 6.3.2 F. Hoffmann-La Roche AG
- 6.3.3 Siemens Healthineers AG
- 6.3.4 Danaher Corporation (Beckman Coulter)
- 6.3.5 Thermo Fisher Scientific Inc.
- 6.3.6 DiaSorin S.p.A.
- 6.3.7 Quest Diagnostics Incorporated
- 6.3.8 bioMerieux SA
- 6.3.9 Bio-Rad Laboratories Inc.
- 6.3.10 Ortho Clinical Diagnostics Holdings plc
- 6.3.11 Grifols S.A.
- 6.3.12 Randox Laboratories Ltd.
- 6.3.13 Shenzhen Mindray Bio-Medical Electronics Co., Ltd.
- 6.3.14 Tosoh Corporation
- 6.3.15 Sysmex Corporation
- 6.3.16 Eurofins Scientific SE
- 6.3.17 ARUP Laboratories
- 6.3.18 Cerba HealthCare SAS
- 6.3.19 Unilabs AB
- 6.3.20 Biomerica Inc.
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-Need Assessment

