PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2117380

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2117380
Fixed-Wing VTOL UAV - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2025 - 2030)
According to Mordor Intelligence, the fixed-wing VTOL UAV market size is USD 1.32 billion in 2025 and is forecasted to reach USD 3.79 billion by 2030, expanding at a 23.48% CAGR.
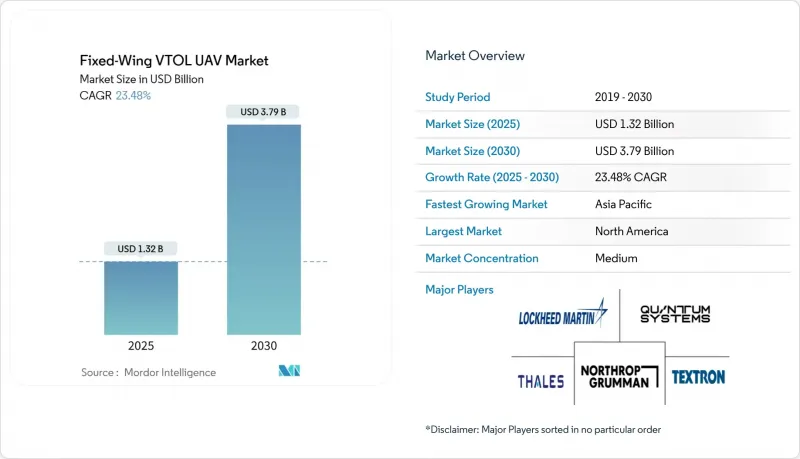
This report is Segmented by Application (ISR, Combat Operations, Border Management, and Others), Propulsion Type (Electric, Hybrid-Electric, Fuel-Cell, and Conventional), Mode of Operation (Autonomous, and More), MTOW Class (Less Than 25 Kg, 25 To 150 Kg, and More), Range (Short, Medium, and Long), and Geography (North America, Europe, and More). The Market Forecasts are Provided in Terms of Value (USD).
Global Fixed-Wing VTOL UAV Market Trends and Insights
Rising Global Demand for Runway-Independent ISR and Surveillance Platforms
Armed forces increasingly favor fixed-wing VTOL UAV market solutions that avoid vulnerable runways while preserving fixed-wing endurance. Turkey's 2025 tactical VTOL drone achieves 10-hour endurance and 1,300 km range from a 12-foot square deck, illustrating the operational leap offered by vertical launch and cruise efficiency. Japan's purchase of V-BAT systems for naval surveillance shows similar prioritization of confined-space operations. Border agencies deploy these aircraft to establish rapid, infrastructure-free coverage in remote sectors, and multi-fuel capabilities such as those on the APUS 25 enhance logistical resilience in dispersed missions. The dual ability to hover for target identification and sprint to new taskings is unmatched by pure rotorcraft or runway-bound fixed-wing types.
Expansion of Commercial Mapping and Aerial Surveying Applications
Surveying firms are replacing light aircraft with fixed-wing VTOL UAV market platforms that combine vertical launch ease with high-speed area coverage. XAG's M2000 maps 533 hectares per hour during 90-minute sorties at centimeter-level accuracy, removing runway dependencies for agricultural clients. Aeromao's VT-NAUT extends missions to altitudes of 4,900 m, reaching mountainous mining sites inaccessible by ground teams. Hydrogen-powered prototypes such as the 100 kg-MTOW DAPHNE aim for zero-emission environmental surveys, aligning with strict European sustainability mandates. Post-mining subsidence monitoring and multispectral imaging create recurring revenue streams that offset higher acquisition costs versus multirotors.
Higher Acquisition Costs Compared to Multirotor Alternatives
Dual-mode aerostructures, complex transition flight controls, and hybrid powertrains raise unit prices to USD 98,000-500,000 for light-class aircraft, versus lower-priced multirotors. Service costs also escalate because technicians must maintain both electric and combustion subsystems. That premium narrows in endurance-driven roles where fixed-wing efficiency halves per-hour operating costs over long sorties. RAND research notes that commercial scale should eventually compress military procurement prices as production volumes rise, supporting the Fixed-Wing VTOL UAV Market.
Other drivers and restraints analyzed in the detailed report include:
- Progress in Regulatory Approvals for Beyond Visual Line-of-Sight Operations
- Technological Advancements in Hybrid-Electric Propulsion Systems
- Endurance Limitations Due to Current Battery Energy Density Constraints
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
ISR platforms dominated the fixed-wing VTOL UAV market in 2024 with a 46.89% share, and their 25.34% CAGR underlines sustained procurement for runway-independent surveillance. The V-BAT's 10-hour endurance from a 12-foot deck illustrates why navies and border forces prioritize these aircraft. Commercial off-the-shelf sensors accelerate payload upgrades, expanding use cases into signals intelligence and disaster assessment.
Combat operations constitute the fastest-rising niche within the segment, propelled by trials of air-launched precision munitions such as Hero 120 from C-130 ramp deployment. Cross-domain tactics integrate hover-and-strike payloads, turning ISR airframes into multi-mission assets. Civil operators leverage ISR-derived optics for pipeline monitoring and wildlife protection, illustrating technology spillover across markets.
Electric powertrains held 53.75% of the fixed-wing VTOL UAV market share in 2024 as regulators favored noise- and emission-free craft. Fuel-cell models, however, scale faster at 27.56% CAGR because PEM stacks offer superior energy density on 2-hour-plus sorties. Operators balancing endurance and sustainability increasingly view hydrogen as a long-term solution.
Hybrid-electric remains an essential bridge technology. A compound-wing demonstrator's 25-minute endurance gain shows how battery-engine pairing can expand the fixed-wing VTOL UAV market size for long-range mapping missions. Conventional fuel systems persist for payload-heavy military tasks where rapid refueling trumps emission targets.
Complete Report Scope:
- By Application
- Intelligence, Surveillance, and Reconnaissance (ISR)
- Combat Operations
- Border Management
- Others
- By Propulsion Type
- Electric
- Hybrid-Electric
- Fuel-Cell
- Conventional
- By Mode of Operation
- Autonomous
- Remotely Piloted
- Optionally Piloted
- By MTOW Class
- Less than 25 kg
- 25 to 150 kg
- Greater than 150 kg
- By Range
- Short Range
- Medium Range
- Long Range
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- United Kingdom
- France
- Germany
- Italy
- Rest of Europe
- Asia-Pacific
- China
- India
- Japan
- South Korea
- Australia
- Rest of Asia-Pacific
- South America
- Brazil
- Rest of South America
- Middle East and Africa
- Middle East
- Saudi Arabia
- United Arab Emirates
- Rest of Middle East
- Africa
- South Africa
- Rest of Africa
- Middle East
- North America
Geography Analysis
North America led the fixed-wing VTOL UAV market with a 36.55% share in 2024, sustained by defense outlays, early BVLOS waivers, and strong domestic manufacturing. AeroVironment posted USD 821 million revenue in fiscal 2025 and is consolidating capabilities through the USD 4.1 billion BlueHalo acquisition to scale autonomous systems. The FAA's powered-lift rule and Dallas BVLOS precedent position the US for widespread commercial rollouts, while Canada and Mexico benefit from trilateral supply-chain alignment under USMCA.
Asia-Pacific is the fastest-growing region, with a 24.89% CAGR. China's tilt-rotor prototype, Japan's USD 25 million V-BAT buy, and South Korea's electronics expertise reinforce a robust pipeline of defense and civil programs. Agricultural drone use, disaster response needs, and growing offshore-wind assets widen the civil addressable market. Local production incentives in India and Australia enhance cost competitiveness and encourage global export ambitions.
Europe's growth is steady, anchored by EASA's 2025 VCA framework that standardizes certification across member states. Germany's battery-management know-how, France's defense industrial base, and Scandinavia's offshore-wind focus foster diverse demand. The DAPHNE hydrogen UAV illustrates Europe's emphasis on zero-emission surveillance for environmental stewardship. UK CAP2537 guidance advances home-grown certification while Pan-EU airspace harmonization simplifies cross-border operations.
- AeroVironment, Inc.
- Lockheed Martin Corporation
- Quantum-Systems GmbH
- Alti Unmanned
- Thales Group
- Israel Aerospace Industries Ltd.
- Northrop Grumman Corporation
- Textron, Inc.
- BAE Systems plc
- Autel Robotics Co., Ltd.
- Swift Engineering Inc.
- Elbit Systems Ltd.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising global demand for runway-independent ISR and surveillance platforms
- 4.2.2 Expansion of commercial mapping and aerial surveying applications
- 4.2.3 Progress in regulatory approvals for beyond visual line-of-sight (BVLOS) operations
- 4.2.4 Technological advancements in hybrid-electric propulsion systems
- 4.2.5 Adoption of UAVs for environmental monitoring in hazardous sites
- 4.2.6 Growing use of high-wind-capable UAVs for offshore wind farm inspections
- 4.3 Market Restraints
- 4.3.1 Higher acquisition costs compared to multi-rotor UAV alternatives
- 4.3.2 Endurance limitations due to current battery energy density constraints
- 4.3.3 Shortage of skilled talent for hybrid flight control software development
- 4.3.4 Airspace congestion challenges around vertiport infrastructure
- 4.4 Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Suppliers
- 4.7.3 Bargaining Power of Buyers
- 4.7.4 Threat of Substitutes
- 4.7.5 Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS
- 5.1 By Application
- 5.1.1 Intelligence, Surveillance, and Reconnaissance (ISR)
- 5.1.2 Combat Operations
- 5.1.3 Border Management
- 5.1.4 Others
- 5.2 By Propulsion Type
- 5.2.1 Electric
- 5.2.2 Hybrid-Electric
- 5.2.3 Fuel-Cell
- 5.2.4 Conventional
- 5.3 By Mode of Operation
- 5.3.1 Autonomous
- 5.3.2 Remotely Piloted
- 5.3.3 Optionally Piloted
- 5.4 By MTOW Class
- 5.4.1 Less than 25 kg
- 5.4.2 25 to 150 kg
- 5.4.3 Greater than 150 kg
- 5.5 By Range
- 5.5.1 Short Range
- 5.5.2 Medium Range
- 5.5.3 Long Range
- 5.6 By Geography
- 5.6.1 North America
- 5.6.1.1 United States
- 5.6.1.2 Canada
- 5.6.1.3 Mexico
- 5.6.2 Europe
- 5.6.2.1 United Kingdom
- 5.6.2.2 France
- 5.6.2.3 Germany
- 5.6.2.4 Italy
- 5.6.2.5 Rest of Europe
- 5.6.3 Asia-Pacific
- 5.6.3.1 China
- 5.6.3.2 India
- 5.6.3.3 Japan
- 5.6.3.4 South Korea
- 5.6.3.5 Australia
- 5.6.3.6 Rest of Asia-Pacific
- 5.6.4 South America
- 5.6.4.1 Brazil
- 5.6.4.2 Rest of South America
- 5.6.5 Middle East and Africa
- 5.6.5.1 Middle East
- 5.6.5.1.1 Saudi Arabia
- 5.6.5.1.2 United Arab Emirates
- 5.6.5.1.3 Rest of Middle East
- 5.6.5.2 Africa
- 5.6.5.2.1 South Africa
- 5.6.5.2.2 Rest of Africa
- 5.6.5.1 Middle East
- 5.6.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 AeroVironment, Inc.
- 6.4.2 Lockheed Martin Corporation
- 6.4.3 Quantum-Systems GmbH
- 6.4.4 Alti Unmanned
- 6.4.5 Thales Group
- 6.4.6 Israel Aerospace Industries Ltd.
- 6.4.7 Northrop Grumman Corporation
- 6.4.8 Textron, Inc.
- 6.4.9 BAE Systems plc
- 6.4.10 Autel Robotics Co., Ltd.
- 6.4.11 Swift Engineering Inc.
- 6.4.12 Elbit Systems Ltd.
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-Need Assessment

