PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2117459

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2117459
Automotive Piston - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
According to Mordor Intelligence, the automotive piston market size is expected to grow from USD 2.98 billion in 2025 to USD 3.05 billion in 2026 and is forecast to reach USD 3.41 billion by 2031 at a 2.25% CAGR over 2026-2031.
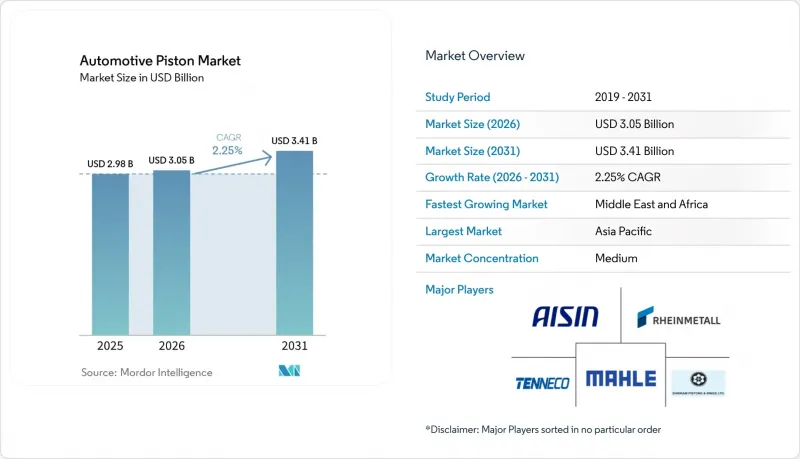
This report is Segmented by Component Type (Piston, Piston Ring, and Piston Pin), Coating Type (Oil Shedding, Dry Film Lubrication, and Thermal Barrier), Vehicle Type (Passenger Cars and Commercial Vehicles), Material Type (Aluminum and Steel), and Geography (North America, South America, Europe, Asia-Pacific, and More). The Market Forecasts are Provided in Terms of Value (USD) and Volume (Units).
Global Automotive Piston Market Trends and Insights
Continued ICE Demand in Emerging Markets
Emerging economies still rely on ICE powertrains because charging infrastructure remains limited and vehicle affordability is crucial. India exported more than 800,000 vehicles in fiscal 2025, most of them gasoline or flex-fuel models serving Africa and Latin America. China follows a dual-track approach, keeping ICE exports flowing even while domestic sales shift toward battery-electric platforms. Brazil's ethanol program and Argentina's CNG taxi fleets extend the service life of piston-equipped engines, supporting regional demand. Suppliers with plants in Uttar Pradesh, Sao Paulo, or Monterrey can meet this volume efficiently. The automotive piston market benefits because low-income buyers in these regions prioritize proven ICE technology over newer alternatives.
Stringent Emissions Pushing Lightweight Aluminum and Coated Pistons
Euro 7 legislation, effective mid-2025, and forthcoming Bharat Stage 7 standards are pushing automakers toward lighter, better-cooled pistons that curb NOx and particulate emissions. Aluminum pistons with thermal-barrier crowns lower peak temperatures and allow higher compression without knock. Skirt coatings infused with molybdenum disulfide cut friction at cold start, aiding fleet-average CO2 compliance in Europe and the United States. These regulations encourage rapid technology refresh cycles, creating new contract opportunities for coated-piston specialists. As similar rules proliferate in Southeast Asia and South America, the automotive piston market scales these solutions across multiple continents.
Accelerating EV Penetration Cannibalizes ICE Volumes
Battery-electric vehicles captured roughly 40% of new registrations in China and 25% in Europe during 2025, directly displacing piston demand. Tesla, BYD, and other EV manufacturers are scaling capacity, and legacy OEMs are reallocating capital to meet carbon-neutral pledges. Fewer ICE vehicles mean fewer pistons across both OEM and aftermarket channels. The revenue impact is most severe in regions offering purchase incentives or zero-emission mandates. Suppliers are offsetting this decline by targeting markets with slower EV uptake, but the overall drag on the automotive piston market remains material.
Other drivers and restraints analyzed in the detailed report include:
- Growing Vehicle Parc Driving Aftermarket Piston Replacement
- Hydrogen-ICE Prototypes Need High-Temperature Steel Pistons
- Engine Downsizing Reduces Piston Count per Vehicle
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Pistons accounted for the largest share, 49.02% of 2025 component revenue, anchoring the automotive piston market share for this segmentation. Suppliers continue refining crown geometry and skirt profiles to manage heat and reduce friction in stricter emissions regimes. Design efforts focus on weight trimming to harmonize with higher cylinder pressures in downsized engines. Pistons thus remain the volume backbone despite pressure to electrify. Tier-1 manufacturers leverage global foundries to assure just-in-time delivery for high-volume assembly plants.
Piston pins registered the fastest 3.84% CAGR as OEMs adopt DLC-coated, case-hardened varieties for turbocharged platforms. The upgrade boosts fatigue life and enables higher RPM without galling. Aftermarket buyers favor complete pin-ring kits that streamline overhaul labor. Industry collaboration with coating specialists accelerates qualification cycles and shortens time-to-market. As value shifts toward high-precision pins, smaller niche producers gain room to differentiate.
Thermal-barrier coatings led with a dominant 42.34% share in 2025, reinforcing their role in insulating piston crowns and stabilizing combustion. These ceramic-based layers help meet PN10 standards in Euro 7 and upcoming EPA rules. OEMs prioritize durability over cost, awarding multi-year contracts for proven suppliers. Integration with lightweight aluminum pistons reduces mass while preserving thermal protection. Certification per global lab protocols has become an entry requirement.
Dry-film lubrication coatings set the pace with a 3.29% CAGR, the fastest within this segment. Molybdenum disulfide blends lower boundary friction during cold starts, contributing to lower fleet-average CO2. Emerging chemistries use tungsten disulfide and graphite nanoflakes to extend life at higher loads. Multilayer coatings combine oil-shedding properties, thereby increasing the functional density per unit area. As automakers seek every gram of CO2 reduction, the automotive piston market rewards suppliers offering validated friction-reduction gains.
Complete Report Scope:
- By Component Type
- Piston
- Piston Ring
- Piston Pin
- By Coating Type
- Oil Shedding
- Dry Film Lubrication
- Thermal Barrier
- By Vehicle Type
- Passenger Cars
- Commercial Vehicles
- By Material Type
- Aluminum
- Steel
- By Region
- North America
- United States
- Canada
- Rest of North America
- South America
- Brazil
- Argentina
- Rest of South America
- Europe
- United Kingdom
- Germany
- Spain
- Italy
- France
- Russia
- Rest of Europe
- Asia-Pacific
- India
- China
- Japan
- South Korea
- Rest of Asia-Pacific
- Middle East and Africa
- United Arab Emirates
- Saudi Arabia
- Turkey
- Egypt
- South Africa
- Rest of Middle East and Africa
- North America
Geography Analysis
Asia-Pacific generated 47.71% of 2025 revenue, underscoring its centrality to the automotive piston market. India's export-oriented assembly lines ship gasoline compact cars to Africa and Latin America, prolonging global ICE demand. China maintains large-scale ICE output for Belt-and-Road partners even as domestic sales tilt toward EVs. Japan emphasizes hybrid and hydrogen initiatives, requiring precision-machined pistons with specialized coatings. Regional suppliers invest in dual production lines to handle both cost-sensitive cast aluminum and premium coated products.
Europe and North America are mature but remain critical through stringent emissions mandates and sizable aftermarket fleets. Euro 7 and EPA 2027 standards oblige OEMs to refine combustion chambers, keeping piston innovation alive despite falling volumes. Aging vehicle populations elevate replacement sales, buffering suppliers from new-vehicle volatility. Capital infusions, such as General Motors' recent upgrades to V-engine plants, confirm a lengthy transition rather than an abrupt ICE exit. Local Tier-1s secure profitability by offering value-added coatings and rapid aftermarket distribution.
The Middle East and Africa, forecasted to grow at a 2.52% CAGR, and South America offer volume upside because electrification lags due to infrastructure and affordability constraints. Brazil's ethanol fleet and Argentina's CNG taxis need high-compression pistons resistant to corrosive fuels. Oil-funded fleets in Gulf states renew ICE vehicles on shorter cycles, supporting OEM assembly kits and aftermarket parts. Suppliers with facilities in Mexico or South Africa leverage trade agreements to serve both continents efficiently. Collectively, these emerging regions add growth breadth to the automotive piston market as advanced economies pivot to electrified powertrains.
- Mahle GmbH
- Tenneco Inc.
- Rheinmetall AG (Kolbenschmidt)
- Aisin Corporation
- Shriram Pistons and Rings Ltd.
- Hitachi Astemo Ltd.
- NPR Holdings Co. Ltd.
- RIKEN Corporation
- Art Metal Mfg. Co. Ltd.
- Burgess Norton
- Bohai Automotive Systems
- Hirschvogel Group
- Dongsuh Industrial Co.
- India Pistons Ltd.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Continued ICE Vehicle Demand in Emerging Markets
- 4.2.2 Stringent Emissions Pushing Lightweight Al and Coated Pistons
- 4.2.3 Growing Vehicle Parc Driving Aftermarket Piston Replacement
- 4.2.4 Hydrogen ICE Prototypes Need High-Temperature Steel Pistons
- 4.2.5 Low-Friction Skirt Coatings for Fuel-Economy Credits
- 4.2.6 3-D Printed Custom Pistons for Performance Tuning
- 4.3 Market Restraints
- 4.3.1 Accelerating EV Penetration Cannibalises ICE Volumes
- 4.3.2 Engine Downsizing Reduces Piston Count Per Vehicle
- 4.3.3 Cylinder-Deactivation Cuts Piston Duty Cycles
- 4.3.4 OEM Cap-Ex Diverted to E-Powertrain R&D
- 4.4 Value / Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Threat of New Entrants
- 4.7.2 Threat of Substitutes
- 4.7.3 Bargaining Power of Suppliers
- 4.7.4 Bargaining Power of Buyers
- 4.7.5 Intensity of Competitive Rivalry
5 Market Size and Growth Forecasts (Value (USD) and Volume (Units))
- 5.1 By Component Type
- 5.1.1 Piston
- 5.1.2 Piston Ring
- 5.1.3 Piston Pin
- 5.2 By Coating Type
- 5.2.1 Oil Shedding
- 5.2.2 Dry Film Lubrication
- 5.2.3 Thermal Barrier
- 5.3 By Vehicle Type
- 5.3.1 Passenger Cars
- 5.3.2 Commercial Vehicles
- 5.4 By Material Type
- 5.4.1 Aluminum
- 5.4.2 Steel
- 5.5 By Region
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Rest of North America
- 5.5.2 South America
- 5.5.2.1 Brazil
- 5.5.2.2 Argentina
- 5.5.2.3 Rest of South America
- 5.5.3 Europe
- 5.5.3.1 United Kingdom
- 5.5.3.2 Germany
- 5.5.3.3 Spain
- 5.5.3.4 Italy
- 5.5.3.5 France
- 5.5.3.6 Russia
- 5.5.3.7 Rest of Europe
- 5.5.4 Asia-Pacific
- 5.5.4.1 India
- 5.5.4.2 China
- 5.5.4.3 Japan
- 5.5.4.4 South Korea
- 5.5.4.5 Rest of Asia-Pacific
- 5.5.5 Middle East and Africa
- 5.5.5.1 United Arab Emirates
- 5.5.5.2 Saudi Arabia
- 5.5.5.3 Turkey
- 5.5.5.4 Egypt
- 5.5.5.5 South Africa
- 5.5.5.6 Rest of Middle East and Africa
- 5.5.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (Includes Global Level Overview, Market Level Overview, Core Segments, Financials as Available, Strategic Information, Market Rank/Share for Key Companies, Products and Services, SWOT Analysis, and Recent Developments)
- 6.4.1 Mahle GmbH
- 6.4.2 Tenneco Inc.
- 6.4.3 Rheinmetall AG (Kolbenschmidt)
- 6.4.4 Aisin Corporation
- 6.4.5 Shriram Pistons and Rings Ltd.
- 6.4.6 Hitachi Astemo Ltd.
- 6.4.7 NPR Holdings Co. Ltd.
- 6.4.8 RIKEN Corporation
- 6.4.9 Art Metal Mfg. Co. Ltd.
- 6.4.10 Burgess Norton
- 6.4.11 Bohai Automotive Systems
- 6.4.12 Hirschvogel Group
- 6.4.13 Dongsuh Industrial Co.
- 6.4.14 India Pistons Ltd.
7 Market Opportunities and Future Outlook
- 7.1 White-space and Unmet-Need Assessment

