PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2118894

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2118894
Branded Content Services - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
According to Mordor Intelligence, the branded content services market size is projected to expand from USD 81.16 billion in 2025 and USD 90.35 billion in 2026 to USD 152.21 billion by 2031, registering a CAGR of 10.99% between 2026 to 2031.
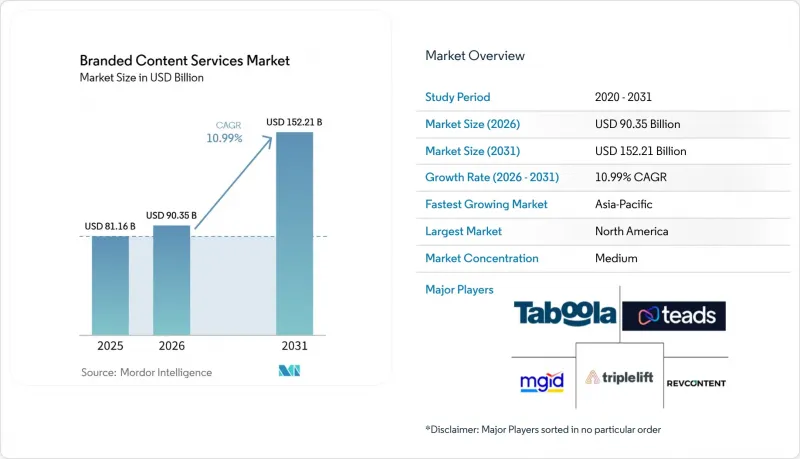
This report is Segmented by Platform Model (Closed Platforms, Open Web Publisher Networks, and Hybrid Platforms), Device (Mobile, Desktop and Laptop, Connected TV, and Tablet), Industry Verticals (Retail and E-Commerce, Media and Entertainment, Healthcare and Life Sciences, Travel and Hospitality, Consumer Goods, and More), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global Branded Content Services Market Trends and Insights
Shift Toward Non-Intrusive Advertising Formats
Consumer resistance to interruptive advertising has made less disruptive formats a core requirement for effective brand communication, especially where audiences can skip, block, or ignore standard ad units. U.S. digital advertising revenue exceeded USD 150 billion in 2024, although broad reach did not resolve declining engagement with standard display and pre-roll formats. The branded content services market benefits when advertising is presented in a form that fits the editorial setting, the subject matter, and the audience's viewing behavior. Native articles and creator-hosted formats can support longer engagement and stronger recall because they reduce the disruption associated with conventional advertising. Premium publishers are also raising editorial standards to protect audience trust, which increases the quality expected from sponsored work and makes execution more dependent on editorial planning. This supports experienced studios and gives publishers more leverage when they negotiate commercial programs.
Video-First Content Consumption Across Publisher and Social Environments
Video is gaining importance because social feeds, connected TV, and short-form video applications are designed for video viewing and make video assets easier to distribute repeatedly. Connected TV advertisers are increasing their spending plans, with 70% expecting to raise spending by an average of 17% in 2026. This supports the branded content services market by moving premium brand budgets toward addressable digital video environments where content can be integrated into the viewing experience. Creator video can also be used as paid media against a brand's own audience data, which makes it more useful beyond a single organic post. The production and distribution systems for creator video are becoming more closely connected across social platforms, allowing a successful asset to be adapted across several placements. As a result, video content is becoming part of a recurring media investment cycle rather than a separate creative experiment.
Disclosure and Trust Scrutiny Around Sponsored Editorial Content
Disclosure requirements are becoming more demanding across major advertising jurisdictions, so legal, platform, and publisher reviews increasingly occur before content can be released. The Federal Trade Commission provides guidance on clear and conspicuous disclosures for endorsements, influencer content, and reviews. The European Commission's AI Act framework also sets transparency duties for certain AI-generated content. The branded content services market faces longer approval cycles when programs include sponsored editorial work or AI-assisted creative, particularly when a campaign is intended for several jurisdictions. These checks can limit the use of synthetic likenesses in campaigns that need to move quickly and can require earlier coordination between creative, legal, and publisher teams. Clear labeling remains important because unclear sponsored content can damage both the advertiser relationship and the publisher's audience trust.
Other drivers and restraints analyzed in the detailed report include:
- First-Party and Contextual Targeting Demand in a Cookieless Media Mix
- Creator Economy Scaling Into Always-On Brand Programs
- ROI Attribution Fragmentation Across Publishers, Creators, and Platforms
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Closed platforms held 57.62% of branded content services market size in 2025. Meta, TikTok, YouTube, and LinkedIn combine large audiences with mature creator-to-brand monetization systems. Their in-feed formats make sponsored content easier to distribute alongside ordinary audience activity, reducing the separation between a paid placement and the surrounding viewing experience. Meta's partnership advertising format reached an annualized revenue run rate of USD 10 billion in the first quarter of 2026, which showed the growing commercial role of creator-produced content. LinkedIn launched its Creator Marketplace in June 2026, extending branded content infrastructure to professional audiences as closed platforms continue to attract budgets by linking content creation, targeting, distribution, and reporting within a single operating environment.
Open web publisher networks compete through editorial quality, brand safety, and verified first-party audiences rather than raw reach. The New York Times T Brand Studio, BBC StoryWorks, Guardian Labs, Financial Times Commercial, and Hearst studios use these strengths to support premium integrations. Hybrid platforms bridge programmatic distribution with publisher-native placements through firms such as Taboola, Outbrain, MGID, and TripleLift. Hybrid platforms are projected to grow at an 11.63% CAGR from 2026 to 2031. In June 2026, Taboola opened the monetization system behind DeeperDive to external AI companies, chatbot developers, and virtual assistant providers, showing how hybrid operators are adapting from content recommendation to infrastructure for AI-mediated discovery.
Complete Report Scope:
- By Platform Model
- Closed Platforms
- Open Web Publisher Networks
- Hybrid Platforms
- By Device
- Mobile
- Desktop and Laptop
- Connected TV
- Tablet
- By Industry Verticals
- Retail and E-commerce
- Media and Entertainment
- Healthcare and Life Sciences
- Travel and Hospitality
- Consumer Goods
- Other Industry Verticals (BFSI, Education,Automotive & IT and Telecom )
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Chile
- Rest of South America
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- South Korea
- Australia
- Rest of Asia-Pacific
- Middle East
- Saudi Arabia
- United Arab Emirates
- Qatar
- Rest of Middle East
- Africa
- South Africa
- Egypt
- Nigeria
- Rest of Africa
- North America
Geography Analysis
North America held 37.62% of the branded content services market share in 2025. The region has a high concentration of native advertising platforms, premium publisher studios, and retail media networks. U.S. creator economy advertising spend reached USD 37.1 billion in 2025 and is projected to reach USD 43.9 billion in 2026. This makes the region the largest setting for creator-led branded content programs, while publisher consolidation is changing the competitive structure.
In July 2026, Lupa Systems completed its acquisition of New York Magazine, the Vox Media Podcast Network, and Vox. Penske Media Corporation acquired the remaining Vox Media digital brand portfolio, including The Verge, Eater, SB Nation, Popsugar, Punch, and Thrillist. South America remains smaller but is growing in Brazil and Argentina as social video use and local retail media networks expand. Measurement infrastructure and creator monetization gaps limit institutional brand investment in the region. Europe has growing demand in Germany, the United Kingdom, and France, but data protection and AI transparency obligations add execution requirements.
Premium publishing groups in the United Kingdom continue to provide strong studio infrastructure for quality-engaged audiences. Asia-Pacific is projected to grow at a 12.43% CAGR from 2026 to 2031, supported by video consumption, super-app commerce systems in China, and connected TV adoption in India and South Korea. Japan's internet advertising market reached JPY 4.0459 trillion in 2025 (USD 26.79 billion), and internet ad media fees are estimated at JPY 3.584 trillion (USD 23.74 billion), in 2026. Video advertising in Japan recorded 14.7% year-on-year growth, while TikTok surpassed 42 million monthly users in the country in 2026. The Middle East is emerging through sovereign media investments and luxury campaigns, while Africa remains earlier stage, led by South Africa and Nigeria.
- Taboola.com Ltd.
- Outbrain Inc.
- MGID Inc.
- TripleLift, Inc.
- Life360, Inc.
- Revcontent, LLC
- Thomson Reuters Corporation
- The New York Times Company
- Vox Media, LLC
- Hearst Communications, Inc.
- BBC Studios Limited
- Future plc
- Penske Media Corporation
- Gannett Co., Inc.
- Dotdash Meredith, Inc.
- Advance Magazine Publishers Inc.
- Guardian News & Media Limited
- Financial Times Limited
- A360media LLC
- BuzzFeed, Inc.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Shift Toward Non-Intrusive Advertising Formats
- 4.2.2 Video-First Content Consumption Across Publisher and Social Environments
- 4.2.3 First-Party and Contextual Targeting Demand in a Cookieless Media Mix
- 4.2.4 Creator Economy Scaling Into Always-On Brand Programs
- 4.2.5 Retail Media and Commerce Content Convergence
- 4.2.6 AI-Led Creative Adaptation and Performance Measurement
- 4.3 Market Restraints
- 4.3.1 Disclosure and Trust Scrutiny Around Sponsored Editorial Content
- 4.3.2 ROI Attribution Fragmentation Across Publishers, Creators, and Platforms
- 4.3.3 Rights Management Risk for AI-Generated Assets and Talent Likeness
- 4.3.4 Editorial Firewall and Governance Constraints at Premium Publishers
- 4.4 Industry Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Bargaining Power of Buyers
- 4.7.2 Bargaining Power of Suppliers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
- 4.8 Impact of Macroeconomic Factors on the Market
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Platform Model
- 5.1.1 Closed Platforms
- 5.1.2 Open Web Publisher Networks
- 5.1.3 Hybrid Platforms
- 5.2 By Device
- 5.2.1 Mobile
- 5.2.2 Desktop and Laptop
- 5.2.3 Connected TV
- 5.2.4 Tablet
- 5.3 By Industry Verticals
- 5.3.1 Retail and E-commerce
- 5.3.2 Media and Entertainment
- 5.3.3 Healthcare and Life Sciences
- 5.3.4 Travel and Hospitality
- 5.3.5 Consumer Goods
- 5.3.6 Other Industry Verticals (BFSI, Education,Automotive & IT and Telecom )
- 5.4 By Geography
- 5.4.1 North America
- 5.4.1.1 United States
- 5.4.1.2 Canada
- 5.4.1.3 Mexico
- 5.4.2 South America
- 5.4.2.1 Brazil
- 5.4.2.2 Argentina
- 5.4.2.3 Chile
- 5.4.2.4 Rest of South America
- 5.4.3 Europe
- 5.4.3.1 Germany
- 5.4.3.2 United Kingdom
- 5.4.3.3 France
- 5.4.3.4 Italy
- 5.4.3.5 Spain
- 5.4.3.6 Rest of Europe
- 5.4.4 Asia-Pacific
- 5.4.4.1 China
- 5.4.4.2 Japan
- 5.4.4.3 India
- 5.4.4.4 South Korea
- 5.4.4.5 Australia
- 5.4.4.6 Rest of Asia-Pacific
- 5.4.5 Middle East
- 5.4.5.1 Saudi Arabia
- 5.4.5.2 United Arab Emirates
- 5.4.5.3 Qatar
- 5.4.5.4 Rest of Middle East
- 5.4.6 Africa
- 5.4.6.1 South Africa
- 5.4.6.2 Egypt
- 5.4.6.3 Nigeria
- 5.4.6.4 Rest of Africa
- 5.4.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)
- 6.4.1 Taboola.com Ltd.
- 6.4.2 Outbrain Inc.
- 6.4.3 MGID Inc.
- 6.4.4 TripleLift, Inc.
- 6.4.5 Life360, Inc.
- 6.4.6 Revcontent, LLC
- 6.4.7 Thomson Reuters Corporation
- 6.4.8 The New York Times Company
- 6.4.9 Vox Media, LLC
- 6.4.10 Hearst Communications, Inc.
- 6.4.11 BBC Studios Limited
- 6.4.12 Future plc
- 6.4.13 Penske Media Corporation
- 6.4.14 Gannett Co., Inc.
- 6.4.15 Dotdash Meredith, Inc.
- 6.4.16 Advance Magazine Publishers Inc.
- 6.4.17 Guardian News & Media Limited
- 6.4.18 Financial Times Limited
- 6.4.19 A360media LLC
- 6.4.20 BuzzFeed, Inc.
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment

