PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2118925

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2118925
Hospital Consumables - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
According to Mordor Intelligence, the hospital consumables market size is projected to be USD 428.90 billion in 2025, USD 442.84 billion in 2026, and reach USD 519.63 billion by 2031, growing at a CAGR of 3.25% from 2026 to 2031.
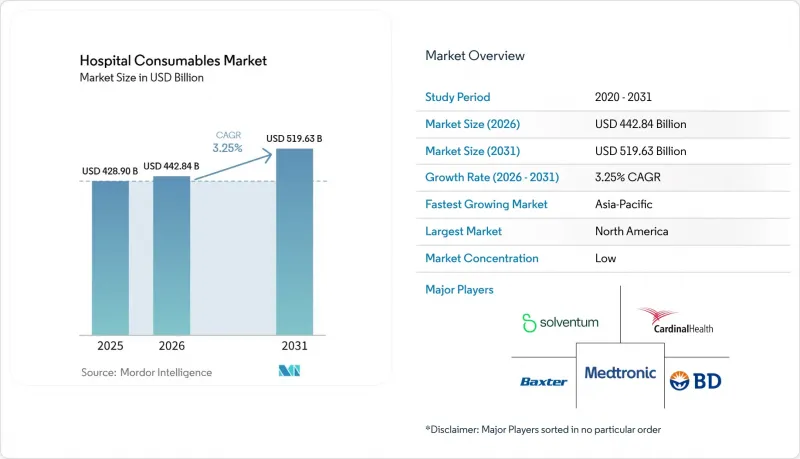
This report is Segmented by Product Type (Non-Woven Disposables, Syringes, IV Kits, Catheters, and Others), Application Area (General Surgery, Intensive Care, and Others), End User (Hospitals, Ascs, and Others), Distribution Channel (Direct Contracts, Gpos, and Others), and Geography (North America, Europe, Asia-Pacific, MEA, and South America). The Market Forecasts are Provided in Terms of Value (USD).
Global Hospital Consumables Market Trends and Insights
Rising Surgical and Minimally Invasive Procedure Volumes
Surgical volumes continued to recover in 2026, while minimally invasive and robotic procedures remained among the faster-growing procedure categories. Each procedure required sterile drapes, gowns, cannulae, irrigation products, and disposable instruments, increasing the clinical use of hospital consumables. In U.S. ambulatory settings, total knee arthroplasty volume grew by 27.6% in 2024, while total hip arthroplasty volume grew by 28.7%. England set a target of 500,000 robotic surgeries annually by 2035, supporting future demand for robotic-compatible single-use products in European acute care settings. The hospital consumables market benefits when suppliers align portfolios with orthopedics, urology, laparoscopic surgery, and other high-growth procedure areas.
Intensifying Healthcare-Associated Infection Prevention Requirements
Healthcare-associated infections remain a major concern for hospitals and public health systems. The World Health Organization reported that 7 in every 100 patients in high-income countries acquired at least 1 healthcare-associated infection during hospitalization, compared with 15 in every 100 patients in lower-middle-income settings. The Centers for Disease Control and Prevention reported 518,000 healthcare-associated infections in U.S. hospitals during 2023, with 61% of reported infections not linked to a specific medical device or procedure. BD received FDA 510(k) clearance for Surgiphor(TM) 1000mL in March 2026, strengthening the role of infection-reduction features in procurement decisions across wound care, vascular access, and surgical applications.
GPO and Centralized-Tender Price Compression
Group purchasing organizations are embedded in the procurement cycle of 97% of US hospitals. Large purchasing organizations use their scale to negotiate lower prices and secure preferred supplier arrangements across hospital networks. The Healthcare Group Purchasing Industry Initiative reported that its members managed more than USD 100 billion in annual purchasing activity while addressing tariff pressure and provider cost constraints. Manufacturers may need to accept lower unit prices to retain contracts, especially in limited-differentiation products such as basic syringes, gloves, gauze, and standard intravenous supplies. This pressure may also push smaller suppliers to exit commodity categories or partner with distributors that support private-label programs.
Other drivers and restraints analyzed in the detailed report include:
- Aging Populations and Chronic-Disease Treatment Intensity
- Hospital Capacity Expansion and ICU Penetration in Emerging Markets
- Ethylene-Oxide Sterilization Capacity and Emissions Constraints
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Non-woven disposable products held 24.55% of the hospital consumables market size in 2025, making them the largest product category. Their leadership reflected broad use in surgical drapes, gowns, face masks, sterile wraps, caps, wound management products, and incontinence care across multiple care settings. Polypropylene spunbond remained widely used due to its cost efficiency and suitability for high-volume manufacturing. European waste regulations and extended producer responsibility frameworks increased attention on biodegradable and bio-based alternatives.
Disposable syringes are forecast to grow at a CAGR of 7.15% between 2026 and 2031. Hospitals and public health programs increasingly used safety-engineered formats, including retractable, auto-disable, and passive-mechanism syringes, supported by occupational safety and sharps injury prevention requirements in North America and Europe. Higher use of GLP-1 receptor agonists for type 2 diabetes and obesity also expanded demand for prefilled and self-injection products. Catheters, intravenous kits, intravenous solutions, guidewires, cannulae, and procedure trays supported recurring revenue through continuous purchasing and bundled contracts.
General surgery and operating rooms accounted for 33.56% of the hospital consumables market share in 2025. Operating rooms used a broad range of consumables in each surgical case, including drapes, gowns, gloves, sutures, blade holders, irrigation systems, specimen containers, and sterile packaging. Complex procedures can require more than USD 300 in consumables per case. The World Health Organization estimated that more than 313 million surgical procedures are performed globally each year, supporting recurring demand for surgical consumables.
Intensive care and critical care are forecast to grow at a CAGR of 5.80% between 2026 and 2031. Intensive care units required continuous supplies of central venous catheters, arterial lines, ventilator circuits, urinary catheters, infusion sets, and glucose monitoring products, driven by expanding critical care capacity in developing healthcare systems. BD launched the CentroVena One(TM) Insertion System in April 2026 for central line placement in acute care settings. Oncology, chemotherapy administration, urology, nephrology, and wound care also supported demand through specialized products and differentiated clinical requirements.
Complete Report Scope:
- By Product Type
- Disposable Medical Gloves
- IV Kits
- Medical Gauze & Tapes
- Disposable Syringes
- Sharps Disposable Containers
- Catheter's
- Non-woven Disposable Products
- Surgical Blades
- Medicine Cups
- Cannula
- Guidewire's
- Thermometer
- Stethoscope
- Glucometer Strips
- IV Solutions
- BP Monitors
- Procedure Trays
- Others
- By Application Area
- General Surgery and Operating Room
- Intensive Care and Critical Care
- Emergency and Trauma Care
- Cardiology and Vascular Intervention
- Urology and Nephrology
- Wound Care and Tissue Management
- Respiratory and Anesthesia Care
- Oncology and Chemotherapy Administration
- Diagnostic and Laboratory Care
- Diabetes and Chronic-Disease Monitoring
- By End User
- Hospitals
- Ambulatory Surgical Centers
- Specialty Clinics and Physician Offices
- Diagnostic Laboratories and Blood Banks
- Long-Term Care and Rehabilitation Facilities
- Home Healthcare Providers
- Others
- By Distribution Channel
- Direct Manufacturer Contracts
- Group Purchasing Organizations
- Medical Distributors and Prime Vendors
- Public Tenders and Framework Agreements
- E-Commerce and Digital Procurement
- Contract Logistics and Vendor-Managed Inventory
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- India
- Japan
- Australia
- South Korea
- Rest of Asia-Pacific
- Middle East and Africa
- GCC
- South Africa
- Rest of Middle East and Africa
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
North America held 40.86% of the hospital consumables market size in 2025. High consumable use per procedure, established safety-device requirements, and a large ambulatory surgical center base supported the region's position. The United States accounted for most regional revenue due to its high volume of complex procedures and detailed product quality requirements. FDA clearance pathways and Joint Commission accreditation standards encouraged the use of products meeting established safety and performance specifications, while Canada moved toward centralized procurement through Medline's May 2026 prime vendor agreement with Mohawk Medbuy. Mexico remained an underpenetrated opportunity as public and private hospital networks continued to expand.
Europe remained the second-largest regional area in the hospital consumables market. Germany, France, the United Kingdom, and Italy formed the core of regional demand. The European Union Medical Device Regulation raised clinical evidence and post-market surveillance requirements, increasing compliance demands for smaller manufacturers and favoring suppliers with established regulatory capabilities and local manufacturing capacity. Convatec completed an expansion of more than GBP 24 million at its United Kingdom advanced wound care manufacturing site during 2026 and also announced research and development investment of more than GBP 500 million, including a Manchester hub planned from 2028.
Asia-Pacific is forecast to grow at a CAGR of 6.88% from 2026 to 2031, making it the fastest-growing regional area. Hospital construction, a growing middle-income population, increasing chronic disease treatment, and broader access to surgery and critical care support demand. India is adding specialty and higher-acuity capacity, increasing demand for operating room, infusion, wound care, and intensive care products, while China remains a major destination due to its extensive healthcare infrastructure and local manufacturing base.
- Ansell
- B. Braun
- Baxter
- Beckton Dickinson
- Boston Scientific
- Cardinal Health
- Coloplast
- Convatec
- Getinge
- ICU Medical
- Mckesson
- Medline Inc.
- Medtronic
- Merit Medical Systems
- Molnlycke Health Care
- Nipro
- Owens & Minor, Inc.
- Hartmann Group
- Smiths Group
- Solventum Corporation
- STERIS
- Stryker
- Teleflex
- Terumo
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising Surgical and Minimally Invasive Procedure Volumes
- 4.2.2 Intensifying Healthcare-Associated Infection Prevention Requirements
- 4.2.3 Aging Populations and Chronic-Disease Treatment Intensity
- 4.2.4 Hospital Capacity Expansion and ICU Penetration in Emerging Markets
- 4.2.5 Shift Toward Standardized Procedure Kits and Point-Of-Care Availability
- 4.2.6 Device-Associated Infection Reduction Through Safer Single-Use Designs
- 4.3 Market Restraints
- 4.3.1 GPO And Centralized-Tender Price Compression
- 4.3.2 Medical Waste, Polymer, and Extended-Producer-Responsibility Costs
- 4.3.3 Ethylene-Oxide Sterilization Capacity and Emissions Constraints
- 4.3.4 Product Liability, Recall, and Quality-System Exposure
- 4.4 Value / Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Threat of new entrants
- 4.7.2 Bargaining power of suppliers
- 4.7.3 Bargaining power of buyers
- 4.7.4 Threat of substitutes
- 4.7.5 Competitive rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE, USD)
- 5.1 By Product Type
- 5.1.1 Disposable Medical Gloves
- 5.1.2 IV Kits
- 5.1.3 Medical Gauze & Tapes
- 5.1.4 Disposable Syringes
- 5.1.5 Sharps Disposable Containers
- 5.1.6 Catheter's
- 5.1.7 Non-woven Disposable Products
- 5.1.8 Surgical Blades
- 5.1.9 Medicine Cups
- 5.1.10 Cannula
- 5.1.11 Guidewire's
- 5.1.12 Thermometer
- 5.1.13 Stethoscope
- 5.1.14 Glucometer Strips
- 5.1.15 IV Solutions
- 5.1.16 BP Monitors
- 5.1.17 Procedure Trays
- 5.1.18 Others
- 5.2 By Application Area
- 5.2.1 General Surgery and Operating Room
- 5.2.2 Intensive Care and Critical Care
- 5.2.3 Emergency and Trauma Care
- 5.2.4 Cardiology and Vascular Intervention
- 5.2.5 Urology and Nephrology
- 5.2.6 Wound Care and Tissue Management
- 5.2.7 Respiratory and Anesthesia Care
- 5.2.8 Oncology and Chemotherapy Administration
- 5.2.9 Diagnostic and Laboratory Care
- 5.2.10 Diabetes and Chronic-Disease Monitoring
- 5.3 By End User
- 5.3.1 Hospitals
- 5.3.2 Ambulatory Surgical Centers
- 5.3.3 Specialty Clinics and Physician Offices
- 5.3.4 Diagnostic Laboratories and Blood Banks
- 5.3.5 Long-Term Care and Rehabilitation Facilities
- 5.3.6 Home Healthcare Providers
- 5.3.7 Others
- 5.4 By Distribution Channel
- 5.4.1 Direct Manufacturer Contracts
- 5.4.2 Group Purchasing Organizations
- 5.4.3 Medical Distributors and Prime Vendors
- 5.4.4 Public Tenders and Framework Agreements
- 5.4.5 E-Commerce and Digital Procurement
- 5.4.6 Contract Logistics and Vendor-Managed Inventory
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 Europe
- 5.5.2.1 Germany
- 5.5.2.2 United Kingdom
- 5.5.2.3 France
- 5.5.2.4 Italy
- 5.5.2.5 Spain
- 5.5.2.6 Rest of Europe
- 5.5.3 Asia-Pacific
- 5.5.3.1 China
- 5.5.3.2 India
- 5.5.3.3 Japan
- 5.5.3.4 Australia
- 5.5.3.5 South Korea
- 5.5.3.6 Rest of Asia-Pacific
- 5.5.4 Middle East and Africa
- 5.5.4.1 GCC
- 5.5.4.2 South Africa
- 5.5.4.3 Rest of Middle East and Africa
- 5.5.5 South America
- 5.5.5.1 Brazil
- 5.5.5.2 Argentina
- 5.5.5.3 Rest of South America
- 5.5.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Market Share Analysis
- 6.3 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)
- 6.3.1 Ansell Limited
- 6.3.2 B. Braun Melsungen AG
- 6.3.3 Baxter International Inc.
- 6.3.4 Becton, Dickinson and Company
- 6.3.5 Boston Scientific Corporation
- 6.3.6 Cardinal Health, Inc.
- 6.3.7 Coloplast A/S
- 6.3.8 ConvaTec Group PLC
- 6.3.9 Getinge AB
- 6.3.10 ICU Medical, Inc.
- 6.3.11 McKesson Corporation
- 6.3.12 Medline Inc.
- 6.3.13 Medtronic plc
- 6.3.14 Merit Medical Systems, Inc.
- 6.3.15 Molnlycke Health Care AB
- 6.3.16 Nipro Corporation
- 6.3.17 Owens & Minor, Inc.
- 6.3.18 Paul Hartmann AG
- 6.3.19 Smith & Nephew plc
- 6.3.20 Solventum Corporation
- 6.3.21 STERIS plc
- 6.3.22 Stryker Corporation
- 6.3.23 Teleflex Incorporated
- 6.3.24 Terumo Corporation
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-need Assessment

