PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2119052

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2119052
Angiostomy Cannula - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
According to Mordor Intelligence, the angiostomy cannula market size is expected to grow from USD 215.52 million in 2025 to USD 231.71 million in 2026 and is forecast to reach USD 332.80 million by 2031 at 7.51% CAGR over 2026-2031.
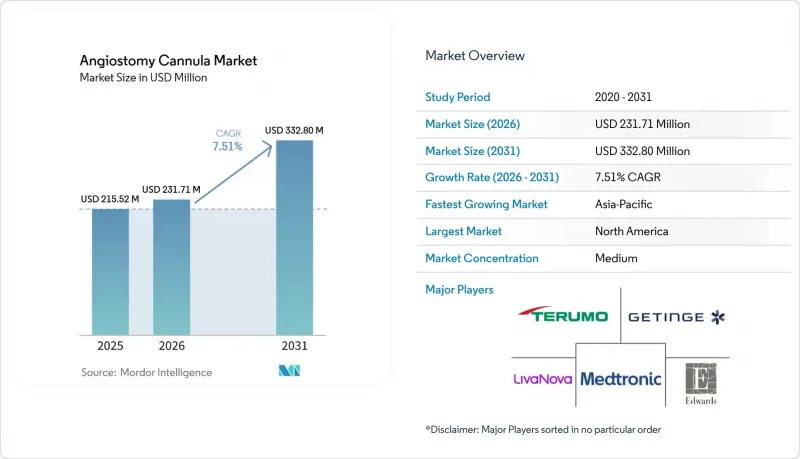
This report is Segmented by Product Type (Cardiac Cannula, Vascular Cannula, and More), Cannulation Site (Aortic and Arterial Sites and More), Material (Polyurethane and More), Tip Design (Straight Tip and More), Application (Cardiopulmonary Bypass Surgery and More), End User (Hospitals, Cardiac Centers, and More), and Geography (North America and More). The Market Forecasts are Provided in Terms of Value (USD).
Global Angiostomy Cannula Market Trends and Insights
Rising Cardiovascular and Critical-Care Procedure Volumes
Cardiovascular disease remains a leading cause of death and disability worldwide, sustaining the clinical need for cardiac and critical-care procedures. The growing chronic disease burden also raises demand for surgical and circulatory support among older patients. Procedure demand differs by country because hospital capacity, clinical workforce availability, and public funding vary widely. Premium configurations remain more relevant in high-income systems, while cost-conscious, compliant products have a wider role in emerging care settings. The angiostomy cannula market benefits when manufacturers can offer both product tiers without compromising the clinical requirements of each setting. Aging populations in Japan, Italy, GCC countries, and South Korea reinforce the longer-term need for cardiac care capacity.
Expansion of ECMO and Extracorporeal Circulation Capability
Each additional ECMO program creates recurring demand for cannulas used across patient episodes rather than demand tied only to elective surgery. Venoarterial ECMO for cardiogenic shock requires large-bore arterial cannulas that can manage high flow and arterial pressure. A clinical report on preclosed femoral access documented the feasibility of fully percutaneous venoarterial ECMO in refractory cardiogenic shock. This clinical direction supports designs with reinforced shafts, reliable flow characteristics, and access features suited to urgent use. Cannula-circuit integration also supports blood conservation and thrombus removal, which can increase the value of a device beyond its role as a standalone consumable. The angiostomy cannula market therefore has a stronger link to intensive care program expansion than to elective procedure growth alone.
Cannulation-Related Vascular Trauma and Thrombotic Risk
Vascular access complications can limit procedure uptake and influence the specifications hospitals use when selecting cannulas. A 2025 prospective study reported a 79.5% incidence of internal jugular vein thrombosis after cannulation for cardiopulmonary bypass, although all thrombi in that cohort were asymptomatic and nonocclusive. This risk increases interest in biocompatible coatings and shaft markings that support real-time imaging. Updated American Society of Echocardiography guidance recommends ultrasound guidance for central vascular access procedures. Centers with integrated imaging can manage access risk more consistently than lower-resource facilities. Cost, reimbursement, and procurement constraints can further slow adoption where hospitals cannot fund the imaging, training, or specialized products that lower this risk.
Other drivers and restraints analyzed in the detailed report include:
- Shift Toward Minimally Invasive and Percutaneous Cannulation
- Biocompatible, Kink-Resistant, and Low-Trauma Cannula Innovation
- Shortage of Specialist Perfusion and Cannulation Personnel
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Cardiac cannulas accounted for 28.31% of the angiostomy cannula market in 2025, reflecting the sustained procedure volume of cardiopulmonary bypass, valve repair, and ECMO. Venous and arterial cannulas serve the large procedural base in open-heart surgery. Cardioplegia cannulas support myocardial protection through aortic root delivery and coronary sinus retrograde perfusion. Vascular cannulas contribute volume in peripheral bypass and revascularization settings.
Thrombus-aspiration cannulas are projected to grow at a 9.58% CAGR from 2026 to 2031, the fastest rate among product types. This growth reflects wider interest in catheter-based clot removal for cardiac and pulmonary care. The angiostomy cannula industry is expanding its product focus from conventional surgical use toward devices suited to interventional treatment pathways. The breadth of a supplier's portfolio will matter as hospitals seek products for both established surgery and specialized aspiration procedures.
Aortic and arterial sites commanded 42.24% of the angiostomy cannula market share in 2025 because central arterial cannulation remains standard in many open-heart procedures. Coronary ostia and coronary sinus sites serve the specialized requirements of cardioplegia delivery. Right atrium, superior vena cava, and inferior vena cava cannulation support standard venous drainage arrangements. Jugular and central venous sites are also relevant to venovenous ECMO for respiratory failure.
Femoral vascular sites are expected to expand at an 8.22% CAGR through 2031 as cardiac surgery adopts more percutaneous and minimally invasive approaches. Research on totally endoscopic cardiac surgery supports Seldinger-guided femorofemoral cannulation, which requires large-bore, thin-walled venous devices with high-flow capacity. Ultrasound guidance can support the shift away from surgical cut-down methods. The angiostomy cannula market can gain from designs that combine high flow with reliable femoral access and safe placement.
Complete Report Scope:
- By Product Type
- Cardiac Cannula
- Vascular Cannula
- Venous Cannula
- Arterial Cannula
- Cardioplegia Cannula
- Thrombus-Aspiration Cannula
- Other Product Types
- By Cannulation Site
- Aortic and Arterial Sites
- Femoral Vascular Sites
- Jugular and Central Venous Sites
- Right Atrium, Superior Vena Cava, and Inferior Vena Cava
- Coronary Ostia and Coronary Sinus
- Other Cannulation Sites
- By Material
- Polyvinyl Chloride
- Polyurethane
- Silicone
- Stainless Steel
- Other Materials
- By Tip Design
- Straight Tip
- Angled Tip
- Curved Tip
- Beveled Tip
- Funnel-Shaped Tip
- Balloon and Self-Expanding Tip
- By Application
- Cardiopulmonary Bypass Surgery
- Extracorporeal Membrane Oxygenation
- Percutaneous Thrombus and Embolus Removal
- Cardioplegia Delivery and Myocardial Protection
- Vascular Surgery and Revascularization
- Other Applications
- By End User
- Hospitals
- Cardiac Centers
- Ambulatory Surgical Centers
- Specialty Clinics
- Other End Users
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- Australia
- South Korea
- Rest of Asia-Pacific
- Middle East and Africa
- GCC
- South Africa
- Rest of Middle East and Africa
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
North America held 45.61% of the global angiostomy cannula market in 2025, supported by dense ECMO program infrastructure and established payment pathways for cardiac surgery. The United States remains important because its hospitals and ambulatory surgical centers use a broad range of cardiac and vascular procedures. The 2026 expansion of cardiovascular procedure coverage in ambulatory surgical centers can support a gradual movement of lower-acuity procedures into outpatient settings. Canada adds procedural demand, but the shortage of perfusionists can restrict cardiac surgery throughput even when devices are available. This workforce constraint increases the value of products and systems that support efficient clinical workflows.
Europe is the second-largest regional market, with Germany, France, and the United Kingdom supporting demand through national cardiac surgery programs. The EU Medical Device Regulation has increased clinical evidence requirements for cardiovascular devices and can lengthen authorization cycles. These requirements favor manufacturers that already have established certifications and clinical documentation. Eastern European cardiac centers and Scandinavian ECMO programs offer incremental consumption potential. Near-term procedure recovery can remain uneven where hospital capacity constraints and patient hesitancy persist.
Asia-Pacific is projected to record the highest regional CAGR of 9.25% from 2026 to 2031. China's procurement approach lowers device prices and can broaden access to cardiovascular treatment, placing pressure on suppliers to manage price and volume together. India is expanding cardiac surgery capability through private hospitals in Tier 2 and Tier 3 cities. Japan's older population creates sustained institutional demand for cardiac care, while South Korea's high-volume cardiac centers offer a concentrated procurement base. Clinical acceptance of ultrasound-guided femoral access supports demand for percutaneous-optimized designs across the region. Middle East and Africa, led by GCC investment in tertiary cardiac capacity, and South America, led by Brazil and Argentina, provide developing opportunities as hospital networks and medical tourism expand.
- Andocor n.v.
- AngioDynamics
- B. Braun
- Beckton Dickinson
- Braile Biomedica
- Cardinal Health
- Changzhou Kangxin Medical Instruments Co., Ltd.
- Cook Group
- Edward Lifesciences
- Eurosets S.r.l.
- Freelife Medical GmbH
- Getinge
- LivaNova
- Medical Materials, Inc.
- Medtronic
- Merit Medical Systems
- Nipro
- Teleflex
- Terumo
- Vygon
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising Cardiovascular and Critical-Care Procedure Volumes
- 4.2.2 Expansion of ECMO and Extracorporeal Circulation Capability
- 4.2.3 Shift Toward Minimally Invasive and Percutaneous Cannulation
- 4.2.4 Biocompatible, Kink-Resistant, and Low-Trauma Cannula Innovation
- 4.2.5 Aging Population and Higher Chronic Disease Burden
- 4.2.6 Cannula-Circuit Integration for Blood Conservation and Thrombus Removal
- 4.3 Market Restraints
- 4.3.1 Cannulation-Related Vascular Trauma and Thrombotic Risk
- 4.3.2 Shortage of Specialist Perfusion and Cannulation Personnel
- 4.3.3 Procedure Cost, Reimbursement, and Procurement Constraints
- 4.3.4 Fragmented Nomenclature and Inconsistent Product Classification
- 4.4 Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Suppliers
- 4.7.3 Bargaining Power of Buyers
- 4.7.4 Threat of Substitutes
- 4.7.5 Rivalry Among Existing Competitors
5 Market Size & Growth Forecasts (Value, USD)
- 5.1 By Product Type
- 5.1.1 Cardiac Cannula
- 5.1.2 Vascular Cannula
- 5.1.3 Venous Cannula
- 5.1.4 Arterial Cannula
- 5.1.5 Cardioplegia Cannula
- 5.1.6 Thrombus-Aspiration Cannula
- 5.1.7 Other Product Types
- 5.2 By Cannulation Site
- 5.2.1 Aortic and Arterial Sites
- 5.2.2 Femoral Vascular Sites
- 5.2.3 Jugular and Central Venous Sites
- 5.2.4 Right Atrium, Superior Vena Cava, and Inferior Vena Cava
- 5.2.5 Coronary Ostia and Coronary Sinus
- 5.2.6 Other Cannulation Sites
- 5.3 By Material
- 5.3.1 Polyvinyl Chloride
- 5.3.2 Polyurethane
- 5.3.3 Silicone
- 5.3.4 Stainless Steel
- 5.3.5 Other Materials
- 5.4 By Tip Design
- 5.4.1 Straight Tip
- 5.4.2 Angled Tip
- 5.4.3 Curved Tip
- 5.4.4 Beveled Tip
- 5.4.5 Funnel-Shaped Tip
- 5.4.6 Balloon and Self-Expanding Tip
- 5.5 By Application
- 5.5.1 Cardiopulmonary Bypass Surgery
- 5.5.2 Extracorporeal Membrane Oxygenation
- 5.5.3 Percutaneous Thrombus and Embolus Removal
- 5.5.4 Cardioplegia Delivery and Myocardial Protection
- 5.5.5 Vascular Surgery and Revascularization
- 5.5.6 Other Applications
- 5.6 By End User
- 5.6.1 Hospitals
- 5.6.2 Cardiac Centers
- 5.6.3 Ambulatory Surgical Centers
- 5.6.4 Specialty Clinics
- 5.6.5 Other End Users
- 5.7 By Geography
- 5.7.1 North America
- 5.7.1.1 United States
- 5.7.1.2 Canada
- 5.7.1.3 Mexico
- 5.7.2 Europe
- 5.7.2.1 Germany
- 5.7.2.2 United Kingdom
- 5.7.2.3 France
- 5.7.2.4 Italy
- 5.7.2.5 Spain
- 5.7.2.6 Rest of Europe
- 5.7.3 Asia-Pacific
- 5.7.3.1 China
- 5.7.3.2 Japan
- 5.7.3.3 India
- 5.7.3.4 Australia
- 5.7.3.5 South Korea
- 5.7.3.6 Rest of Asia-Pacific
- 5.7.4 Middle East and Africa
- 5.7.4.1 GCC
- 5.7.4.2 South Africa
- 5.7.4.3 Rest of Middle East and Africa
- 5.7.5 South America
- 5.7.5.1 Brazil
- 5.7.5.2 Argentina
- 5.7.5.3 Rest of South America
- 5.7.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Market Share Analysis
- 6.3 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)
- 6.3.1 Andocor n.v.
- 6.3.2 AngioDynamics, Inc.
- 6.3.3 B. Braun SE
- 6.3.4 Becton, Dickinson and Company
- 6.3.5 Braile Biomedica
- 6.3.6 Cardinal Health
- 6.3.7 Changzhou Kangxin Medical Instruments Co., Ltd.
- 6.3.8 Cook Medical LLC
- 6.3.9 Edwards Lifesciences Corporation
- 6.3.10 Eurosets S.r.l.
- 6.3.11 Freelife Medical GmbH
- 6.3.12 Getinge AB
- 6.3.13 LivaNova PLC
- 6.3.14 Medical Materials, Inc.
- 6.3.15 Medtronic
- 6.3.16 Merit Medical Systems, Inc.
- 6.3.17 Nipro Corporation
- 6.3.18 Teleflex Incorporated
- 6.3.19 Terumo Corporation
- 6.3.20 Vygon SA
7 Market Opportunities and Future Outlook
- 7.1 White-Space and Unmet-Need Assessment

