PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2119068

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2119068
Sustainable IT Hardware - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
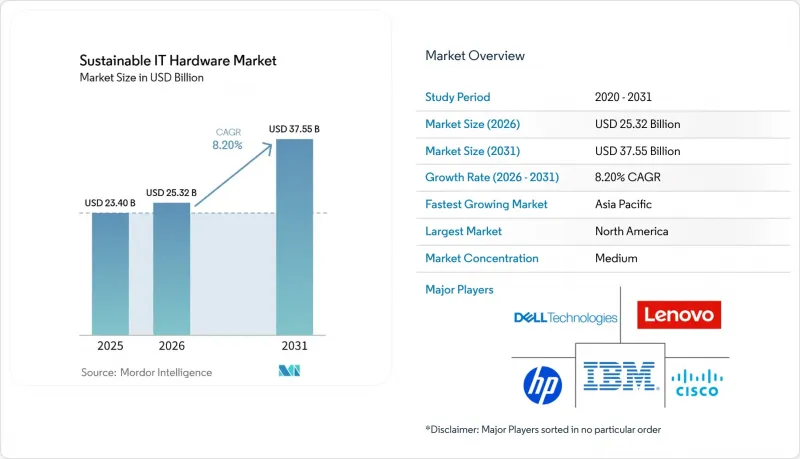
According to Mordor Intelligence, the sustainable IT hardware market size is expected to increase from USD 23.4 billion in 2025 to USD 25.32 billion in 2026 and reach USD 37.55 billion by 2031, growing at a CAGR of 8.20% over 2026-2031.
This report is Segmented by Product Type (Servers, Networking Equipment, Personal Computers and Workstations, and More), Component (Hardware, Software, and Services), End-User Industry (Data Centers, BFSI, Government and Public Sector, and More), Lifecycle Phase (Procurement and Manufacturing, Operation and Usage, and More), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global Sustainable IT Hardware Market Trends and Insights
Stringent E-Waste and Carbon Regulations Globally
Amendments to the European Union's WEEE Directive in 2024 lifted collection targets to 70% and introduced financial penalties for manufacturers that fail to fund take-back schemes, prompting design teams to prioritize easy-to-disassemble chassis and standardized fasteners. China's updated recovery rules require suppliers of enterprise-grade storage arrays to set up provincial collection networks by 2026, accelerating investment in reverse logistics hubs. California's Senate Bill 244 mandates 30% post-consumer recycled content in all IT equipment sold in the state by 2028, driving demand for certified recycled plastics and low-carbon aluminum.
Enterprise ESG and Net-Zero Procurement Mandates
A 2024 Carbon Disclosure Project survey found that 68% of Fortune 500 firms embedded lifecycle-emission thresholds into server and storage requests for proposals, up from 41% in 2022. Microsoft's 2025 Supplier Code of Conduct now requires product-level lifecycle assessments aligned with ISO 14040 and evidence of annual embodied-carbon reductions per teraflop or terabyte. Google disclosed that 82% of its 2024 server purchases met EPEAT Climate+ criteria, lifting industry demand for renewable-powered manufacturing and verified offset schemes.
High Upfront Cost of Sustainable Hardware and Cooling Retrofits
Liquid-cooled racks cost 40%-60% more to install than air-cooled equivalents because of coolant distribution units, leak sensors, and facility piping upgrades, extending payback periods beyond three years in regions where electricity prices remain below USD 0.08 per kWh. ENERGY STAR-certified storage arrays carry 12%-18% higher list prices driven by low-power NAND, advanced error correction, and verification fees, offsetting efficiency savings in low-utilization environments.
Other drivers and restraints analyzed in the detailed report include:
- Rapid Expansion of Hyperscale and Edge Data Centers
- Growing Demand for Energy-Efficient High-Density AI Servers
- Supply Chain Volatility for Low-Carbon Components
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Servers accounted for 37.6% of 2025 revenue and are forecast to grow at a 10.9% CAGR, the highest among categories, as hyperscale clouds adopt liquid-cooled chassis optimized for generative-AI inference workloads. This uptake supports the sustainable IT hardware market size for servers, enabling operators to double compute density and defer new building permits. Chiplet-based x86 and ARM processors integrate silicon-carbide power modules that cut conversion losses up to 25%, aligning with corporate net-zero roadmaps. Storage vendors pivot to NVMe-over-Fabrics and computational drives like Seagate's Exos CORVAULT, which extends mean-time-to-data-loss past 3.5 million hours while lowering energy per I/O cycle. Networking equipment benefits from 800 Gbps switch silicon that delivers 35% better watts per gigabit, sustaining sustainable IT hardware market share gains as AI cluster fabrics expand.
Peripherals, PCs, and power equipment are experiencing steady growth, driven by advancements in technologies such as USB Power Delivery 3.1, sleep-mode sensors, and predictive UPS analytics. These innovations are essential to meet the stricter ENERGY STAR Version 9.0 thresholds, which emphasize energy efficiency and sustainability. For instance, Vertiv's machine-learning UPS algorithms have proven effective in delaying battery replacements by up to 20% over a ten-year period. This not only reduces operational costs but also significantly curtails lifecycle emissions, contributing to environmental sustainability. Furthermore, these advancements collectively support circular procurement practices by ensuring that commodity metals are preserved and reintroduced into manufacturing processes, thereby promoting a more sustainable and resource-efficient production cycle.
Hardware delivered 61.9% of sustainable IT hardware market revenue in 2025, though services are expanding at a 9.4% CAGR as enterprises outsource carbon accounting, asset tracking and refurbishment. This dynamic underpins a rising sustainable IT hardware market share for managed services, especially among global banks and retailers that lack in-house disposal capacity. Schneider Electric's EcoStruxure IT shifted workloads to off-peak windows, cutting one Fortune 100 firm's data-center power by 14% in 2024. HPE GreenLake Sustainability Services publishes quarterly reports on avoided emissions and water savings, aligning with Scope 3 requirements for purchased goods. Logistics specialists such as Iron Mountain recovered 18,500 metric tons of steel and precious metals from 2.3 million IT units in 2024, reinforcing closed-loop supply chains.
Software spending mirrors hardware refresh cycles, with AI workload-placement engines and digital twins enabling operators to model thermodynamics and electricity grids in real time. These advanced technologies allow businesses to optimize energy consumption, reduce operational inefficiencies, and enhance overall system performance. By leveraging AI-driven insights, operators can predict and mitigate potential issues, ensuring seamless operations and minimizing downtime. Additionally, these orchestration layers reduce stranded capacity, enabling more efficient resource utilization. This trend drives incremental demand for subscription licenses that bundle essential features such as security, energy management, and lifecycle dashboards, offering a comprehensive solution for modern operational challenges.
Complete Report Scope:
- By Product Type
- Servers
- Storage Devices
- Networking Equipment
- Personal Computers and Workstations
- Peripherals and Accessories
- UPS and Power Distribution Units
- By Component
- Hardware
- Software
- Services
- By End-User Industry
- Data Centers
- Large Enterprises
- Small and Medium Enterprises
- Government and Public Sector
- Healthcare
- BFSI
- Telecom and IT
- Other End-User Industries
- By Lifecycle Phase
- Procurement and Manufacturing
- Operation and Usage
- Maintenance and Upgrades
- End-of-Life and Recycling
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Russia
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- South Korea
- Rest of Asia Pacific
- Middle East
- Saudi Arabia
- United Arab Emirates
- Rest of Middle East
- Africa
- South Africa
- Nigeria
- Rest of Africa
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
North America captured 53.8% of 2025 revenue, powered by hyperscale clouds, stringent ENERGY STAR standards, and new U.S. Securities and Exchange Commission climate-disclosure rules that force large filers to audit Scope 3 emissions from IT assets. Federal agencies and 29 states require EPEAT-Silver or higher ratings, pushing vendors to publish product-level carbon footprints. Canada's Greening Government Strategy mandates net-zero operations by 2030, further boosting procurement of high-efficiency servers and laptops.
Asia-Pacific is the fastest-growing region at a 12.2% CAGR through 2031. India's INR 170 billion (USD 2.04 billion) incentive for domestic server manufacturing and renewable-powered factories strengthens local supply chains. Japan's Green Transformation League funds pilots to recycle rare-earth magnets, while South Korea's K-Circular Economy Act sets mandatory recycled-content thresholds and tracks devices from sale to dismantling. Hyperscalers in Singapore and Indonesia deploy liquid-cooled AI clusters to manage tropical heat without evaporative cooling, sustaining sustainable IT hardware market share across Southeast Asia. Europe ranks second, boosted by the Ecodesign for Sustainable Products Regulation and grants to retrofit data centers with waste-heat recovery.
Germany budgets EUR 500 million (USD 560 million) for facilities that supply district-heating networks, driving demand for liquid-cooled racks with 60°C outlet temperatures that enable efficient heat reuse. The United Kingdom's draft rules compel data centers above 500 kilowatts to publish monthly power-usage and water-usage metrics, accelerating metering upgrades. The Middle East builds AI-ready campuses in Saudi Arabia and the UAE as part of diversification agendas, with anchor tenants demanding renewable-energy purchase agreements and digital passports. Africa's growth centers on South Africa, where Teraco's 20-megawatt solar data center in Johannesburg sets a regional template for sustainable compute in markets with intermittent grids.
- Lenovo Group Limited
- HP Inc.
- Dell Technologies Inc.
- International Business Machines Corporation
- Cisco Systems Inc.
- Huawei Technologies Co., Ltd.
- Inspur Electronic Information Industry Co., Ltd.
- Super Micro Computer, Inc.
- Fujitsu Limited
- NEC Corporation
- Hewlett Packard Enterprise Company
- Schneider Electric SE
- Vertiv Holdings Co.
- Eaton Corporation plc
- Delta Electronics, Inc.
- Seagate Technology Holdings plc
- Western Digital Corporation
- Pure Storage, Inc.
- Advanced Micro Devices, Inc.
- NVIDIA Corporation
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Stringent E-Waste and Carbon Regulations Globally
- 4.2.2 Enterprise ESG and Net-Zero Procurement Mandates
- 4.2.3 Rapid Expansion of Hyperscale and Edge Data Centers
- 4.2.4 Growing Demand for Energy-Efficient High-Density AI Servers
- 4.2.5 Emergence of Circular Economy IT-as-a-Service Models
- 4.2.6 Advancements in Low-Voltage Silicon Carbide and GaN Power Components
- 4.3 Market Restraints
- 4.3.1 High Upfront Cost of Sustainable Hardware and Cooling Retrofits
- 4.3.2 Supply Chain Volatility for Low-Carbon Components
- 4.3.3 Lack of Standardized Sustainability Metrics Across Regions
- 4.3.4 Rising Water Stress Impacting Liquid Cooling Adoption in Emerging Asia
- 4.4 Industry Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Impact of Macroeconomic Factors on the Market
- 4.8 Porter's Five Forces Analysis
- 4.8.1 Threat of New Entrants
- 4.8.2 Bargaining Power of Suppliers
- 4.8.3 Bargaining Power of Buyers
- 4.8.4 Threat of Substitutes
- 4.8.5 Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Product Type
- 5.1.1 Servers
- 5.1.2 Storage Devices
- 5.1.3 Networking Equipment
- 5.1.4 Personal Computers and Workstations
- 5.1.5 Peripherals and Accessories
- 5.1.6 UPS and Power Distribution Units
- 5.2 By Component
- 5.2.1 Hardware
- 5.2.2 Software
- 5.2.3 Services
- 5.3 By End-User Industry
- 5.3.1 Data Centers
- 5.3.2 Large Enterprises
- 5.3.3 Small and Medium Enterprises
- 5.3.4 Government and Public Sector
- 5.3.5 Healthcare
- 5.3.6 BFSI
- 5.3.7 Telecom and IT
- 5.3.8 Other End-User Industries
- 5.4 By Lifecycle Phase
- 5.4.1 Procurement and Manufacturing
- 5.4.2 Operation and Usage
- 5.4.3 Maintenance and Upgrades
- 5.4.4 End-of-Life and Recycling
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 Europe
- 5.5.2.1 Germany
- 5.5.2.2 United Kingdom
- 5.5.2.3 France
- 5.5.2.4 Russia
- 5.5.2.5 Rest of Europe
- 5.5.3 Asia-Pacific
- 5.5.3.1 China
- 5.5.3.2 Japan
- 5.5.3.3 India
- 5.5.3.4 South Korea
- 5.5.3.5 Rest of Asia Pacific
- 5.5.4 Middle East
- 5.5.4.1 Saudi Arabia
- 5.5.4.2 United Arab Emirates
- 5.5.4.3 Rest of Middle East
- 5.5.5 Africa
- 5.5.5.1 South Africa
- 5.5.5.2 Nigeria
- 5.5.5.3 Rest of Africa
- 5.5.6 South America
- 5.5.6.1 Brazil
- 5.5.6.2 Argentina
- 5.5.6.3 Rest of South America
- 5.5.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)
- 6.4.1 Lenovo Group Limited
- 6.4.2 HP Inc.
- 6.4.3 Dell Technologies Inc.
- 6.4.4 International Business Machines Corporation
- 6.4.5 Cisco Systems Inc.
- 6.4.6 Huawei Technologies Co., Ltd.
- 6.4.7 Inspur Electronic Information Industry Co., Ltd.
- 6.4.8 Super Micro Computer, Inc.
- 6.4.9 Fujitsu Limited
- 6.4.10 NEC Corporation
- 6.4.11 Hewlett Packard Enterprise Company
- 6.4.12 Schneider Electric SE
- 6.4.13 Vertiv Holdings Co.
- 6.4.14 Eaton Corporation plc
- 6.4.15 Delta Electronics, Inc.
- 6.4.16 Seagate Technology Holdings plc
- 6.4.17 Western Digital Corporation
- 6.4.18 Pure Storage, Inc.
- 6.4.19 Advanced Micro Devices, Inc.
- 6.4.20 NVIDIA Corporation
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment

