PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2187772

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2187772
India IT Hardware - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2027 - 2032)
According to Mordor Intelligence, the India IT hardware market size is expected to increase from USD 22.61 billion in 2026 to USD 24.14 billion in 2027 and reach USD 33.92 billion by 2032, growing at a CAGR of 7.04% over 2027-2032.
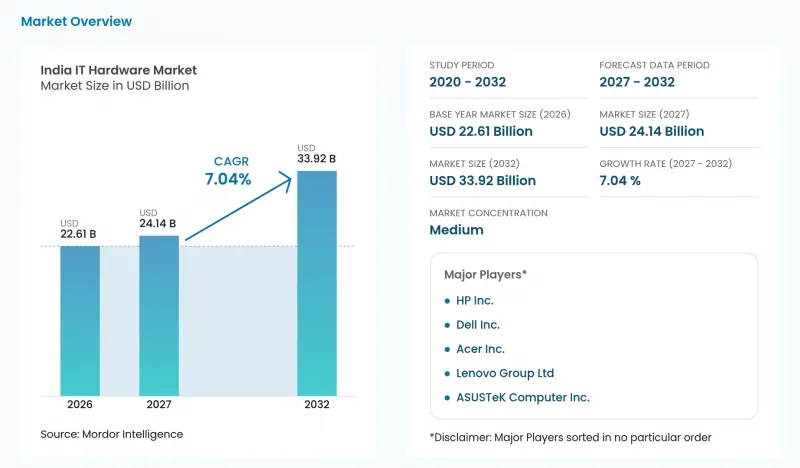
This report is segmented by Product Type (PCs and Workstations, Servers, and more), Application (Consumer and Enterprise), End-user Industry (IT and Telecom, BFSI, and more), and Geography (South India, West and Central India, and more). The market forecasts are provided in terms of value (USD), based on availability.
India IT Hardware Market Trends and Insights
Rapid growth in laptop demand under hybrid-work policies
Hybrid schedules make portable computing commercially relevant because the same device can serve work split across home and office. Infosys reported that approximately 79% of its global workforce operated in a hybrid manner in fiscal 2026. In Q2 2026, notebook shipments in India rose 13% year over year to 3 million units. A portable endpoint lets suppliers address both parts of a hybrid schedule through the same device category, connecting the work arrangement to an identifiable hardware use case. Omdia attributed part of Q2 PC growth to purchases brought forward ahead of expected price increases, so vendors cannot extrapolate sustained hybrid-work demand from that quarter's shipment gain.
Elevated need for high-performance computing in AI workloads
AI workloads create a hardware opportunity through shared computing infrastructure, extending demand beyond organizations that can own dedicated equipment. The IndiaAI Mission expanded shared compute capacity to more than 45,000 graphics processing units, or GPUs, by June 2026. By August 2026, 237 projects had accessed 9.32 million GPU hours of subsidized AI computing through the mission. Together, the capacity and recorded access show how a common infrastructure pool can serve many projects without requiring each to acquire physical GPUs. For server suppliers, this concentrates the addressable equipment opportunity around shared-compute providers, while project participation gives that infrastructure a concrete application base.
Escalating e-waste compliance costs
E-waste obligations create financial exposure for producers beyond the initial sale of equipment. Approved guidelines from the Central Pollution Control Board, or CPCB, require producers that miss extended producer responsibility, or EPR, targets to bear compensation based on average e-waste collection, transportation and recycling costs. The 2024 amendment directs CPCB to fix EPR certificate exchange price limits at 30% to 100% of compensation for unfulfilled obligations. For a producer buying certificates to close a shortfall, the prescribed floor sets a minimum cost of 30% of the corresponding compensation liability. For affected producers, that exposure can reduce room for price concessions, leaving a cost burden when sales opportunities require more competitive quotations.
Other drivers and restraints analyzed in the detailed report include:
- Public-sector digitization push via Digital India and NIC projects
- Make-in-India incentives for local PC/server manufacturing (PLI 2.0)
- Semiconductor supply-chain volatility
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
PCs and workstations accounted for a 42.16% share of the India IT hardware market size in 2026. India's traditional PC market, covering desktops, notebooks and workstations, shipped 4.4 million units in Q1 2026, up 31.1% year over year, according to IDC. In July 2025, Syrma SGS reported making small quantities of MSI laptops for India, with global supply under negotiation. In June 2026, MSI said most of its India-market laptops were manufactured locally through Syrma SGS and other contract manufacturing partners. An assembler can participate in a brand's Indian supply program alongside other manufacturers, so local capability need not depend on export commitments.
Enterprise storage devices are the fastest-growing product segment, with a forecast CAGR of 8.3% over 2027-2032. On August 1, 2025, Esconet Technologies Limited disclosed a contract from National Informatics Centre Services Inc. to supply, install and commission a data storage system for the National Data Centre operated by NIC. The agreed package included hardware, software and associated services, with execution following the purchase-order timeline. Bundling the physical system with installation makes integration capability part of the supplier's commercial offering, alongside the equipment itself. The storage opportunity therefore favors providers able to take responsibility for deployment, linking device demand to the ability to serve an institutional data-center requirement.
Complete Report Scope:
- By Product Type
- PCs and Workstations
- Enterprise Networking Hardware
- Enterprise Storage Devices
- Servers
- Other Hardware (Printers and Copiers)
- By Application
- Consumer
- Enterprise
- SMEs
- Large Enterprises
- By End-user Industry
- BFSI
- Retail
- IT and Telecom
- Other End-user Industries
- By Geography
- North India
- East India
- West and Central India
- South India
List of Companies Covered in this Report:
- Dell Inc.
- Lenovo Group Ltd
- ASUSTeK Computer Inc.
- HP Inc.
- Acer Inc.
- IBM Corporation
- Apple Inc.
- Samsung Electronics Co. Ltd.
- NetApp Inc.
- Hitachi Ltd.
- Cisco Systems Inc.
- Juniper Networks Inc.
- Arista Networks Inc.
- Hewlett Packard Enterprise (HPE) Inc.
- Wistron India Inc.
- Foxconn India Inc.
- Super Micro Computer Inc.
- Dell EMC Indian Ops
- Supertron Electronics Private Limited
- RP Tech India
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rapid growth in laptop demand under hybrid-work policies
- 4.2.2 Elevated need for high-performance computing in AI workloads
- 4.2.3 Public-sector digitization push via Digital India and NIC projects
- 4.2.4 Make-in-India incentives for local PC/server manufacturing (PLI 2.0)
- 4.2.5 Rising demand for edge data-center servers in Tier-2 cities (under-reported)
- 4.2.6 Corporate ESG mandates favor energy-efficient hardware (under-reported)
- 4.3 Market Restraints
- 4.3.1 Escalating e-waste compliance costs
- 4.3.2 Semiconductor supply-chain volatility
- 4.3.3 Persistent gray-market imports in peripherals (under-reported)
- 4.3.4 Slow enterprise refresh cycles in public-sector tenders (under-reported)
- 4.4 Industry Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Suppliers
- 4.7.3 Bargaining Power of Buyers
- 4.7.4 Threat of Substitutes
- 4.7.5 Competitive Rivalry
- 4.8 Assessment of Macro-economic Trends on the Market
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Product Type
- 5.1.1 PCs and Workstations
- 5.1.2 Enterprise Networking Hardware
- 5.1.3 Enterprise Storage Devices
- 5.1.4 Servers
- 5.1.5 Other Hardware (Printers and Copiers)
- 5.2 By Application
- 5.2.1 Consumer
- 5.2.2 Enterprise
- 5.2.2.1 SMEs
- 5.2.2.2 Large Enterprises
- 5.3 By End-user Industry
- 5.3.1 BFSI
- 5.3.2 Retail
- 5.3.3 IT and Telecom
- 5.3.4 Other End-user Industries
- 5.4 By Geography
- 5.4.1 North India
- 5.4.2 East India
- 5.4.3 West and Central India
- 5.4.4 South India
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 Dell Inc.
- 6.4.2 Lenovo Group Ltd
- 6.4.3 ASUSTeK Computer Inc.
- 6.4.4 HP Inc.
- 6.4.5 Acer Inc.
- 6.4.6 IBM Corporation
- 6.4.7 Apple Inc.
- 6.4.8 Samsung Electronics Co. Ltd.
- 6.4.9 NetApp Inc.
- 6.4.10 Hitachi Ltd.
- 6.4.11 Cisco Systems Inc.
- 6.4.12 Juniper Networks Inc.
- 6.4.13 Arista Networks Inc.
- 6.4.14 Hewlett Packard Enterprise (HPE) Inc.
- 6.4.15 Wistron India Inc.
- 6.4.16 Foxconn India Inc.
- 6.4.17 Super Micro Computer Inc.
- 6.4.18 Dell EMC Indian Ops
- 6.4.19 Supertron Electronics Private Limited
- 6.4.20 RP Tech India
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment

