PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2119142

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2119142
Myocardial Ischemia - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
According to Mordor Intelligence, the myocardial ischemia market is projected to expand from USD 4.94 billion in 2025 and USD 5.13 billion in 2026 to USD 6.48 billion by 2031, registering a CAGR of 4.76% between 2026 and 2031.
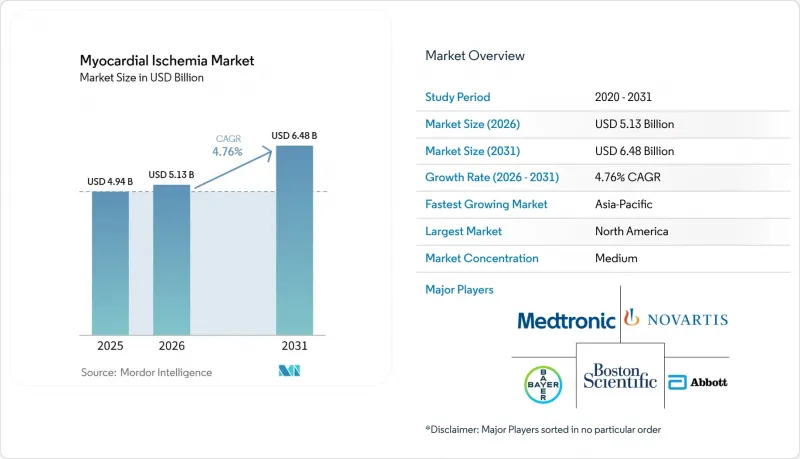
This report is Segmented by Type (Symptomatic Myocardial Ischemia, Asymptomatic Myocardial Ischemia), Management (Diagnosis, Treatment), End-User (Hospitals and Clinics, Cardiac Specialty Clinics, and More), and Geography (North America, Europe, Asia-Pacific, Middle East and Africa, South America). The Market Forecasts are Provided in Terms of Value (USD).
Global Myocardial Ischemia Market Trends and Insights
Rising Global Burden of Cardiovascular Disease
The myocardial ischemia market continues to draw support from the persistent global burden of ischemic heart disease. A 2025 modeling study published in JACC projected that total cardiovascular disease deaths will rise from 20.5 million in 2025 to 35.6 million by 2050. A separate 2025 study in BMC Cardiovascular Disorders also confirmed that ischemic heart disease remains the leading cause of disability adjusted life years worldwide. This keeps the myocardial ischemia market tied to structural patient need rather than short-cycle fluctuations in procedure volumes. Aging populations, higher body mass index, and persistent cardiometabolic risk are widening the treatment pool across both developed and developing health systems. That demand supports steady use of imaging, medication, and revascularization across the myocardial ischemia market.
Expanding Early Diagnosis and Screening Adoption
The myocardial ischemia market is also being lifted by the wider acceptance of earlier diagnosis in at-risk patients. The 2025 ACC, AHA, ACEP, NAEMSP, and SCAI guideline reinforced individualized risk stratification and precision diagnostic testing in acute coronary syndrome management. That clinical direction supports higher use of ECG, echocardiography, stress testing, coronary CT, and functional imaging in routine care pathways. The economic case for this shift is also improving, as the PRECISE randomized trial showed that a precision diagnostic pathway for stable chest pain reduced mean diagnostic costs at 45 days by USD 249 per patient versus usual testing. This makes wider screening easier to defend in value-based care systems where cost control matters as much as clinical yield. It also strengthens the diagnostic side of the myocardial ischemia market because more patients are being identified before severe events occur.
High Cost of Diagnostic and Interventional Care Pathways
The myocardial ischemia market still faces a clear affordability barrier in diagnosis and intervention. Boston Scientific's 2025 reimbursement guide showed Medicare national average payments for PCI with an intraluminal device ranging from USD 12,911 to USD 30,397, depending on complication status. Limited access to cath labs and advanced imaging in lower resource settings adds another layer of delay, especially outside large urban hospitals. The result is not a lack of need, but slower penetration of the myocardial ischemia market across parts of Asia-Pacific, the Middle East, Africa, and South America.
Other drivers and restraints analyzed in the detailed report include:
- Shift Toward Minimally Invasive Revascularization and Precision Imaging
- Wearable Monitoring and Remote Cardiac Triage Adoption
- Adverse Events and Long-Term Medication Non-Adherence
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Symptomatic myocardial ischemia held 52.22% of the myocardial ischemia market share in 2025, reflecting the large volume of patients who entered care through chest pain, stress testing, angiography, and standard intervention pathways. The asymptomatic segment, however, is forecasted to grow at a 5.24% CAGR through 2031, which makes it the fastest-moving part of the myocardial ischemia market by type. The shift is being driven by wider screening in high-risk groups such as people with diabetes and chronic kidney disease, where silent disease is common.
Wearable monitoring is now the main structural force behind this change in the myocardial ischemia market. Guidance remains selective rather than universal, which keeps the focus on the highest risk groups and reduces the chance of broad overtesting. A 2024 review in Biomedicines showed that silent myocardial ischemia continues to pose a meaningful clinical challenge, especially when symptom presentation is weak or absent. That balance keeps the type mix of the myocardial ischemia market moving toward more targeted detection rather than broad population screening.
Complete Report Scope:
- By Type
- Symptomatic Myocardial Ischemia
- Asymptomatic Myocardial Ischemia
- By Management
- Diagnosis
- Electrocardiogram
- Echocardiography
- Stress Testing
- Coronary Angiography
- CT and MRI Imaging
- Treatment
- Medication Therapy
- Percutaneous Coronary Intervention
- Coronary Artery Bypass Grafting
- Lifestyle Management and Rehabilitation
- Diagnosis
- By End-User
- Hospitals and Clinics
- Cardiac Specialty Clinics
- Diagnostic Centers
- Ambulatory Surgical Centers
- Research and Academic Institutes
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- Australia
- South Korea
- Rest of Asia-Pacific
- Middle East and Africa
- GCC
- South Africa
- Rest of Middle East and Africa
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
North America held 47.35% of the myocardial ischemia market share in 2025, which kept it as the clear regional leader. The region benefits from mature cath lab infrastructure, broad reimbursement support, and high adoption of advanced imaging platforms. The United States remains the core demand center because guideline-driven acute coronary syndrome care creates stable diagnostic and treatment volume across hospitals and interventional programs. Canada and Mexico add supplementary volume, but North America's lead still rests mainly on the scale and reimbursement depth of the U.S. system.
Europe remains the second largest regional block in the myocardial ischemia market, with Germany, the United Kingdom, France, Italy, and Spain supporting most of the continent's procedural and pharmacotherapy demand. Germany stands out because its digital health reimbursement pathway creates a clearer route for longer-term cardiovascular management tools in routine care. European device and drug access is also shaped by established regulatory systems, including EMA review processes and the EU MDR framework for cardiac devices. Eastern European countries offer a medium-term opening within the myocardial ischemia market because disease burden remains high while interventional capacity still trails Western Europe.
Asia-Pacific shows the fastest projected myocardial ischemia market expansion by region, at a projected 7.13% CAGR from 2026 to 2031. China and India are leading the regional volume build-out as access to cardiac care widens across larger patient pools. Japan adds a strong innovation base, while South Korea and Australia contribute advanced imaging and interventional adoption. Middle East and Africa, along with South America, remain smaller in total size, but the myocardial ischemia market is still growing there as cardiac capacity expands in major urban centers even though limited cath lab and imaging access continues to slow penetration in rural and lower resource settings.
- Abbott Laboratories
- Abbvie
- Amgen
- B. Braun
- Bayer
- Boehringer Ingelheim
- Boston Scientific
- Canon
- Daiichi Sankyo
- GE Healthcare
- Gilead Sciences
- Medtronic
- Merck
- Novartis
- Otsuka
- Pfizer
- Sanofi
- Siemens Healthineers
- Terumo
- Teva Pharmaceutical Industries
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising Global Burden of Cardiovascular Disease
- 4.2.2 Expanding Early Diagnosis and Screening Adoption
- 4.2.3 Shift Toward Minimally Invasive Revascularization and Precision Imaging
- 4.2.4 Wearable Monitoring and Remote Cardiac Triage Adoption
- 4.2.5 Underdiagnosis of Silent Ischemia in High-Risk Patients
- 4.3 Market Restraints
- 4.3.1 High Cost of Diagnostic and Interventional Care Pathways
- 4.3.2 Adverse Events and Long-Term Medication Non-Adherence
- 4.3.3 Limited Access to Cath Labs and Advanced Imaging in Low-Resource Settings
- 4.4 Supply/Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Suppliers
- 4.7.3 Bargaining Power of Buyers
- 4.7.4 Threat of Substitutes
- 4.7.5 Competitive Rivalry
5 Market Size & Growth Forecasts (Value, USD)
- 5.1 By Type
- 5.1.1 Symptomatic Myocardial Ischemia
- 5.1.2 Asymptomatic Myocardial Ischemia
- 5.2 By Management
- 5.2.1 Diagnosis
- 5.2.1.1 Electrocardiogram
- 5.2.1.2 Echocardiography
- 5.2.1.3 Stress Testing
- 5.2.1.4 Coronary Angiography
- 5.2.1.5 CT and MRI Imaging
- 5.2.2 Treatment
- 5.2.2.1 Medication Therapy
- 5.2.2.2 Percutaneous Coronary Intervention
- 5.2.2.3 Coronary Artery Bypass Grafting
- 5.2.2.4 Lifestyle Management and Rehabilitation
- 5.2.1 Diagnosis
- 5.3 By End-User
- 5.3.1 Hospitals and Clinics
- 5.3.2 Cardiac Specialty Clinics
- 5.3.3 Diagnostic Centers
- 5.3.4 Ambulatory Surgical Centers
- 5.3.5 Research and Academic Institutes
- 5.4 By Geography
- 5.4.1 North America
- 5.4.1.1 United States
- 5.4.1.2 Canada
- 5.4.1.3 Mexico
- 5.4.2 Europe
- 5.4.2.1 Germany
- 5.4.2.2 United Kingdom
- 5.4.2.3 France
- 5.4.2.4 Italy
- 5.4.2.5 Spain
- 5.4.2.6 Rest of Europe
- 5.4.3 Asia-Pacific
- 5.4.3.1 China
- 5.4.3.2 Japan
- 5.4.3.3 India
- 5.4.3.4 Australia
- 5.4.3.5 South Korea
- 5.4.3.6 Rest of Asia-Pacific
- 5.4.4 Middle East and Africa
- 5.4.4.1 GCC
- 5.4.4.2 South Africa
- 5.4.4.3 Rest of Middle East and Africa
- 5.4.5 South America
- 5.4.5.1 Brazil
- 5.4.5.2 Argentina
- 5.4.5.3 Rest of South America
- 5.4.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Market Share Analysis
- 6.3 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products & Services, Recent Developments)
- 6.3.1 Abbott Laboratories
- 6.3.2 AbbVie Inc.
- 6.3.3 Amgen Inc.
- 6.3.4 B. Braun Melsungen AG
- 6.3.5 Bayer AG
- 6.3.6 Boehringer Ingelheim International GmbH
- 6.3.7 Boston Scientific Corporation
- 6.3.8 Canon Medical Systems Corporation
- 6.3.9 Daiichi Sankyo Company, Limited
- 6.3.10 GE HealthCare
- 6.3.11 Gilead Sciences, Inc.
- 6.3.12 Medtronic plc
- 6.3.13 Merck and Co., Inc.
- 6.3.14 Novartis AG
- 6.3.15 Otsuka Holdings Co., Ltd.
- 6.3.16 Pfizer Inc.
- 6.3.17 Sanofi S.A.
- 6.3.18 Siemens Healthineers AG
- 6.3.19 Terumo Corporation
- 6.3.20 Teva Pharmaceutical Industries Ltd.
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-need Assessment

