PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2119161

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2119161
Calcium Chloride - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
According to Mordor Intelligence, the calcium chloride market was valued at USD 2.22 billion in 2025 and is estimated to grow from USD 2.32 billion in 2026 to reach USD 2.98 billion by 2031, at a CAGR of 5.13% during the forecast period (2026-2031).
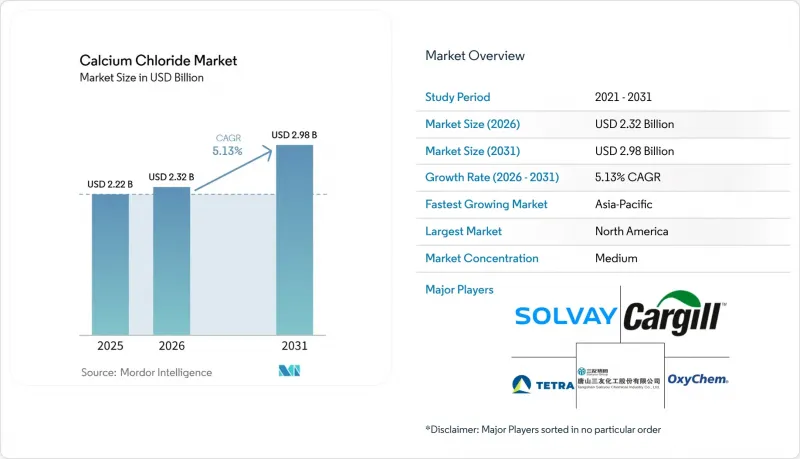
This report is Segmented by Grade (Industrial Grade, Food Grade, and Pharmaceutical Grade), Product Type (Flakes, Pellets and Prills, and More), Application (De-Icing and Dust Control, Food and Beverage Processing, and More), End-Use Industry (Municipal and Public Infrastructure, and More), and Geography (Asia-Pacific, North America, and More). The Market Forecasts are Provided in Terms of Value (USD).
Global Calcium Chloride Market Trends and Insights
Growing Use of Calcium Chloride in Oil and Gas Drilling and Well Completion Operations
The calcium chloride market benefits from demand for clear brines used in drilling, completion, and workover work across conventional, offshore, and unconventional wells. The U.S. Energy Information Administration reported that U.S. crude oil and natural gas rotary rigs averaged 546 in January 2026, supporting completion-fluid demand in the Permian Basin and Appalachia. TETRA Technologies reported USD 631.0 million in 2025 revenue and USD 113.6 million in adjusted Earnings Before Interest, Taxes, Depreciation, and Amortization (EBITDA) for its Completion Fluids & Products division, with revenue up 5% and adjusted EBITDA up 14% from 2024. The reported performance reflects continued demand from deepwater and unconventional completions, where fluid quality and supply continuity are important. Offshore activity in the Gulf of Mexico, together with activity in India and China, broadens the demand base beyond North America. Completion schedules remain important for inventory planning because they can lag changes in reported drilling activity.
Increasing Preference for High-Performance De-Icing and Dust Control Solutions
The calcium chloride market continues to depend on winter road treatment, especially in the Great Lakes region, Canada, and Northern Europe. The U.S. Environmental Protection Agency identifies road-treatment salt as a contributor to freshwater salinization and provides salt-management information for reducing related risks. This policy focus favors documented products that can deliver consistent performance while allowing agencies to better control applications. Municipal buyers are balancing road-safety requirements with efforts to reduce chloride loading in sensitive watersheds and nearby water bodies. The same products support dust control on unpaved mining roads and construction sites where operators must manage airborne particles and surface conditions. This gives suppliers a reason to offer application guidance, liquid systems, storage support, and formulation documentation rather than only dry material.
High Corrosion Risks and Associated Maintenance Costs in Infrastructure and Transportation Assets
Corrosion risk remains a constraint on the calcium chloride market in road, bridge, airport, parking, pipeline, and vehicle applications. The Transportation Research Board documented the costs associated with chloride-based de-icers and their effects on infrastructure. A 2024 study examined repair-cost uncertainty for reinforced concrete exposed to chloride ingress. These costs make procurement teams more attentive to corrosion performance, especially for bridge decks, runways, parking structures, and public assets. Suppliers can respond with inhibited formulations and clearer product documentation, but these measures add cost and may narrow the difference with alternatives. Alternative de-icers can gain attention where municipalities give greater weight to asset protection, runoff concerns, and long-term maintenance expenses.
Other drivers and restraints analyzed in the detailed report include:
- Expanding Application of Calcium Chloride in Construction for Concrete Acceleration and Soil Stabilization
- Growing Demand from the Food Processing Industry as a Firming, Preserving, and Coagulating Agent
- Storage, Handling, and Packaging Challenges Due to the Hygroscopic Nature of Calcium Chloride
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Industrial grade held 62.71% of the calcium chloride market share in 2025, reflecting its wide use in de-icing, dust control, oilfield brines, and construction. These uses generally prioritize functional performance, large available volume, and practical concentration tolerances over pharmaceutical-level purity. Pharmaceutical grade is forecast to grow at a 5.82% CAGR through 2031, supported by medical applications that need pharmacopoeia specifications, sterile manufacturing conditions, and controlled handling. Food grade and pharmaceutical grade are important to suppliers seeking higher-value sales and a less seasonal demand base.
The U.S. Food and Drug Administration framework under 21 CFR §184.1193 and the Codex E509 listing give food processors a defined basis for calcium chloride use. This supports demand from dairy, brewing, canned vegetables, tofu, and related processing activities. Solvay launched expanded food grade and pharmaceutical grade calcium chloride from Rheinberg, Germany, in February 2025, with EN 233 and British Pharmacopoeia (BP)/United States Pharmacopeia (USP)-certified calcium chloride dihydrate for European dairy and pharmaceutical customers. Tokuyama produces calcium chloride as a soda-ash co-product at Shunan City in Japan and supplies industrial and food-related uses through its domestic network.
Flakes held 43.86% of the calcium chloride market share in 2025 because they are widely used in de-icing, construction, and dust control. Their rapid dissolution, familiar handling profile, and broad availability make them suitable for high-volume applications. Pellets and Prills are projected to grow at a 5.24% CAGR through 2031 because oilfield, food-processing, and pharmaceutical users need controlled, lower-dust products. Product selection increasingly depends on dosing precision, storage needs, transportation conditions, and the operating environment at the point of use.
Nedmag supplies calcium chloride in liquid and prill forms for industrial and food-related applications. Prills can support operations where a consistent form and predictable dissolution are important. Liquid calcium chloride is used for anti-icing before snowfall and can reduce dry residue on road surfaces. Powder serves narrower uses that need fine particle distribution and controlled handling.
Complete Report Scope:
- By Grade
- Industrial Grade
- Food Grade
- Pharmaceutical Grade
- By Product Type
- Flakes
- Pellets and Prills
- Liquid
- Powder
- By Application
- De-Icing and Dust Control
- Construction and Concrete Acceleration
- Food and Beverage Processing
- Oil and Gas (Drilling and Completion Fluids)
- Water Treatment
- Chemical Processing and Refrigeration
- By End-Use Industry
- Municipal and Public Infrastructure
- Construction
- Food and Beverage
- Oil and Gas
- Chemical
- By Geography
- Asia-Pacific
- China
- India
- Japan
- South Korea
- Rest of Asia-Pacific
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Russia
- Rest of Europe
- South America
- Brazil
- Argentina
- Rest of South America
- Middle-East and Africa
- Saudi Arabia
- South Africa
- Rest of Middle-East and Africa
- Asia-Pacific
Geography Analysis
North America held 36.22% of the calcium chloride market share in 2025, supported by municipal de-icing demand and oilfield activity. The Great Lakes, the Northeastern United States, the Canadian Prairies, Texas, New Mexico, and Alberta are important demand areas because they combine cold-weather road needs with active energy operations. Natural brine resources in Michigan and California support local supply and cost advantages for producers with access to them. TETRA's reported 2025 completion-fluid performance reflects demand beyond the winter de-icing season. U.S. Environmental Protection Agency salt-management resources also influence municipal purchasing by focusing attention on freshwater impacts, product performance, and chloride-loading outcomes.
Asia-Pacific is projected to grow at a 6.11% CAGR through 2031. Construction in China and India supports concrete acceleration and soil stabilization, particularly where project schedules face cold-weather or difficult-soil conditions. Food grade demand in Japan and South Korea adds a separate base, while Southeast Asian healthcare and injectable-drug manufacturing support pharmaceutical grade requirements. Chinese producers use soda-ash co-production to supply cost-competitive industrial material for domestic construction users and export markets. India offers demand across highways, concrete work, dairy processing, and other food applications, which gives suppliers several routes to grow.
Europe's demand is led by Germany, the United Kingdom, and Nordic countries, serving as key centers for de-icing and high-purity demand. Solvay's February 2025 Rheinberg product launch supports European dairy and pharmaceutical customers with certified calcium chloride dihydrate. Eastern European road expansion can support further de-icing use in locations with limited distribution coverage. Semiconductor manufacturing in Germany and Central Europe creates demand for specialized industrial processing materials. In South America, Brazil and Argentina use calcium chloride for mining dust suppression and food processing. The contrast between regions requires suppliers to match local grade requirements, logistics coverage, and seasonal sales patterns.
- Aarti Industries Ltd.
- Cargill, Incorporated
- Gulbrandsen Chemicals Pvt. Ltd.
- Nedmag B.V.
- Occidental Chemical Corporation (OxyChem)
- Shandong Haihua Group Co., Ltd.
- Solvay
- TANGSHAN SANYOU CHEMICAL INDUSTRIES CO., LTD.
- TETRA Technologies, Inc.
- Tiger Calcium
- Tokuyama Corporation
- Ward Chemical
- Weifang Haibin Chemical Co., Ltd.
- Weifang Taize Chemical Industry Co., Ltd.
- Zirax
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Growing Use of Calcium Chloride in Oil and Gas Drilling and Well Completion Operations
- 4.2.2 Increasing Preference for High-Performance De-Icing and Dust Control Solutions
- 4.2.3 Expanding Application of Calcium Chloride in Construction for Concrete Acceleration and Soil Stabilization
- 4.2.4 Growing Demand from the Food Processing Industry as a Firming, Preserving, and Coagulating Agent
- 4.2.5 Increasing Adoption of Calcium Chloride in Industrial Refrigeration and Cold Storage Systems
- 4.3 Market Restraints
- 4.3.1 High Corrosion Risks and Associated Maintenance Costs in Infrastructure and Transportation Assets
- 4.3.2 Storage, Handling, and Packaging Challenges Due to the Hygroscopic Nature of Calcium Chloride
- 4.3.3 Availability of Alternative De-Icing Chemicals and Dust Control Products
- 4.4 Value Chain Analysis
- 4.5 Porter's Five Forces Analysis
- 4.5.1 Threat of New Entrants
- 4.5.2 Bargaining Power of Suppliers
- 4.5.3 Bargaining Power of Buyers
- 4.5.4 Threat of Substitutes
- 4.5.5 Competitive Rivalry
5 Market Size and Growth Forecasts (Value)
- 5.1 By Grade
- 5.1.1 Industrial Grade
- 5.1.2 Food Grade
- 5.1.3 Pharmaceutical Grade
- 5.2 By Product Type
- 5.2.1 Flakes
- 5.2.2 Pellets and Prills
- 5.2.3 Liquid
- 5.2.4 Powder
- 5.3 By Application
- 5.3.1 De-Icing and Dust Control
- 5.3.2 Construction and Concrete Acceleration
- 5.3.3 Food and Beverage Processing
- 5.3.4 Oil and Gas (Drilling and Completion Fluids)
- 5.3.5 Water Treatment
- 5.3.6 Chemical Processing and Refrigeration
- 5.4 By End-Use Industry
- 5.4.1 Municipal and Public Infrastructure
- 5.4.2 Construction
- 5.4.3 Food and Beverage
- 5.4.4 Oil and Gas
- 5.4.5 Chemical
- 5.5 By Geography
- 5.5.1 Asia-Pacific
- 5.5.1.1 China
- 5.5.1.2 India
- 5.5.1.3 Japan
- 5.5.1.4 South Korea
- 5.5.1.5 Rest of Asia-Pacific
- 5.5.2 North America
- 5.5.2.1 United States
- 5.5.2.2 Canada
- 5.5.2.3 Mexico
- 5.5.3 Europe
- 5.5.3.1 Germany
- 5.5.3.2 United Kingdom
- 5.5.3.3 France
- 5.5.3.4 Italy
- 5.5.3.5 Russia
- 5.5.3.6 Rest of Europe
- 5.5.4 South America
- 5.5.4.1 Brazil
- 5.5.4.2 Argentina
- 5.5.4.3 Rest of South America
- 5.5.5 Middle-East and Africa
- 5.5.5.1 Saudi Arabia
- 5.5.5.2 South Africa
- 5.5.5.3 Rest of Middle-East and Africa
- 5.5.1 Asia-Pacific
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share (%)/Ranking Analysis
- 6.4 Company Profiles (includes Global Overview, Market Overview, Core Segments, Financials as available, Strategic Information, Products and Services, and Recent Developments)
- 6.4.1 Aarti Industries Ltd.
- 6.4.2 Cargill, Incorporated
- 6.4.3 Gulbrandsen Chemicals Pvt. Ltd.
- 6.4.4 Nedmag B.V.
- 6.4.5 Occidental Chemical Corporation (OxyChem)
- 6.4.6 Shandong Haihua Group Co., Ltd.
- 6.4.7 Solvay
- 6.4.8 TANGSHAN SANYOU CHEMICAL INDUSTRIES CO., LTD.
- 6.4.9 TETRA Technologies, Inc.
- 6.4.10 Tiger Calcium
- 6.4.11 Tokuyama Corporation
- 6.4.12 Ward Chemical
- 6.4.13 Weifang Haibin Chemical Co., Ltd.
- 6.4.14 Weifang Taize Chemical Industry Co., Ltd.
- 6.4.15 Zirax
7 Market Opportunities and Future Outlook
- 7.1 White-Space and Unmet-Need Assessment

