PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2119629

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2119629
China MCU - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
According to Mordor Intelligence, the China MCU market size was valued at USD 8.63 billion in 2025 and estimated to grow from USD 9.49 billion in 2026 to reach USD 15.23 billion by 2031, at a CAGR of 9.93% during the forecast period (2026-2031).
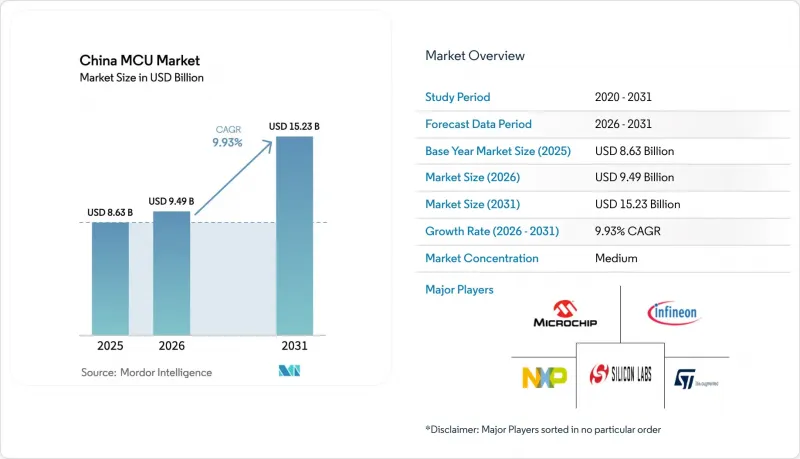
This report is Segmented by Architecture (8-Bit, 16-Bit, 32-Bit, and 64-Bit), Core IP (ARM Cortex-M Series, RISC-V Cores, and More), Process Node (above 90nm, 65-90nm, 40-60nm, 28-40nm, and Less Than 28nm), Application (Consumer Electronics, Automotive, Industrial Automation, Communication and IoT, Healthcare and Medical Devices, and More). The Market Forecasts are Provided in Terms of Value (USD).
China MCU Market Trends and Insights
Explosive Growth in China's EV Production Triggering High-Reliability Automotive MCU Demand
New-energy vehicle production broke the 11 million-unit mark in 2024 and delivered over 40% domestic penetration, sharply lifting MCU content per car to USD 900-1,000. Level 2+ driver-assistance systems reached 62.5% penetration the same year, pushing demand for redundant domain controllers built on multiple high-performance MCUs for sensor fusion and braking logic. Chinese vendors such as Zhaoyi Innovation advanced toward ISO 26262 ASIL-D compliance, though most still focus on body ECUs rather than safety-critical powertrain blocks. Foreign suppliers maintain the lead in qualified 32-bit automotive controllers, yet rising domestic capacity and policy support are narrowing the gap. The China MCU market is therefore experiencing a rapid uptick in AEC-Q100-qualified parts, tighter cybersecurity requirements, and longer product lifecycles that favor suppliers with robust functional-safety toolchains.
National "IoT+" Strategy Spurring Connected-Device MCU Volumes
Beijing's IoT+ blueprint underwrote more than 8,000 5G+Industrial-Internet projects by 2024, catapulting specialized 32-bit MCU demand for real-time machine control. China's AIoT sector reached RMB 1.7 trillion in 2024, with AI-enabled terminals accounting for 55% of shipments and headed toward 80% by 2027. Bluetooth Low Energy modules, integral to TWS earbuds and wearables, are projected to top USD 1 billion worldwide by 2025, expanding at mid-teen CAGRs and anchoring MCU integration of wireless cores. Edge-side inferencing is permeating factory and consumer devices, forcing controller vendors to embed NPUs and secure elements into pin-compatible packages. This policy-driven proliferation of smart nodes cements the China MCU market as a volume engine for globally aligned IoT platforms.
U.S. Export Controls Curbing Access to Advanced EDA and Lithography Tools
Restrictions enacted by the United States hamper Chinese access to EUV scanners and advanced EDA suites, lifting projected 5 nm costs at SMIC by 40-50% versus TSMC peers while yields sit at roughly one-third of leading-edge benchmarks. Lack of EUV machinery forces DUV multi-patterning, inflating mask counts and cycle times. MCU designs targeting AI edge nodes or in-vehicle infotainment that need high logic density face performance-per-watt penalties. Domestic toolchains are progressing but still trail global incumbents in timing-closure and power-optimization depth. This technological drag tempers top-end growth of the China MCU market and slows adoption of sub-14 nm nodes.
Other drivers and restraints analyzed in the detailed report include:
- Government Subsidies to Accelerate Domestic MCU Design-in (Made-in-China 2025)
- Industrial 4.0 Retrofits in SMEs Raising Adoption of 32-bit Industrial-Grade MCUs
- Persistent Wafer-Level Supply Bottlenecks in 40 nm and 28 nm Nodes
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
The China MCU market size for 32-bit devices reached USD 4.64 billion in 2025, equating to 53.78% revenue share. Edge AI workloads, surround-view stitching, and high-speed industrial vision accelerate 64-bit adoption, lifting that segment at an 10.88% CAGR. Sixteen-bit and eight-bit controllers linger in cost-sensitive appliances and small sensor nodes, yet their combined share slips yearly as 28 nm 32-bit pricing compresses. Suzhou Guoxin's CCR4001S marries a 230 MHz RISC-V core with a 0.3 TOPS NPU, demonstrating domestic ambition to migrate control and inference onto one die. Automotive OEMs specify multicore lock-step 32-bit parts for body domain and dual-A76 64-bit SoCs for digital cockpit clusters, reinforcing a tiered architecture roadmap within the China MCU market.
Second-order effects include tighter alignment between memory density and compute throughput. As capacitive-touch HMIs enter appliances, firmware swells into the megabyte range, making on-chip flash a differentiation point. Vendors thus bundle 2-4 MB of eFlash in mid-range 32-bit MCUs. Concurrently, 64-bit controllers integrate LPDDR4 PHYs to stream neural-network weights. These advances collectively edge the China MCU market toward heterogeneous compute paradigms inside constrained power envelopes.
ARM retained 61.05% of 2025 revenue, but royalty-free RISC-V cores chalked up double-digit growth, aided by government grants and open-source toolchains. Zhenhua Fengguang taped out its first fully indigenous 32-bit RISC-V MCU in January 2025, positioning for pilot production by year-end. Ultra-low-cost RISC-V parts priced near USD 0.10 invigorate entry-level IoT nodes. Design freedom enables domestic firms to add custom DSP blocks for motor control or crypto accelerators for digital-yuan wallets without paying license fees. However, migration hurdles include IDE maturity, middleware depth, and safety certification libraries, factors that still buttress ARM's lead in the China MCU market.
Legacy 8051 cores persist in power meters and basic lighting controls, offering deterministic cycle timing and tiny die sizes on above 90 nm nodes. Yet new 8-bit sockets dwindle as ODMs standardize toolchains around 32-bit units with cost parity. The net result is an increasingly bifurcated China MCU market where premium performance leans toward 64-bit RISC-V and mass-market control consolidates on low-cost 32-bit ARM alternatives.
Complete Report Scope:
- By Architecture
- 8-bit
- 16-bit
- 32-bit
- 64-bit
- By Core IP
- ARM Cortex-M Series
- RISC-V Cores
- 8051 / MCS-51
- MIPS and Others
- By Process Node
- above 90 nm
- 65 - 90 nm
- 40 - 60 nm
- 28 - 40 nm
- less than 28 nm
- By Application
- Consumer Electronics
- Automotive
- Industrial Automation
- Communication and IoT
- Healthcare and Medical Devices
- Other Applications
List of Companies Covered in this Report:
- Microchip Technology Inc.
- NXP Semiconductors N.V.
- STMicroelectronics N.V.
- Texas Instruments Incorporated
- Renesas Electronics Corporation
- Infineon Technologies AG
- GigaDevice Semiconductor Inc.
- Nuvoton Technology Corporation
- Holtek Semiconductor Inc.
- Silicon Laboratories Inc.
- Nordic Semiconductor ASA
- Espressif Systems (Shanghai) Co., Ltd.
- Shanghai MindMotion Microelectronics Co., Ltd.
- Shanghai ChipON Micro-Electronics Co., Ltd.
- Wuhan Eastsoft Embedded System Co., Ltd.
- Nationz Technologies Inc.
- Hangzhou C-SKY Microsystems Co., Ltd.
- Actions Technology Co., Ltd.
- Sanechips Technology Co., Ltd.
- Hangzhou ASR Microelectronics Co., Ltd.
- Shenzhen Beken Corporation Ltd.
- Qingdao Eastsoft Microelectronics Co., Ltd.
- Zhuhai Abov Microelectronics Co., Ltd.
- Austriamicrosystems AG
- Chongqing Sino-MCU Technology Co., Ltd.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Explosive growth in China's EV production triggering high-reliability automotive MCU demand
- 4.2.2 National "IoT +" strategy spurring connected-device MCU volumes
- 4.2.3 Government subsidies to accelerate domestic MCU design-in (Made-in-China 2025)
- 4.2.4 Industrial 4.0 retrofits in SMEs raising adoption of 32-bit industrial-grade MCUs
- 4.2.5 Emergence of RISC-V open ISA in Chinese MCUs lowering entry barriers
- 4.2.6 Digital-yuan hardware wallet roll-out creating an all-new secure-MCU niche
- 4.3 Market Restraints
- 4.3.1 U.S. export controls curbing access to advanced EDA and lithography tools
- 4.3.2 Persistent wafer-level supply bottlenecks in 40 nm, 28 nm nodes
- 4.3.3 Scarcity of functional-safety talent for ISO 26262-compliant MCU designs
- 4.3.4 Reliability certification hurdles for domestic MCUs in Tier-1 auto OEMs
- 4.4 Industry Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Suppliers
- 4.7.3 Bargaining Power of Buyers
- 4.7.4 Threat of Substitutes
- 4.7.5 Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Architecture
- 5.1.1 8-bit
- 5.1.2 16-bit
- 5.1.3 32-bit
- 5.1.4 64-bit
- 5.2 By Core IP
- 5.2.1 ARM Cortex-M Series
- 5.2.2 RISC-V Cores
- 5.2.3 8051 / MCS-51
- 5.2.4 MIPS and Others
- 5.3 By Process Node
- 5.3.1 above 90 nm
- 5.3.2 65 - 90 nm
- 5.3.3 40 - 60 nm
- 5.3.4 28 - 40 nm
- 5.3.5 less than 28 nm
- 5.4 By Application
- 5.4.1 Consumer Electronics
- 5.4.2 Automotive
- 5.4.3 Industrial Automation
- 5.4.4 Communication and IoT
- 5.4.5 Healthcare and Medical Devices
- 5.4.6 Other Applications
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)
- 6.4.1 Microchip Technology Inc.
- 6.4.2 NXP Semiconductors N.V.
- 6.4.3 STMicroelectronics N.V.
- 6.4.4 Texas Instruments Incorporated
- 6.4.5 Renesas Electronics Corporation
- 6.4.6 Infineon Technologies AG
- 6.4.7 GigaDevice Semiconductor Inc.
- 6.4.8 Nuvoton Technology Corporation
- 6.4.9 Holtek Semiconductor Inc.
- 6.4.10 Silicon Laboratories Inc.
- 6.4.11 Nordic Semiconductor ASA
- 6.4.12 Espressif Systems (Shanghai) Co., Ltd.
- 6.4.13 Shanghai MindMotion Microelectronics Co., Ltd.
- 6.4.14 Shanghai ChipON Micro-Electronics Co., Ltd.
- 6.4.15 Wuhan Eastsoft Embedded System Co., Ltd.
- 6.4.16 Nationz Technologies Inc.
- 6.4.17 Hangzhou C-SKY Microsystems Co., Ltd.
- 6.4.18 Actions Technology Co., Ltd.
- 6.4.19 Sanechips Technology Co., Ltd.
- 6.4.20 Hangzhou ASR Microelectronics Co., Ltd.
- 6.4.21 Shenzhen Beken Corporation Ltd.
- 6.4.22 Qingdao Eastsoft Microelectronics Co., Ltd.
- 6.4.23 Zhuhai Abov Microelectronics Co., Ltd.
- 6.4.24 Austriamicrosystems AG
- 6.4.25 Chongqing Sino-MCU Technology Co., Ltd.
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-Need Assessment

