PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2119667

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2119667
Americas Interventional Radiology - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
According to Mordor Intelligence, americas interventional radiology market size in 2026 is estimated at USD 13.54 billion, growing from 2025 value of USD 12.76 billion with 2031 projections showing USD 18.21 billion, growing at 6.13% CAGR over 2026-2031.
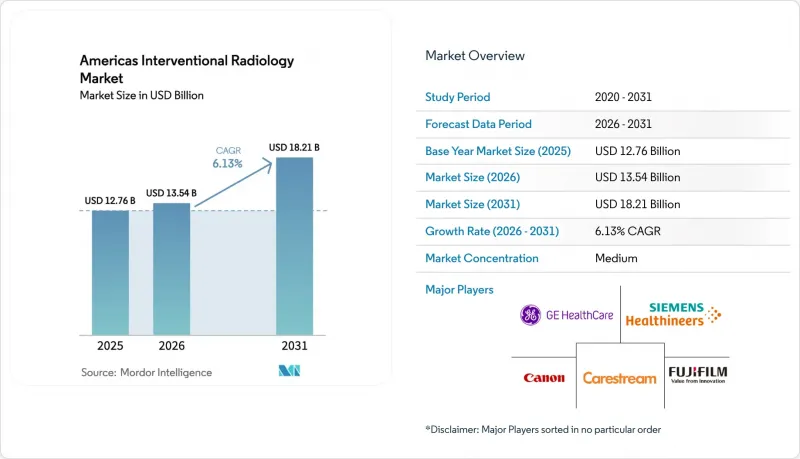
This report is Segmented by Product (Imaging Equipment, Interventional Consumables & Devices), Application (Cardiology, Oncology, Urology & Nephrology, Gastroenterology, Neurology), End User (Hospitals, Office-Based Labs/ASCs, Specialty Clinics), and Geography (North America, South America). The Market Forecasts are Provided in Terms of Value (USD).
Americas Interventional Radiology Market Trends and Insights
Increasing Burden of Chronic Cardiovascular & Oncological Diseases
Hypertension prevalence is projected to climb from 51.2% to 61.0% by 2050, and diabetes from 16.3% to 26.8%, adding a steady pipeline of complex cases amenable to catheter-based interventions. The aging population magnifies disease incidence, while patient preference for shorter recovery dovetails with hospital efforts to lower length of stay. Together these factors increase case volumes for peripheral angioplasty, renal denervation, and tumor embolization. Consequently, America's interventional radiology market benefits from structural tailwinds that consistently replenish procedural demand.
Technological Advances in IR Imaging (Photon-Counting CT, AI, AR)
Photon-counting detector CT enables higher spatial resolution and intrinsic spectral separation, which improves tissue contrast while cutting radiation dose compared to energy-integrating systems, thereby elevating diagnostic certainty in complex vascular interventions. Clinical studies show vessel-sharpness ratings of 134.7 HU/mm versus 100.9 HU/mm on conventional scanners, facilitating precise device deployment in coronary and neurovascular procedures. AI-enabled robotic platforms overlay real-time trajectory guidance, automate wire manipulation, and reduce fluoroscopy time by up to 56%, which eases radiation safety concerns for staff and patients. Augmented-reality head-mounted displays further shorten learning curves for complex ablation or embolization. Early adopters realize competitive gains through lower complication rates and higher throughput, reinforcing the technological arms race within America's interventional radiology market.
High Capital Cost of IR Suites & Advanced Imaging Modalities
Photon-counting CT scanners, robotic C-arms, and hybrid operating rooms each require outlays above USD 2 million, with entire suite buildouts reaching USD 5 million, which strains hospital balance sheets already operating at 1.2% median operating margins. Annual service contracts consume 15 - 20% of purchase price, while software upgrades add incremental costs that small systems struggle to absorb. Latin American hospitals face 30 - 40% price premiums driven by import tariffs and currency volatility, raising barriers to adoption. Deferred-payment leasing and refurbished equipment programs are expanding, yet premium financing charges dilute investment returns. As a result, America's interventional radiology market encounters localized slowdowns where capital intensity outweighs clinical demand.
Other drivers and restraints analyzed in the detailed report include:
- Rapid Expansion of Office-Based Labs (OBLs) & ASCs in the Americas
- Shift to Value-Based Care Favoring Minimally-Invasive IR Over Surgery
- Shortage of Trained Interventional Radiologists in Latin America
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Consumables and devices accounted for 52.22% of America's interventional radiology market share in 2025, buoyed by high procedure frequency and single-use mandates that accelerate replacement cycles. Stents, catheters, guidewires, and embolic agents dominate hospital procurement lists because multifaceted procedures require multiple SKUs per case. The stent subsegment gained further traction after Abbott secured FDA clearance for its dissolving Esprit BTK scaffold for below-the-knee disease, a milestone that reshapes peripheral revascularization options. Biopsy and thrombectomy kits also expand as stroke and oncology protocols emphasize early intervention.
Imaging equipment represents the fastest-growing category at a 6.73% CAGR through 2031 as facilities upgrade to photon-counting CT, self-driving C-arms, and AI-integrated MRI that mitigate radiologist shortages and enhance workflow. Hospitals leverage financing partnerships to acquire comprehensive platforms that bundle scanners, software, and analytics services, improving lifetime value. AI-rich ultrasound systems are penetrating office-based labs due to portability and rapid learning curves, while angiography suites adopt radiation-free light-based navigation that can slash fluoroscopy exposure by over half. These trends drive a premium replacement cycle that anchors long-term expansion in America's interventional radiology market.
Complete Report Scope:
- By Product
- Imaging Equipment
- MRI Systems
- CT Scanners
- Ultrasound Imaging Systems
- Angiography Systems
- Fluoroscopy Systems
- Interventional Consumables & Devices
- Stents
- Catheters & Guidewires
- Angioplasty Balloons
- Embolization & Thrombectomy Devices
- Biopsy Devices
- IVC Filters & Accessories
- Imaging Equipment
- By Application
- Cardiology
- Oncology
- Urology & Nephrology
- Gastroenterology
- Neurology
- By End User
- Hospitals
- Office-Based Labs (OBLs) / Ambulatory Surgical Centers (ASCs)
- Specialty Clinics
- Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Rest of South America
- North America
List of Companies Covered in this Report:
- Boston Scientific
- Medtronic
- Abbott Laboratories
- GE Healthcare
- Koninklijke Philips
- Siemens Healthineers
- Fujifilm Holdings Corp.
- Stryker Corporation (Neurovascular)
- Terumo
- Beckton Dickinson
- AngioDynamics
- Penumbra
- Cook Group
- Merit Medical Systems
- Cardinal Health Inc. (Cordis)
- Canon
- Ziehm Imaging
- IMBiotechnologies Ltd. (Canada)
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Increasing burden of chronic cardiovascular & oncological diseases
- 4.2.2 Technological advances in IR imaging (photon-counting CT, AI, AR)
- 4.2.3 Rapid expansion of office-based labs (OBL) & ASCs in the Americas (under-reported)
- 4.2.4 Favorable reimbursement revisions for IR codes in U.S. and Brazil
- 4.2.5 Shift to value-based care favouring minimally-invasive IR over surgery (under-reported)
- 4.3 Market Restraints
- 4.3.1 High capital cost of IR suites & advanced imaging modalities
- 4.3.2 Shortage of trained interventional radiologists in Latin America
- 4.3.3 Stringent ANVISA-level approval timelines delaying device launches
- 4.3.4 Post-COVID capex deferrals by hospitals (under-reported)
- 4.4 Value / Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Suppliers
- 4.7.3 Bargaining Power of Buyers
- 4.7.4 Threat of Substitutes
- 4.7.5 Competitive Rivalry
5 Market Size & Growth Forecasts (Value, USD)
- 5.1 By Product
- 5.1.1 Imaging Equipment
- 5.1.1.1 MRI Systems
- 5.1.1.2 CT Scanners
- 5.1.1.3 Ultrasound Imaging Systems
- 5.1.1.4 Angiography Systems
- 5.1.1.5 Fluoroscopy Systems
- 5.1.2 Interventional Consumables & Devices
- 5.1.2.1 Stents
- 5.1.2.2 Catheters & Guidewires
- 5.1.2.3 Angioplasty Balloons
- 5.1.2.4 Embolization & Thrombectomy Devices
- 5.1.2.5 Biopsy Devices
- 5.1.2.6 IVC Filters & Accessories
- 5.1.1 Imaging Equipment
- 5.2 By Application
- 5.2.1 Cardiology
- 5.2.2 Oncology
- 5.2.3 Urology & Nephrology
- 5.2.4 Gastroenterology
- 5.2.5 Neurology
- 5.3 By End User
- 5.3.1 Hospitals
- 5.3.2 Office-Based Labs (OBLs) / Ambulatory Surgical Centers (ASCs)
- 5.3.3 Specialty Clinics
- 5.4 Geography
- 5.4.1 North America
- 5.4.1.1 United States
- 5.4.1.2 Canada
- 5.4.1.3 Mexico
- 5.4.2 South America
- 5.4.2.1 Brazil
- 5.4.2.2 Argentina
- 5.4.2.3 Rest of South America
- 5.4.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Market Share Analysis
- 6.3 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products & Services, and Recent Developments)
- 6.3.1 Boston Scientific Corporation
- 6.3.2 Medtronic plc
- 6.3.3 Abbott Laboratories
- 6.3.4 GE HealthCare
- 6.3.5 Philips Healthcare
- 6.3.6 Siemens Healthineers AG
- 6.3.7 Fujifilm Holdings Corp.
- 6.3.8 Stryker Corporation (Neurovascular)
- 6.3.9 Terumo Corporation
- 6.3.10 Becton, Dickinson and Company (BD)
- 6.3.11 AngioDynamics Inc.
- 6.3.12 Penumbra Inc.
- 6.3.13 Cook Medical LLC
- 6.3.14 Merit Medical Systems Inc.
- 6.3.15 Cardinal Health Inc. (Cordis)
- 6.3.16 Canon Medical Systems Corp.
- 6.3.17 Ziehm Imaging
- 6.3.18 IMBiotechnologies Ltd. (Canada)
7 Market Opportunities & Future Outlook
- 7.1 White-Space & Unmet-Need Assessment

