PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2119746

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2119746
User-Generated Content Platform - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
According to Mordor Intelligence, the user-generated content platform market size is expected to grow from USD 9.85 billion in 2025 to USD 12.63 billion in 2026 and is forecast to reach USD 43.92 billion by 2031 at 28.32% CAGR over 2026-2031.
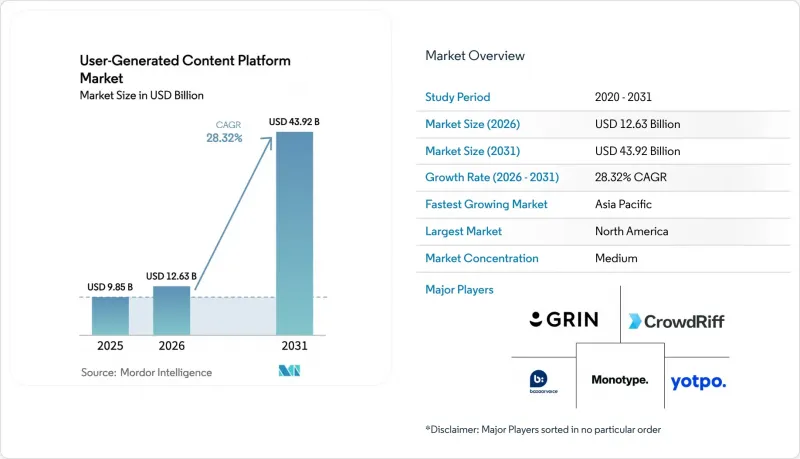
This report is Segmented by Product Type (Blogs, Social Media Posts, Audio and Video, and More), End-User (Individuals, Small and Medium Enterprises, and Large Enterprises), Deployment Mode (Cloud-Based, and On-premises/Private Cloud), Revenue Model (Advertising-Supported, Subscription/SaaS, and More), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global User-Generated Content Platform Market Trends and Insights
Influencer-Driven Commerce Acceleration
Brands fusing creator networks with integrated checkout features are shortening purchase funnels and driving measurable ROI improvements. Influencer marketing platforms generated USD 21 billion in 2024 revenue, with micro-influencers producing 60% higher engagement than macro creators. Enterprise demand for scalable identification of niche creators is propelling investment in AI-based discovery engines. Shoppable content integrations are eliminating an average of 2.3 customer touchpoints, reinforcing the strategic imperative for real-time UGC activation. Updated FTC endorsement guidelines are encouraging platforms that automate disclosure compliance, boosting trust and reinforcing growth across the user-generated content platform market.
Short-Form Video Platforms Fueling UGC Volumes
Platforms processed more than 720,000 video hours daily in late 2024. This surge increases the need for intelligent curation systems that surface relevant clips for brands drowning in content abundance. Vertical-video formats optimized for mobile use now deliver 40% higher engagement, prompting platforms to redeploy recommendation algorithms. Meta's September 2024 AI studio rollout accelerated creator productivity and preserved hallmark authenticity, fueling additional demand for analytics that validate performance while filtering deceptive content. These forces collectively expand platform stickiness and monetization opportunities inside the user-generated content platform market.
Brand-Safety and Content-Moderation Costs
Industry-wide moderation spend surpassed USD 25 billion in 2024, with more than 1 million human moderators supplementing AI filters. The EU Digital Services Act heightened obligations, forcing sophisticated classification and 24-hour takedown windows that add USD 2.8 billion in annual compliance expenses for dominant firms. AI tools trim per-item costs by 35%, yet nuanced contextual evaluation still demands human oversight, especially for enterprise campaigns where a single unsafe placement can void contracts. These operating burdens temper profitability and slow near-term expansion in the user-generated content platform market.
Other drivers and restraints analyzed in the detailed report include:
- Social-Commerce Integrations by Major Retailers
- Generative-AI-Assisted Content Creatio
- Rising Regulatory Scrutiny on Data Use
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Social media posts contributed 41.18% of 2025 revenue, underscoring their entrenched role in brand storytelling. Live-streaming boasts the highest 30.12% CAGR through 2031, reflecting consumer appetite for real-time interaction and tipping-based monetization. Gaming-centric broadcasts produced USD 4.2 billion in creator revenue during 2024. Audio-video hybrids continue steady growth as production kits become affordable. Ratings and reviews remain foundational trust signals, especially when embedded in e-commerce checkouts. Blogs, while mature, are regaining momentum through AI-enhanced multimedia inserts.
Cloud-native AI tagging systems ensure compliance with evolving classification standards set by the EU's Digital Services Act, reducing manual workload. Vertical video algorithms optimized for smartphones are lifting dwell times and click-throughs. As these mobile-first experiences proliferate, providers capable of cross-format orchestration gain share, sustaining the user-generated content platform market expansion.
Large enterprises held 43.21% of 2025 revenue, leveraging integrations with CRM and martech stacks to measure full-funnel ROI. SMEs, however, post a 30.25% CAGR to 2031 as subscription tiers remove upfront investment hurdles. Authentic customer photos and videos drive 45% higher SME engagement than brand-authored assets, closing performance gaps with larger competitors.
Enterprise buyers demand robust brand-safety dashboards and API-level data transfers for attribution modeling. SMEs prioritize quick onboarding, guided workflows, and bundled rights management. Platforms offering tiered configurations appease both cohorts, broadening the user-generated content platform market addressable base.
Complete Report Scope:
- By Product Type
- Blogs
- Social Media Posts
- Audio and Video
- Ratings and Reviews
- Live-Streaming
- By End-user
- Individuals
- Small and Medium Enterprises
- Large Enterprises
- By Deployment Mode
- Cloud-based
- On-premise / Private Cloud
- By Revenue Model
- Advertising-supported
- Subscription / SaaS
- Freemium and Transaction-based
- By Geography
- North America
- South America
- Europe
- Asia-Pacific
- Middle East and Africa
Geography Analysis
North America's user-generated content platform market size benefited from USD-denominated brand budgets and broad enterprise SaaS penetration, sustaining higher average revenue per user. The region's stringent brand-safety demands foster advanced moderation tooling, elevating barrier-to-entry for smaller competitors. Ongoing state privacy bills create parallel compliance tracks that platforms must harmonize without sacrificing agility.
Asia-Pacific's explosive content volume and creator population underpin a vibrant competitive field. Localized payment rails and super-app ecosystems catalyze micro-transactions within live-streams, driving monetization innovation. Government support programs in South Korea and Indonesia subsidize digital-skills training, expanding the creator base and demand for platform services. However, content censorship guidelines require adaptable classification engines to avert takedowns.
The Middle East and Africa records the highest forecast CAGR, propelled by smartphone affordability and carrier-backed zero-rating of social platforms that amplify reach. E-commerce rollouts across Gulf Cooperation Council states integrate shoppable UGC feeds, translating social discovery into purchase at unprecedented speed. Local languages and dialects challenge global AI filters, incentivizing regional partnerships that supply contextual training data. Collectively, divergent regional dynamics reinforce the heterogeneity of the global user-generated content platform market.
- Bazaarvoice Inc.
- Yotpo Ltd.
- Pixlee TurnTo Corp.
- CrowdRiff Inc.
- Grin Technologies Inc.
- Upfluence SAS
- Taggbox Private Limited
- Stackla Pty Ltd (a Nosto company)
- Olapic Inc.
- TINT (Filestack Inc.)
- Social Native Inc.
- Khoros LLC
- Sprinklr Inc.
- Nosto Solutions Oy
- Adobe Inc. (UGC Framework)
- Hootsuite Inc.
- Later Media Inc.
- Dash Hudson Inc.
- Curalate, LLC
- Monotype Imaging Holdings Inc.
- Pancake Laboratories Inc.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Influencer-driven commerce acceleration
- 4.2.2 Short-form video platforms fueling UGC volumes
- 4.2.3 Social-commerce integrations by major retailers
- 4.2.4 Generative-AI-assisted content creation
- 4.2.5 Web3 token-based creator monetisation models
- 4.2.6 Privacy-centric first-party data advantages
- 4.3 Market Restraints
- 4.3.1 Brand-safety and content-moderation costs
- 4.3.2 Rising regulatory scrutiny on data use
- 4.3.3 Decline of third-party cookies reducing ad yields
- 4.3.4 Generative-AI misinformation risks
- 4.4 Industry Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Bargaining Power of Buyers
- 4.7.2 Bargaining Power of Suppliers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
- 4.8 Impact of Macroeconomic Factors
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Product Type
- 5.1.1 Blogs
- 5.1.2 Social Media Posts
- 5.1.3 Audio and Video
- 5.1.4 Ratings and Reviews
- 5.1.5 Live-Streaming
- 5.2 By End-user
- 5.2.1 Individuals
- 5.2.2 Small and Medium Enterprises
- 5.2.3 Large Enterprises
- 5.3 By Deployment Mode
- 5.3.1 Cloud-based
- 5.3.2 On-premise / Private Cloud
- 5.4 By Revenue Model
- 5.4.1 Advertising-supported
- 5.4.2 Subscription / SaaS
- 5.4.3 Freemium and Transaction-based
- 5.5 By Geography
- 5.5.1 North America
- 5.5.2 South America
- 5.5.3 Europe
- 5.5.4 Asia-Pacific
- 5.5.5 Middle East and Africa
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global Overview, Market Overview, Core Segments, Financials, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)
- 6.4.1 Bazaarvoice Inc.
- 6.4.2 Yotpo Ltd.
- 6.4.3 Pixlee TurnTo Corp.
- 6.4.4 CrowdRiff Inc.
- 6.4.5 Grin Technologies Inc.
- 6.4.6 Upfluence SAS
- 6.4.7 Taggbox Private Limited
- 6.4.8 Stackla Pty Ltd (a Nosto company)
- 6.4.9 Olapic Inc.
- 6.4.10 TINT (Filestack Inc.)
- 6.4.11 Social Native Inc.
- 6.4.12 Khoros LLC
- 6.4.13 Sprinklr Inc.
- 6.4.14 Nosto Solutions Oy
- 6.4.15 Adobe Inc. (UGC Framework)
- 6.4.16 Hootsuite Inc.
- 6.4.17 Later Media Inc.
- 6.4.18 Dash Hudson Inc.
- 6.4.19 Curalate, LLC
- 6.4.20 Monotype Imaging Holdings Inc.
- 6.4.21 Pancake Laboratories Inc.
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-Need Assessment

