PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2120345

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2120345
Memristor - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
According to Mordor Intelligence, the memristor market size reached USD 28.6 billion in 2026 and is forecast to climb to USD 155.09 billion by 2031, advancing at a 28.6% CAGR over the period.
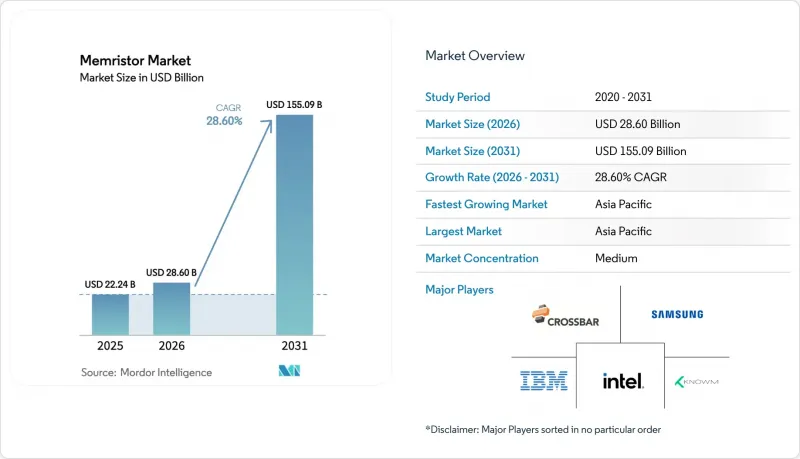
This report is Segmented by Application (Non-Volatile Memory, Neuromorphic and Biological System, Programmable Logic and Signal Processing, and More), End-User Industry (Consumer Electronics, IT and Telecom, Automotive, Healthcare, and More), Technology (Molecular and Ionic Thin Film, and More), Material (Metal Oxide, Chalcogenide, and More), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global Memristor Market Trends and Insights
Increasing Demand for IoT, Cloud Computing, and Big Data
Hyperscalers are deploying memristive compute-in-memory arrays to curb the 80% energy overhead linked to data movement in von Neumann cores. A fully integrated chip from Tsinghua consumes 3% of ASIC baselines, enabling real-time learning on wearables and autonomous vehicles. In June 2025, SoftBank, Intel, and the University of Tokyo formed SAIMEMORY with JPY 3 billion (USD 22.2 million) seed capital to commercialize high-capacity low-power memory. Edge devices profit from zero standby leakage, and Asia-Pacific consumer-electronics vendors are quick to integrate such arrays. North American hyperscalers are piloting neuromorphic accelerators for recommendation engines, expanding the immediate addressable memristor market.
Surging Adoption of Autonomous Robots
Warehouse and factory robots demand deterministic latency that legacy DRAM-GPU stacks cannot meet. KAIST demonstrated an insect-mimicking motion detector consuming 92.9% less energy than existing designs while raising prediction accuracy. BrainChip's Akida processor, embedding memristive synapses, has attracted OEMs that require millisecond responses. Collaborative robots across East Asian factories have become early volume customers, and Europe's industrial automation sector is following in medium-term procurement cycles. These deployments push up unit demand for ruggedized memristors with high endurance and low-temperature drift.
Complexity in Technological Application
System-on-chip designers must co-optimize materials, analog circuits, and network algorithms, yet such multidisciplinary talent is scarce. The University of Tokyo's multilevel TaOx test chip balanced 10-year retention with higher density using new activation functions unrecognized by standard frameworks. This gap forces bespoke toolchains, extends time-to-market, and raises non-recurring engineering cost. Regions with nascent ecosystems feel the pinch most, but shared reference designs expected from 2026 products should gradually reduce barriers.
Other drivers and restraints analyzed in the detailed report include:
- Rising Adoption of Edge AI Accelerators Requiring In-Memory Computing
- Semiconductor Scaling Limits Pushing Beyond CMOS Memory Designs
- High Switching Variability and Endurance Issues
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
In 2025, non-volatile memory represented 45.22% revenue, anchored by embedded flash replacements in microcontrollers. The memristor market size tied to neuromorphic and biological systems is set to grow at 36.22% CAGR as laboratories transition from simulation to production silicon. KAIST's selector-less array demonstrated real-time learning for security cameras, proving commercial viability. Programmable logic uses, such as adaptive filters in 5G radio, are also increasing. As compute-centric architectures outpace pure storage, the memristor market will witness value shifting toward devices optimized for multiply-accumulate precision.
The pivot is underscored by Tsinghua's integrated compute-in-memory chip, which operates at 3% of ASIC energy. Storage-class memory pilots by hyperscalers further blend the boundary between memory and logic. Secondary roles like random-number generation and physically unclonable functions add incremental demand, reinforcing the memristor market's diversification.
Consumer electronics held 31.55% revenue in 2025, leveraging on-device AI for voice and camera tasks. Automotive demand is accelerating at a 27.53% CAGR as electric vehicles embed advanced driver assistance requiring sub-millisecond inference. BrainChip's Akida processor is already integrated into pedestrian-detection modules. Edge telecom and IT buyers deploy memristive accelerators in 5G base stations to trim backhaul latency, boosting the memristor market share inside carrier infrastructure.
Healthcare devices enjoy long battery life thanks to zero leakage, while industrial automation uses memristors for adaptive robot controllers. Defense contracts, such as DARPA's REMIND award, secure revenue streams for radiation-hardened variants. Emerging sectors, agriculture and retail among them, experiment with sensor nodes, signaling broadening addressable opportunities for the memristor market.
Complete Report Scope:
- By Application
- Non-volatile Memory
- Neuromorphic and Biological System
- Programmable Logic and Signal Processing
- Emerging Data Storage
- Other Applications
- By End-user Industry
- Consumer Electronics
- IT and Telecom
- Automotive
- Healthcare
- Industrial Automation
- Defense and Aerospace
- Other End-user Industries
- By Technology
- Molecular and Ionic Thin Film
- Spin-based and Magnetic Memristor
- Hybrid CMOS-Memristor
- 3D Crosspoint
- Other Technologies
- By Material
- Metal Oxide
- Chalcogenide
- Spintronic
- Organic Polymer
- Ferroelectric
- Other Materials
- By Geography
- North America
- United States
- Canada
- Mexico
- Rest of North America
- Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Russia
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- South Korea
- Australia
- Rest of Asia-Pacific
- South America
- Brazil
- Argentina
- Rest of South America
- Middle East
- Saudi Arabia
- United Arab Emirates
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Nigeria
- Rest of Africa
- North America
Geography Analysis
Asia-Pacific led the memristor market with 53.33% revenue in 2025 and is projected to grow at 21.90% CAGR through 2031. Japan earmarked JPY 10 trillion (USD 67 billion) for semiconductor programs, underpinning ventures like SAIMEMORY. China's Tsinghua University delivered a compute-in-memory chip consuming 3% of ASIC baselines, while South Korea's KAIST unveiled phase-change and neuromorphic breakthroughs during 2024-2025. Taiwan's TSMC co-authored multiple Nature papers on memristive integration, signaling foundry scale-up. India and Southeast Asian states are enhancing design education, yet their memristor ecosystems remain early-stage.
North America ranked second in 2025, propelled by defense needs and hyperscaler AI investment. DARPA's USD 11.6 million REMIND grant funds space-grade ReRAM, and amended U.S. microelectronics strategy lists memristive materials as national priorities. IBM and Intel continue research on phase-change and neuromorphic architectures, while Canada and Mexico contribute packaging and design talent.
Europe followed, with Germany, France, and the United Kingdom piloting advanced driver assistance and predictive-maintenance accelerators. The European Space Agency evaluates memristor radiation tolerance for deep-space probes. South America, the Middle East, and Africa show nascent but rising interest, especially in smart-city deployments, yet supply-chain constraints limit rapid scaling. Asia-Pacific and North America are therefore set to maintain dominant memristor market positions through 2031.
- Crossbar Inc.
- Panasonic Corporation
- 4DS Memory Limited
- Adesto Technology Inc.
- Micron Technology Inc.
- Samsung Electronics Co. Ltd.
- Sony Group Corporation
- Western Digital Corporation
- Knowm Inc.
- Intel Corporation
- IBM Corporation
- SK hynix Inc.
- Weebit Nano Ltd.
- Fujitsu Limited
- Toshiba Corporation
- Honeywell International Inc.
- Everspin Technologies Inc.
- STMicroelectronics N.V.
- Avalanche Technology Inc.
- HP Inc.
- Taiwan Semiconductor Manufacturing Company Limited
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Increasing Demand for IoT, Cloud Computing, and Big Data
- 4.2.2 Surging Adoption of Autonomous Robots
- 4.2.3 Rising Adoption of Edge AI Accelerators Requiring In-Memory Computing
- 4.2.4 Semiconductor Scaling Limits Pushing Beyond CMOS Memory Designs
- 4.2.5 Defense Funding for Radiation-Hardened Space Memory
- 4.2.6 Growing Focus on Carbon-Neutral Data Centers
- 4.3 Market Restraints
- 4.3.1 Complexity in Technological Application
- 4.3.2 High Switching Variability and Endurance Issues
- 4.3.3 Immature Design Automation Toolchains
- 4.3.4 Supply-Chain Dependence on Rare-Earth Materials
- 4.4 Industry Value / Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Industry Impact of Macroeconomic Factors on the Market
- 4.8 Porter's Five Forces Analysis
- 4.8.1 Threat of New Entrants
- 4.8.2 Bargaining Power of Buyers
- 4.8.3 Bargaining Power of Suppliers
- 4.8.4 Threat of Substitute Products
- 4.8.5 Intensity of Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUES)
- 5.1 By Application
- 5.1.1 Non-volatile Memory
- 5.1.2 Neuromorphic and Biological System
- 5.1.3 Programmable Logic and Signal Processing
- 5.1.4 Emerging Data Storage
- 5.1.5 Other Applications
- 5.2 By End-user Industry
- 5.2.1 Consumer Electronics
- 5.2.2 IT and Telecom
- 5.2.3 Automotive
- 5.2.4 Healthcare
- 5.2.5 Industrial Automation
- 5.2.6 Defense and Aerospace
- 5.2.7 Other End-user Industries
- 5.3 By Technology
- 5.3.1 Molecular and Ionic Thin Film
- 5.3.2 Spin-based and Magnetic Memristor
- 5.3.3 Hybrid CMOS-Memristor
- 5.3.4 3D Crosspoint
- 5.3.5 Other Technologies
- 5.4 By Material
- 5.4.1 Metal Oxide
- 5.4.2 Chalcogenide
- 5.4.3 Spintronic
- 5.4.4 Organic Polymer
- 5.4.5 Ferroelectric
- 5.4.6 Other Materials
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.1.4 Rest of North America
- 5.5.2 Europe
- 5.5.2.1 Germany
- 5.5.2.2 France
- 5.5.2.3 United Kingdom
- 5.5.2.4 Italy
- 5.5.2.5 Spain
- 5.5.2.6 Russia
- 5.5.2.7 Rest of Europe
- 5.5.3 Asia-Pacific
- 5.5.3.1 China
- 5.5.3.2 Japan
- 5.5.3.3 India
- 5.5.3.4 South Korea
- 5.5.3.5 Australia
- 5.5.3.6 Rest of Asia-Pacific
- 5.5.4 South America
- 5.5.4.1 Brazil
- 5.5.4.2 Argentina
- 5.5.4.3 Rest of South America
- 5.5.5 Middle East
- 5.5.5.1 Saudi Arabia
- 5.5.5.2 United Arab Emirates
- 5.5.5.3 Turkey
- 5.5.5.4 Rest of Middle East
- 5.5.6 Africa
- 5.5.6.1 South Africa
- 5.5.6.2 Nigeria
- 5.5.6.3 Rest of Africa
- 5.5.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as Available, Strategic Information, Market Rank/Share for Key Companies, Products and Services, and Recent Developments)
- 6.4.1 Crossbar Inc.
- 6.4.2 Panasonic Corporation
- 6.4.3 4DS Memory Limited
- 6.4.4 Adesto Technology Inc.
- 6.4.5 Micron Technology Inc.
- 6.4.6 Samsung Electronics Co. Ltd.
- 6.4.7 Sony Group Corporation
- 6.4.8 Western Digital Corporation
- 6.4.9 Knowm Inc.
- 6.4.10 Intel Corporation
- 6.4.11 IBM Corporation
- 6.4.12 SK hynix Inc.
- 6.4.13 Weebit Nano Ltd.
- 6.4.14 Fujitsu Limited
- 6.4.15 Toshiba Corporation
- 6.4.16 Honeywell International Inc.
- 6.4.17 Everspin Technologies Inc.
- 6.4.18 STMicroelectronics N.V.
- 6.4.19 Avalanche Technology Inc.
- 6.4.20 HP Inc.
- 6.4.21 Taiwan Semiconductor Manufacturing Company Limited
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-need Assessment

