PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2120351

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2120351
Ethyl Acetate - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
According to Mordor Intelligence, the ethyl acetate market size is projected to expand from 3.99 million tons in 2025 and 4.16 million tons in 2026 to 5.14 million tons by 2031, registering a CAGR of 4.32% between 2026 to 2031.
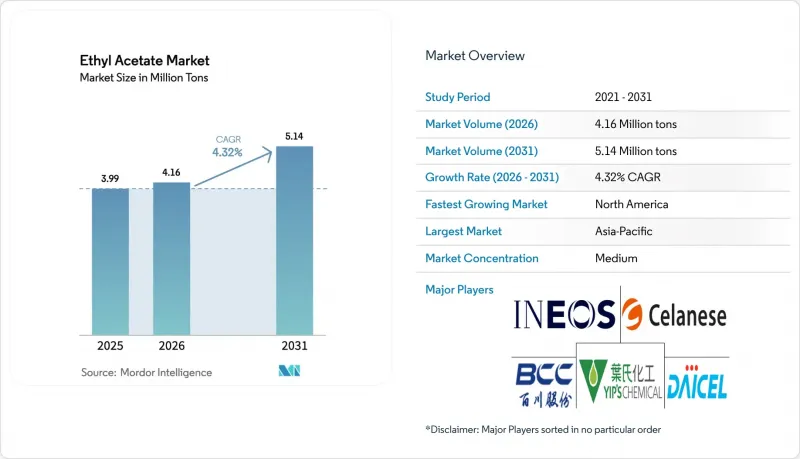
This report is Segmented by Source (Petro-Based and Bio-Based), Purity Grade (Industrial/Coatings Grade, Food Grade, and Pharmaceutical/GMP Grade), Application (Paints and Coatings, Flexible-Packaging Inks, and More), End-User Industry (Automotive, Artificial Leather, and More), and Geography (Asia-Pacific, North America, Europe, and More). The Market Forecasts are Provided in Terms of Volume (Tons).
Global Ethyl Acetate Market Trends and Insights
Rising Demand in Solvent Applications
Industrial solvent usage sets the baseline for ethyl acetate market growth as paints, coatings, adhesives, and general process applications consume large volumes. Architectural-coating recovery in North America and infrastructure spending in India and Southeast Asia keep bulk demand resilient. Eastman's Chemical Intermediates division reported a 15% sequential revenue jump in Q3 2024, citing higher acetyls availability after maintenance work and firmer selling prices, a signal that integrated producers are tightening supply-demand balances. E-commerce packaging expansion amplifies consumption of polyurethane and acrylic laminating adhesives, where ethyl acetate provides the primary solvent in multilayer films. Automotive refinish volumes are normalizing as vehicle fleets age, supporting additional solvent offtake in both North America and Europe. The progressive shift away from methyl ethyl ketone to ethyl acetate in certain coating formulations, driven by lower toxicity and regulatory acceptance, is adding incremental demand.
Growth of the Pharmaceutical Sector
Pharmaceutical manufacturing absorbs ethyl acetate as an extraction medium, reaction solvent, and chromatography eluent. GMP-grade specifications mandate single-site production, batch quarantine, and validated impurity profiling, which raise entry barriers and support premium pricing. India's generic-drug exports surpassed USD 50 billion in 2024, boosting demand for pharmaceutical-grade ethyl acetate in antibiotic purification, steroid extraction, and tablet-coating processes. FDA regulation 21 CFR 182.60 lists the solvent as GRAS, validating its use in excipients and taste-masking formulations under cGMP regimes. ICH Q3C residual-solvent testing keeps removal thresholds tight, sustaining sales of high-purity grades. Celanese's vertically integrated Kingsport, Tennessee complex supplies pharmaceutical customers with traceable, cGMP-compliant solvent, illustrating how feedstock control can secure a durable competitive edge.
Conversion to Water-Borne Adhesives in Europe
European packaging converters have steadily introduced water-borne systems to comply with stringent VOC ceilings. Germany and France have rolled out corporate sustainability frameworks that rank solvent reduction as a top priority, persuading adhesive formulators to trial water-borne or high-solids chemistries. Although solvent-borne lamination still dominates flexible packaging, especially where high bond strength and fast cure speed are critical, a gradual migration to water-borne technologies is under way in end-use cases such as label-stock assembly and certain carton-sealing lines. The learning curve involves adapting to longer drying times and higher energy consumption for water removal, which presently caps penetration rates. North American converters are monitoring European developments and could adopt similar specifications once regulatory pressure converges.
Other drivers and restraints analyzed in the detailed report include:
- EU Shift to Low-VOC Solvents Boosting Offset-Printing Inks
- Increasing Demand for Personal-Care Products
- Volatile Acetic-Acid Feedstock Prices in North America
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Petro-based maintained 90.23% of worldwide output in 2025 because entrenched Fischer-esterification assets enjoy scale and feedstock cost advantages. Nonetheless, bio-based is expanding at a 6.37% CAGR through 2031 as brand-owner net-zero mandates translate into purchase orders for ISCC PLUS and USDA-certified solvent grades. SEKAB's newly certified bio-acetic acid stream gives European coatings customers mass-balance documentation, while Viridis Chemical services North American buyers with 100% bio-based product. Godavari Biorefineries trimmed steam use to 2.5 tons per ton of solvent and upgraded sustainability credentials, which sharpens the cost curve for renewable supply.
Celanese launched its ECO-B line with up to 43% bio-content, expanding options for partial drop-in replacement in established petro-based chains. Although Asia-Pacific retains a price-centric procurement culture that favors petro-routes, European and North American policies are nurturing a differentiated niche that could account for double-digit percentage shares by 2031 if certification premiums stay inside historical bounds.
Industrial/coatings grade supplied 60.14% of global demand in 2025 and remains the workhorse for high-volume coatings, inks, and adhesives. The ethyl acetate market size attributable to pharmaceutical/GMP grade is however enlarging at a 5.36% clip thanks to API manufacturing growth in India and China. USP and Ph.Eur. assays above 99% purity, strict impurity limits, and batch traceability justify price uplifts that exceed 20% over industrial grades. Eastman's Longview operations illustrate best-practice with validated test methods, residual-solvent assays, and ISO-compliant documentation, all prerequisites for regulatory inspections.
Food-grade solvent fills a smaller but strategically important niche, covering coffee and tea decaffeination under FDA 21 CFR 173.228, with GRAS status reinforcing acceptability for flavor extraction. European rules under Directive 2009/32/EC echo this clearance. Future growth in food-grade demand rides on rising decaf coffee consumption in Asia-Pacific and the scaling of flavor extraction for plant-based proteins where solvent efficiency and recoverability matter.
Complete Report Scope:
- By Source
- Petro-based
- Bio-based
- By Purity Grade
- Industrial/Coatings Grade
- Food Grade
- Pharmaceutical/GMP Grade
- By Application
- Paints and Coatings
- Flexible-Packaging Inks
- Adhesives and Sealants
- Pigments and Dyes
- Process Solvents
- Other Applications (Flavor and Fragrance Enhancers, Inks)
- By End-user Industry
- Automotive
- Artificial Leather
- Food and Beverage
- Pharmaceuticals
- Other End-user Industries (Packaging)
- By Geography
- Asia-Pacific
- China
- India
- Japan
- South Korea
- ASEAN Countries
- Rest of Asia-Pacific
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- NORDIC Countries
- Rest of Europe
- South America
- Brazil
- Argentina
- Rest of South America
- Middle-East and Africa
- Saudi Arabia
- United Arab Emirates
- South Africa
- Nigeria
- Rest of Middle-East and Africa
- Asia-Pacific
Geography Analysis
Asia-Pacific accounted for 73.15% of 2025 tonnage thanks to China's gigantic 4.30 million-ton installed base and India's thriving API export industry. Despite chronic oversupply, regional consumption growth stays above 4% as infrastructure build-outs support coatings demand. North America records the fastest regional CAGR at 5.91% through 2031, a function of automotive supply-chain reshoring and new bio-based projects such as Viridis Chemical's Nebraska plant, which benefits from ISCC PLUS certification.
Europe grapples with margin pressure from water-borne adhesive uptake and heavy environmental compliance costs, yet offset-printing ink reformulation and pharmaceutical demand stabilize solvent pull. Middle-East producers face harsher economics; Sipchem's decision to idle its Saudi unit highlights how export-oriented plants struggle when Asian prices dip. South America and Africa post steady but modest gains, with investment concentrated in flexible-packaging converters serving regional food-processing industries.
- Celanese Corporation
- Daicel Corporation
- Eastman Chemical Company
- Godavari Biorefineries Ltd
- Greenfield Global Inc.
- INEOS
- Jiangsu Baichuan High-Tech New Materials Co., Ltd.
- Jiangsu SOPO (Group) Co. Ltd
- Jubilant Pharmova Ltd
- Laxmi Organic Industries Ltd.
- PetroChina Company Limited
- PT Pertamina (Persero)
- Resonac Holdings Corporation
- Sasol Ltd
- SEKAB
- Solvay
- Tokuyama Corporation
- Viridis Chemical, LLC
- Yip's Chemical Holdings Limited
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising Demand in Solvent Applications
- 4.2.2 Growth of the Pharmaceutical Sector
- 4.2.3 EU Shift to Low-VOC Solvents Boosting Offset-Printing Inks
- 4.2.4 Increasing Demand for Personal-Care Products
- 4.2.5 Net-Zero Roadmaps Accelerating Bio-Based Ethyl-Acetate Purchases
- 4.3 Market Restraints
- 4.3.1 Conversion To Water-Borne Adhesives in Europe
- 4.3.2 Volatile Acetic-Acid Feedstock Prices in North America
- 4.3.3 Global Oversupply from Recent Chinese Capacity Additions
- 4.4 Value Chain Analysis
- 4.5 Porter's Five Forces
- 4.5.1 Bargaining Power of Suppliers
- 4.5.2 Bargaining Power of Buyers
- 4.5.3 Threat of New Entrants
- 4.5.4 Threat of Substitutes
- 4.5.5 Degree of Competition
5 Market Size and Growth Forecasts (Volume)
- 5.1 By Source
- 5.1.1 Petro-based
- 5.1.2 Bio-based
- 5.2 By Purity Grade
- 5.2.1 Industrial/Coatings Grade
- 5.2.2 Food Grade
- 5.2.3 Pharmaceutical/GMP Grade
- 5.3 By Application
- 5.3.1 Paints and Coatings
- 5.3.2 Flexible-Packaging Inks
- 5.3.3 Adhesives and Sealants
- 5.3.4 Pigments and Dyes
- 5.3.5 Process Solvents
- 5.3.6 Other Applications (Flavor and Fragrance Enhancers, Inks)
- 5.4 By End-user Industry
- 5.4.1 Automotive
- 5.4.2 Artificial Leather
- 5.4.3 Food and Beverage
- 5.4.4 Pharmaceuticals
- 5.4.5 Other End-user Industries (Packaging)
- 5.5 By Geography
- 5.5.1 Asia-Pacific
- 5.5.1.1 China
- 5.5.1.2 India
- 5.5.1.3 Japan
- 5.5.1.4 South Korea
- 5.5.1.5 ASEAN Countries
- 5.5.1.6 Rest of Asia-Pacific
- 5.5.2 North America
- 5.5.2.1 United States
- 5.5.2.2 Canada
- 5.5.2.3 Mexico
- 5.5.3 Europe
- 5.5.3.1 Germany
- 5.5.3.2 United Kingdom
- 5.5.3.3 France
- 5.5.3.4 Italy
- 5.5.3.5 NORDIC Countries
- 5.5.3.6 Rest of Europe
- 5.5.4 South America
- 5.5.4.1 Brazil
- 5.5.4.2 Argentina
- 5.5.4.3 Rest of South America
- 5.5.5 Middle-East and Africa
- 5.5.5.1 Saudi Arabia
- 5.5.5.2 United Arab Emirates
- 5.5.5.3 South Africa
- 5.5.5.4 Nigeria
- 5.5.5.5 Rest of Middle-East and Africa
- 5.5.1 Asia-Pacific
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share (%)/Ranking Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Products and Services, and Recent Developments)
- 6.4.1 Celanese Corporation
- 6.4.2 Daicel Corporation
- 6.4.3 Eastman Chemical Company
- 6.4.4 Godavari Biorefineries Ltd
- 6.4.5 Greenfield Global Inc.
- 6.4.6 INEOS
- 6.4.7 Jiangsu Baichuan High-Tech New Materials Co., Ltd.
- 6.4.8 Jiangsu SOPO (Group) Co. Ltd
- 6.4.9 Jubilant Pharmova Ltd
- 6.4.10 Laxmi Organic Industries Ltd.
- 6.4.11 PetroChina Company Limited
- 6.4.12 PT Pertamina (Persero)
- 6.4.13 Resonac Holdings Corporation
- 6.4.14 Sasol Ltd
- 6.4.15 SEKAB
- 6.4.16 Solvay
- 6.4.17 Tokuyama Corporation
- 6.4.18 Viridis Chemical, LLC
- 6.4.19 Yip's Chemical Holdings Limited
7 Market Opportunities and Future Outlook
- 7.1 White-space and Unmet-need Assessment

