PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2120470

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2120470
Aseptic Packaging - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
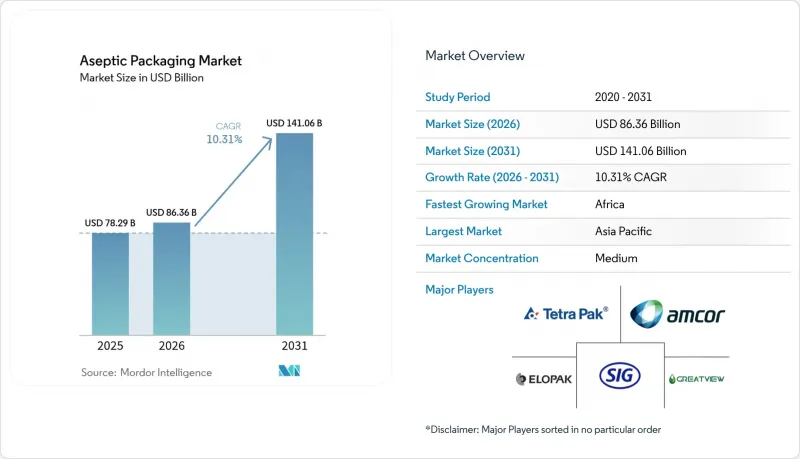
According to Mordor Intelligence, the aseptic packaging market size is expected to grow from USD 78.29 billion in 2025 to USD 86.36 billion in 2026 and is forecast to reach USD 141.06 billion by 2031 at a 10.31% CAGR over 2026-2031.
This report is Segmented by Product (Cartons, Bottles, Cans, Bags and Pouches, and More), Material Composition (Paper and Paperboard, Plastics, Glass, Metal, Composite Laminates), Application (Beverage, Food, Pharmaceuticals, and More), Filling Technology (Form-Fill-Seal (FFS), Blow-Fill-Seal (BFS), Injection Aseptic Filling, and More), and Geography. Market Forecasts are Provided in Terms of Value (USD).
Global Aseptic Packaging Market Trends and Insights
Rapid Growth of RTD Functional Beverages
Ready-to-drink shakes, probiotic drinks, and fortified plant-based milks are switching to ambient cartons and pouches, enabling national distribution without refrigeration. Brand examples such as protein beverages in North America cut logistics bills by roughly one-quarter when they moved from cold-chain to aseptic packaging. Capital spending reflects the shift, with functional beverage producers accounting for 40% of new carton-filler installations in 2025. Smaller entrants lean on co-packers that run aseptic pouches in lots of 10,000-25,000 units, accelerating flavor tests and limiting inventory exposure. Consumer willingness to pay premiums for claims linked to immunity, gut health, and recovery underpins the higher material cost of aseptic solutions.
Expansion of Ambient Dairy Distribution in Emerging Asia
Ultra-high-temperature milk and yogurt now reach rural consumers who lack reliable refrigeration. Indian cooperatives increased carton capacity by roughly one-fifth during 2024-2025 to penetrate tier-2 and tier-3 cities. Ambient formats reduce monsoon-season spoilage, stabilize demand, and earn modest price premiums over fresh milk while remaining affordable relative to imported powders. Government tax incentives for aseptic equipment in Indonesia and Vietnam sharpened the investment case, and multinational processors recorded double-digit growth from ambient dairy portfolios.
Volatility in Multilayer Polymer Prices
Swinging polyethylene and polypropylene prices shaved converter margins and forced quarterly price realignments with brand owners. Small converters in Africa and Latin America, lacking hedging options, absorbed the full cost shock, undermining competitiveness against imported pre-made pouches. Forward-looking suppliers are investing in recycled-resin streams to secure feedstock, yet recycled polyethylene currently trades at a noticeable premium over virgin grades, limiting near-term relief.
Other drivers and restraints analyzed in the detailed report include:
- Stringent Food-Safety Regulations Pushing Sterile Packaging Adoption
- Inflation-Linked Shift from Cold-Chain to Shelf-Stable Logistics
- High Initial CAPEX for Aseptic Filling Lines
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Bags and pouches are projected to deliver an 11.31% CAGR through 2031, the swiftest among formats, as direct-to-consumer beverage and sauce brands need lightweight packs that suit digital graphics. Cartons retained 43.56% of revenue in 2025, yet their growth rate moderates as retailers reward pouches with 20-30% warehouse cube savings. Bottles continue to serve premium coffees and probiotic drinks that justify higher pack costs, while cans cater to energy cocktails, leveraging metal's barrier and recyclability.
Cost and branding factors underpin the pouch trajectory. Each flexible pack reduces shipping weight by close to half versus a similar-volume carton, translating to lower freight emissions, an advantage spotlighted by retailers with sustainability scorecards. Digital press advances now permit full-color artwork for runs of fewer than 50,000 pieces, avoiding plate fees that historically handicapped small-batch cartons. Cans and bottles still dominate cafe or gym channels where resealability and perceived quality matter, yet resealable spouted pouches are narrowing that functional gap, indicating continued share migration toward flexibles in the aseptic packaging market.
Paper and paperboard accounted for 47.13% of revenue in 2025, reflecting carton dominance in dairy and juice, yet composite laminates are on track for an 11.39% CAGR as converters stack polyethylene and ethylene-vinyl-alcohol layers to achieve foil-barrier performance while meeting recyclability rules. Plastics have broad utility across pouches and bottles, while glass remains niche in ultra-premium cold brews, and metal focuses on energy drinks.
Innovation in laminate structures is reducing reliance on aluminum foil. Amcor's polyethylene plus silicon oxide laminate achieves sub-0.5 cc oxygen transmission with 20% less weight. The European Union's 2030 recyclability targets are steering converters toward mono-material solutions, particularly polyethylene. These shifts suggest composite structures will continue to displace foil-lined cartons across the aseptic packaging market, especially in regions with active extended producer responsibility schemes.
Complete Report Scope:
- By Product
- Cartons
- Bottles
- Cans
- Bags and Pouches
- Vials and Ampoules
- By Material Composition
- Paper and Paperboard
- Plastics (PP, PE, PET)
- Glass
- Metal (Aluminum, Steel)
- Composite Laminates
- By Application
- Beverage
- Ready-to-Drink (RTD) Beverages
- Dairy-Based Beverages
- Food
- Processed Food
- Fruits and Vegetables
- Dairy Food
- Pharmaceuticals
- Personal Care and Cosmetics
- Beverage
- By Filling Technology
- Form-Fill-Seal (FFS)
- Blow-Fill-Seal (BFS)
- Injection Aseptic Filling
- Rotary Aseptic Filling
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- United Kingdom
- Germany
- France
- Italy
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- Rest of Asia Pacific
- Middle East and Africa
- Middle East
- United Arab Emirates
- Saudi Arabia
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Egypt
- Rest of Africa
- Middle East
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
Asia Pacific accounted for 35.67% of global revenue in 2025, led by expanding dairy demand in India and the growth of ready-to-drink tea in China. Ultra-high-temperature milk in India grew at double-digit rates as ambient packs reached tier-2 cities without reliable refrigeration. Japan and South Korea show premium uptakes in single-serve yogurts, while Southeast Asian startups adopt pouches to penetrate rural channels.
From 2026 to 2031, Africa is projected to witness a robust CAGR of 11.34%. In Nigeria, Kenya, and South Africa, soaring diesel and grid-power expenses are rendering cold chain operations economically unfeasible. As a result, dairy cooperatives and juice processors in these nations are shifting their focus towards shelf-stable product formats. While local production of cartons and pouches is still in its infancy, leading to heightened landed-cost pressures, multinational corporations are proactively forging partnerships with regional converters, aiming to bolster local supply chains.
Europe and North America grow more slowly yet drive sustainability mandates. The EU's Packaging and Packaging Waste Regulation is accelerating the adoption of mono-material laminates. North America's growth clusters around functional drinks and sterile biologic fills, while Latin America balances currency volatility against strong demand for ambient dairy. The Middle East offers opportunities in Saudi Arabia and the United Arab Emirates, where high ambient temperatures naturally favor the aseptic packaging market.
- Tetra Pak International SA
- SIG Combibloc Group
- Amcor PLC
- Elopak ASA
- IPI SRL (Coesia Group)
- DS Smith PLC
- Smurfit Kappa Group
- Mondi PLC
- Uflex Limited
- Schott AG
- Gerresheimer AG
- Toyo Seikan Group
- CDF Corporation
- BIBP Sp. z o.o.
- Nampak Ltd
- Greatview Aseptic Packaging
- OPLATEK Group
- Sealed Air Corporation
- ProAmpac Holdings Inc.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Industry Value Chain Analysis
- 4.3 Market Drivers
- 4.3.1 Rapid Growth of RTD Functional Beverages
- 4.3.2 Expansion of Ambient Dairy Distribution in Emerging Asia
- 4.3.3 Stringent Food-Safety Regulations Pushing Sterile Packaging Adoption
- 4.3.4 Inflation-Linked Shift from Cold-Chain to Shelf-Stable Logistics
- 4.3.5 Shift Toward Sustainable, Lightweight Packaging Mandates
- 4.3.6 Rise of Digital-Print-Enabled Short SKUs for D2C Brands
- 4.4 Market Restraints
- 4.4.1 Volatility in Multilayer Polymer Prices
- 4.4.2 High Initial CAPEX for Aseptic Filling Lines
- 4.4.3 Limited Recycling Infrastructure for Aluminum-Foil Laminates
- 4.4.4 Regulatory Uncertainty Around PFAS Barrier Coatings
- 4.5 Impact of Macroeconomic Factors on the Market
- 4.6 Regulatory Landscape
- 4.7 Technological Outlook
- 4.8 Porter's Five Forces Analysis
- 4.8.1 Bargaining Power of Suppliers
- 4.8.2 Bargaining Power of Buyers
- 4.8.3 Threat of New Entrants
- 4.8.4 Threat of Substitutes
- 4.8.5 Intensity of Competitive Rivalry
- 4.9 Pricing Analysis
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Product
- 5.1.1 Cartons
- 5.1.2 Bottles
- 5.1.3 Cans
- 5.1.4 Bags and Pouches
- 5.1.5 Vials and Ampoules
- 5.2 By Material Composition
- 5.2.1 Paper and Paperboard
- 5.2.2 Plastics (PP, PE, PET)
- 5.2.3 Glass
- 5.2.4 Metal (Aluminum, Steel)
- 5.2.5 Composite Laminates
- 5.3 By Application
- 5.3.1 Beverage
- 5.3.1.1 Ready-to-Drink (RTD) Beverages
- 5.3.1.2 Dairy-Based Beverages
- 5.3.2 Food
- 5.3.2.1 Processed Food
- 5.3.2.2 Fruits and Vegetables
- 5.3.2.3 Dairy Food
- 5.3.3 Pharmaceuticals
- 5.3.4 Personal Care and Cosmetics
- 5.3.1 Beverage
- 5.4 By Filling Technology
- 5.4.1 Form-Fill-Seal (FFS)
- 5.4.2 Blow-Fill-Seal (BFS)
- 5.4.3 Injection Aseptic Filling
- 5.4.4 Rotary Aseptic Filling
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 Europe
- 5.5.2.1 United Kingdom
- 5.5.2.2 Germany
- 5.5.2.3 France
- 5.5.2.4 Italy
- 5.5.2.5 Rest of Europe
- 5.5.3 Asia Pacific
- 5.5.3.1 China
- 5.5.3.2 Japan
- 5.5.3.3 India
- 5.5.3.4 South Korea
- 5.5.3.5 Rest of Asia Pacific
- 5.5.4 Middle East and Africa
- 5.5.4.1 Middle East
- 5.5.4.1.1 United Arab Emirates
- 5.5.4.1.2 Saudi Arabia
- 5.5.4.1.3 Turkey
- 5.5.4.1.4 Rest of Middle East
- 5.5.4.2 Africa
- 5.5.4.2.1 South Africa
- 5.5.4.2.2 Egypt
- 5.5.4.2.3 Rest of Africa
- 5.5.4.1 Middle East
- 5.5.5 South America
- 5.5.5.1 Brazil
- 5.5.5.2 Argentina
- 5.5.5.3 Rest of South America
- 5.5.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as Available, Strategic Information, Market Rank/Share for Key Companies, Products and Services, and Recent Developments)
- 6.4.1 Tetra Pak International SA
- 6.4.2 SIG Combibloc Group
- 6.4.3 Amcor PLC
- 6.4.4 Elopak ASA
- 6.4.5 IPI SRL (Coesia Group)
- 6.4.6 DS Smith PLC
- 6.4.7 Smurfit Kappa Group
- 6.4.8 Mondi PLC
- 6.4.9 Uflex Limited
- 6.4.10 Schott AG
- 6.4.11 Gerresheimer AG
- 6.4.12 Toyo Seikan Group
- 6.4.13 CDF Corporation
- 6.4.14 BIBP Sp. z o.o.
- 6.4.15 Nampak Ltd
- 6.4.16 Greatview Aseptic Packaging
- 6.4.17 OPLATEK Group
- 6.4.18 Sealed Air Corporation
- 6.4.19 ProAmpac Holdings Inc.
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment

