PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2120618

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2120618
North America Protective Packaging - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
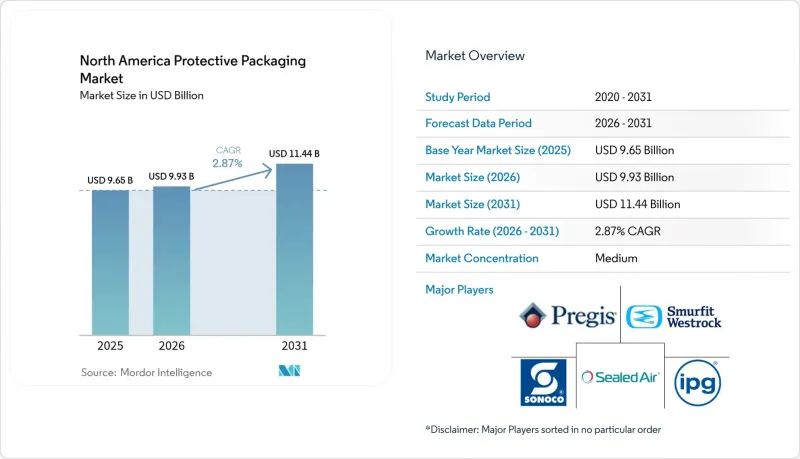
According to Mordor Intelligence, the North America protective packaging market size is expected to grow from USD 9.65 billion in 2025 to USD 9.93 billion in 2026 and is forecast to reach USD 11.44 billion by 2031 at 2.87% CAGR over 2026-2031.
This report is Segmented by Material Type (Paper, Plastics, Foam, and Bio-Based), Product Type (Rigid, Flexible, and Foam), Functionality (Cushioning, Void Fill, and Insulation), End-User (Food, Industrial, Pharma, Electronics, E-Commerce), Technology (Inflatable, Molded Pulp, and Insulated Containers), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
North America Protective Packaging Market Trends and Insights
E-commerce boom and parcel-volume growth
Surging parcel volumes continue to redefine protective packaging market requirements. Automated fulfillment centers rely on pre-formed mailers and air pillows that cut packing time by up to 40%, keeping pace with same-day delivery promises. Sealed Air reported robust e-commerce sales in 2024, attributing growth to automation-ready solutions that integrate seamlessly with high-speed lines. Retailers, however, increasingly deploy cube-optimization software that trims excess void, reducing material intensity even as shipment counts climb. This duality sustains volume growth for automation-compatible formats while capping runaway tonnage gains for traditional void-fill.
Shift toward sustainable and recycled materials
Sustainability commitments from multinationals accelerate the adoption of fiber-based and compostable solutions despite cost premiums. Nestle earmarked EUR 1.5 billion (USD 1.6 billion) for sustainable packaging through 2025, funneling funds toward bio-based cushioning and molded-pulp inserts. Health Canada's single-use plastics prohibition, effective December 2024, eliminates several fossil-based formats, prompting rapid material substitution across North American supply chains. Despite 20-25% cost premiums, brand-owner ESG targets and consumer preference shifts underpin a steady pipeline of plant-derived films, starch loose-fill, and mycelium cushioning.
Stringent regulations on single-use plastics and degradability
Health Canada's prohibition eliminates checkout bags, cutlery, and defined packaging types, forcing rapid reformulation and significant R&D outlays for converters. Simultaneously, the U.S. EPA proposed limits on PFAS in food-contact coatings, removing conventional fluoropolymer barriers from the protective packaging toolbox. Compliance spending already absorbs 8-12% of development budgets, and uncertainty over enforcement timelines postpones investment in alternative chemistries.
Other drivers and restraints analyzed in the detailed report include:
- Cold-chain expansion in food and pharma
- Dim-weight freight rules favoring light flexible formats
- Volatile resin and fiber prices
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Plastics secured 51.45% of 2025 revenue and remain indispensable for moisture and puncture barriers in the protective packaging market. However, the bio-based segment advances at a 5.49% CAGR, reflecting regulatory pressure and corporate ESG targets. The protective packaging industry logged a 35% rise in USPTO patent filings for PHA films and mycelium foams, signaling R&D momentum. Producers channel capex toward scalable compostable resins even as price premiums persist.
Paper and molded-fiber alternatives benefit from recyclability perceptions, though fiber price volatility narrows cost advantages. Foam plastics face scrutiny for disposal challenges yet retain irreplaceable insulation properties for fragile or temperature-sensitive loads. The protective packaging market is increasingly split into high-performance polymer applications and sustainability-driven fiber or compostable niches, with converters like Sealed Air earmarking USD 150 million for circular-material development.
Flexible mailers, bubble wrap, and air pillows captured 46.12% of 2025 revenue as e-commerce shippers chase lightweight, automation-friendly options. Dim-weight freight economics amplify this edge, reinforcing demand for low-cube solutions. Foam regained momentum through pharmaceutical cold-chain expansion, registering the highest 4.38% CAGR outlook to 2031. Pfizer's USD 2 billion cold-chain push underscores durable insulation demand for biologics.
Rigid corrugated inserts persist in industrial supply chains, while molded pulp gains share in electronics as OEMs swap EPS for fiber to meet recycling mandates. The protective packaging market sees discretionary upgrades toward smart variants embedding temperature sensors, QR tracking, and tamper evidence, enabling converters to upsell performance without proportionate material increases.
Complete Report Scope:
- By Material Type
- Paper and Paperboard
- Plastics
- Foam Plastics
- Bio-based and Compostable Materials
- By Product Type
- Rigid
- Corrugated Paperboard Protectors
- Molded Pulp
- Insulated Shipping Containers
- Flexible
- Protective Mailers
- Bubble Wraps
- Air Pillows/Air Bags
- Paper Fill
- Foam
- Molded Foam
- Foam-in-Place (FIP)
- Loose Fill
- Foam Rolls/Sheets
- Rigid
- By Functionality
- Cushioning
- Blocking and Bracing
- Void Fill
- Insulation
- Wrapping and Surface Protection
- Other Functionalities
- By End-user Vertical
- Food and Beverage
- Industrial
- Pharmaceuticals
- Consumer Electronics
- Cosmetics and Home Care
- E-commerce and Logistics
- Other End-user Verticals
- By Packaging Technology
- Inflatable Packaging Systems
- Molded Pulp and Fiber-based Systems
- Suspension and Retention Packaging
- Insulated Shipping Containers
- Dunnage and Layer Pads
- Honeycomb Paper Solutions
- By Country
- United States
- Canada
- Mexico
List of Companies Covered in this Report:
- Sealed Air Corporation
- Pregis LLC
- Sonoco Products Company
- Intertape Polymer Group Inc.
- Smurfit WestRock
- International Paper Company
- Amcor plc
- Storopack Hans Reichenecker GmbH
- Huhtamaki Oyj
- UFP Technologies, Inc.
- Ranpak Holdings Corp.
- Pro-Pac Packaging Limited
- 3M Company
- Mondi plc
- Veritiv Corporation
- ProAmpac LLC
- Dow Inc.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 E-commerce boom and parcel-volume growth
- 4.2.2 Shift toward sustainable and recycled materials
- 4.2.3 Cold-chain expansion in food and pharma
- 4.2.4 Dim-weight freight rules favoring light flexible formats
- 4.2.5 Reverse-logistics uptick demanding re-usable protection
- 4.2.6 On-site AI-driven packaging automation at fulfilment hubs
- 4.3 Market Restraints
- 4.3.1 Stringent regulations on single-use plastics and degradability
- 4.3.2 Volatile resin and fiber prices
- 4.3.3 Warehouse cube-optimization reducing void-fill volumes
- 4.3.4 High CAPEX for smart-packaging machinery
- 4.4 Industry Value Chain Analysis
- 4.5 Porter's Five Forces Analysis
- 4.5.1 Bargaining Power of Suppliers
- 4.5.1.1 Bargaining Power of Buyers
- 4.5.1.2 Threat of New Entrants
- 4.5.1.3 Threat of Substitutes
- 4.5.1.4 Intensity of Competitive Rivalry
- 4.5.1 Bargaining Power of Suppliers
- 4.6 The Impact of Macroeconomic Factors on the Market
- 4.7 Regulatory Landscape
- 4.8 Technological Outlook
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Material Type
- 5.1.1 Paper and Paperboard
- 5.1.2 Plastics
- 5.1.3 Foam Plastics
- 5.1.4 Bio-based and Compostable Materials
- 5.2 By Product Type
- 5.2.1 Rigid
- 5.2.1.1 Corrugated Paperboard Protectors
- 5.2.1.2 Molded Pulp
- 5.2.1.3 Insulated Shipping Containers
- 5.2.2 Flexible
- 5.2.2.1 Protective Mailers
- 5.2.2.2 Bubble Wraps
- 5.2.2.3 Air Pillows/Air Bags
- 5.2.2.4 Paper Fill
- 5.2.3 Foam
- 5.2.3.1 Molded Foam
- 5.2.3.2 Foam-in-Place (FIP)
- 5.2.3.3 Loose Fill
- 5.2.3.4 Foam Rolls/Sheets
- 5.2.1 Rigid
- 5.3 By Functionality
- 5.3.1 Cushioning
- 5.3.2 Blocking and Bracing
- 5.3.3 Void Fill
- 5.3.4 Insulation
- 5.3.5 Wrapping and Surface Protection
- 5.3.6 Other Functionalities
- 5.4 By End-user Vertical
- 5.4.1 Food and Beverage
- 5.4.2 Industrial
- 5.4.3 Pharmaceuticals
- 5.4.4 Consumer Electronics
- 5.4.5 Cosmetics and Home Care
- 5.4.6 E-commerce and Logistics
- 5.4.7 Other End-user Verticals
- 5.5 By Packaging Technology
- 5.5.1 Inflatable Packaging Systems
- 5.5.2 Molded Pulp and Fiber-based Systems
- 5.5.3 Suspension and Retention Packaging
- 5.5.4 Insulated Shipping Containers
- 5.5.5 Dunnage and Layer Pads
- 5.5.6 Honeycomb Paper Solutions
- 5.6 By Country
- 5.6.1 United States
- 5.6.2 Canada
- 5.6.3 Mexico
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 Sealed Air Corporation
- 6.4.2 Pregis LLC
- 6.4.3 Sonoco Products Company
- 6.4.4 Intertape Polymer Group Inc.
- 6.4.5 Smurfit WestRock
- 6.4.6 International Paper Company
- 6.4.7 Amcor plc
- 6.4.8 Storopack Hans Reichenecker GmbH
- 6.4.9 Huhtamaki Oyj
- 6.4.10 UFP Technologies, Inc.
- 6.4.11 Ranpak Holdings Corp.
- 6.4.12 Pro-Pac Packaging Limited
- 6.4.13 3M Company
- 6.4.14 Mondi plc
- 6.4.15 Veritiv Corporation
- 6.4.16 ProAmpac LLC
- 6.4.17 Dow Inc.
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-Need Assessment

