PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2187201

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2187201
Acetic Acid - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2027 - 2032)
According to Mordor Intelligence, the acetic acid market size is expected to grow from 21.46 million tons in 2026 to 22.45 million tons in 2027 and is forecast to reach 27.78 million tons by 2032 at 4.35% CAGR over 2027-2032.
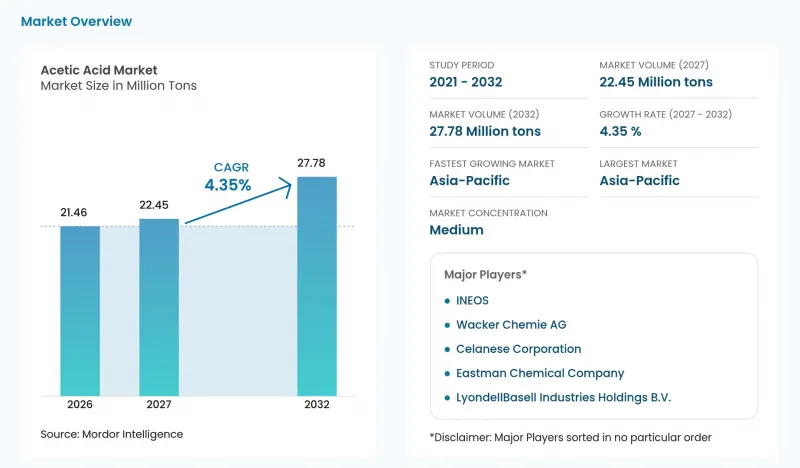
This report is segmented by Derivative (Vinyl Acetate Monomer, Purified Terephthalic Acid, and more), Production Route (Methanol Carbonylation, Ethylene Oxidation, and more), Application (Adhesives, Paints and Coatings, Medical, and more), and Geography (Asia-Pacific, North America, and more). The market forecasts are provided in terms of volume (tons), based on availability.
Global Acetic Acid Market Trends and Insights
Surging Vinyl Acetate Monomer Demand
Vinyl acetate monomer (VAM) demand connects acetic acid suppliers with both an established consumption base and expansions in downstream polymer production. China's apparent VAM consumption was about 2.93 million metric tons in 2025, according to China Chemical Economic and Technical Development Center data cited by Jiangsu SOPO. In 2026, Sinopec subsidiary Chongqing Chuanwei Chemical started up a specialty polyvinyl alcohol (PVA) resin unit in China with annual capacity of 50,000 metric tons. VAM is used to manufacture PVA, whose applications include adhesives, coatings and water-soluble packaging films. The unit produced qualified product and shipped its first batch to Europe, linking its VAM-derived production requirements to export customers as well as China's domestic consumption base.
Steady PTA Capacity Additions in Asia
Purified terephthalic acid (PTA) project commissioning creates a concrete downstream production opportunity for acetic acid suppliers serving Asian industrial customers. In August 2025, Jiangsu Hailun Petrochemical put a PTA technical-upgrade and expansion project into operation in Jiangyin, Jiangsu, China. The project had annual capacity of 3.2 million metric tons, and its operator is a subsidiary of Jiangsu Sanfame Polyester Material. Celanese's 2025 annual report identifies acetic acid as primarily used to manufacture VAM, PTA and other acetyl derivatives. The commercial benefit comes from serving the project's acetic acid requirements, with independent producers needing an agreed supply role to translate the downstream expansion into their own sales.
Volatile Methanol Feedstock Pricing
Methanol-price variation makes the relationship between feedstock costs and acid selling prices a constraint on expansion economics. Gujarat Narmada Valley Fertilizers & Chemicals Limited (GNFC) showed methanol prices varying from FY 2021-22 through FY 2025-26 alongside acetic acid prices in its company-specific Indian feedstock-spread chart. Methanex's average realized methanol selling price rose to USD 361 per metric ton in 2025 from USD 355 per metric ton in 2024. Its 2025 annual report characterized methanol prices as historically volatile and cyclical and expected that pattern to continue. GNFC also lists methanol production, so part of its methanol cost may reflect captive supply rather than external purchases. Higher methanol costs can absorb an acid-price gain, leaving externally sourced production exposed even when acid selling prices rise.
Other drivers and restraints analyzed in the detailed report include:
- Expansion of Acetate-Ester Solvents in High-Solids Coatings
- Bio-Based Acetic Acid Pathways Scaling Under Net-Zero Mandates
- Anti-Dumping and Tariff Actions on Chinese Exports
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Vinyl acetate monomer (VAM) accounted for a 27.31% share of the acetic acid market size in 2026. Japan produced 444,939 metric tons of VAM in 2025. That national output illustrates an operating Japanese manufacturing base that requires acid feedstock as derivative production occurs. Acid suppliers serving those Japanese VAM producers therefore have a recurring feedstock-supply role tied to operating output, extending the opportunity beyond initial plant commissioning.
Purified terephthalic acid (PTA) is forecast to be the fastest-growing derivative segment, at a 4.75% CAGR over 2027-2032. Separation-technology supplier Sulzer describes PTA production as p-xylene oxidation in acetic acid, followed by solvent recovery that separates acetic acid from reaction water. SASA commissioned its PTA plant in Turkiye in the first quarter of 2025 with annual production capacity of 1.75 million metric tons. The investment completed a vertical integration step in SASA's polyester production chain. The oxidation-solvent and recovery steps make acid handling and separation part of process design for an integrated PTA plant such as SASA's.
Complete Report Scope:
- By Derivative
- Vinyl Acetate Monomer (VAM)
- Purified Terephthalic Acid (PTA)
- Ethyl Acetate
- Acetic Anhydride
- Other Derivatives
- By Production Route
- Methanol Carbonylation
- Acetaldehyde Oxidation
- Ethylene Oxidation
- Bio-based Fermentation
- By Application
- Adhesives, Paints and Coatings
- Plastics and Polymers
- Food and Beverage
- Textile
- Medical
- Other Applications
- By Geography
- Asia-Pacific
- China
- India
- Japan
- South Korea
- ASEAN Countries
- Rest of Asia-Pacific
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- NORDIC Countries
- Rest of Europe
- South America
- Brazil
- Argentina
- Rest of South America
- Middle-East and Africa
- Saudi Arabia
- South Africa
- Rest of Middle-East and Africa
- Asia-Pacific
Geography Analysis
Asia-Pacific accounted for 69.56% of the acetic acid market size in 2026 and is forecast to grow at a 4.95% CAGR over 2027-2032, making it the largest and fastest-growing geography. Handsome Chemical commissioned a 600,000-metric-ton acetic acid plant in Jingmen, Hubei, China, in May 2025. Handsome Chemical's plant was scheduled for gradual capacity release in the second half of 2025, according to Yip's Chemical Holdings, which reported a 24% effective stake in the producer. Yip's described Handsome Chemical as the world's largest acetate solvents company and reported planned simultaneous release of 600,000 metric tons of acetate capacity, pairing the acid expansion with the producer's downstream manufacturing.
North America's feedstock integration is illustrated by Celanese's Clear Lake, Texas, methanol joint venture with Mitsui, in which Celanese owns 50%. Celanese reported that its share of Fairway Methanol production and a long-term Mitsui contract met almost all its North American methanol needs in 2025. Europe faced production-cost pressure as INEOS announced on September 22, 2026, that it would mothball all 3 Hull Acetyls units until further notice because of uncompetitive energy costs. At that date, 2 units had ceased production and the third was due to stop within days. Mothballing the units INEOS described as Europe's last remaining world-scale Acetyls facilities would remove that local scale option for European buyers for the shutdown's duration.
In South America's other markets, the European Commission identified Sucroal S.A. as Colombia's sole acetic-acid producer in its September 2025 ruling. Elsewhere in Europe, the Netherlands recorded gross acetic acid imports of 51,896.2 metric tons from the world in 2025, illustrating an import channel within the region. In Asia-Pacific's other markets, Pakistan's Noventra Limited (formerly LOTTE Chemical Pakistan Ltd.) uses acetic acid as the solvent in paraxylene oxidation to produce PTA. Within Middle-East and Africa's other markets, Egypt reported gross acetic acid exports of 9.98 metric tons to the world in 2025. Under that Colombian supply structure, switching to another producer would mean sourcing beyond domestic production.
- Celanese Corporation
- Daicel Corporation
- Eastman Chemical Company
- Gujarat Narmada Valley Fertilizers & Chemicals Limited
- INEOS
- Jiangsu SOPO (Group) Co., Ltd.
- Kingboard Holdings
- LyondellBasell Industries Holdings B.V.
- Mitsubishi Chemical Corporation
- PetroChina Company Limited
- SABIC
- Sekab
- Shandong Hualu Hengsheng Chemical Co., Ltd.
- Shanghai Huayi Energy Chemical Co., Ltd.
- Sipchem Company
- Tanfac Industries Ltd
- Wacker Chemie AG
- Yankuang Energy Group Company Limited
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Surging Vinyl Acetate Monomer Demand
- 4.2.2 Steady PTA Capacity Additions in Asia
- 4.2.3 Expansion of Acetate-Ester Solvents in High-Solids Coatings
- 4.2.4 Bio-Based Acetic Acid Pathways Scaling Under Net-Zero Mandates
- 4.2.5 CO2-to-Acetic Acid Electrosynthesis Pilots
- 4.3 Market Restraints
- 4.3.1 Volatile Methanol Feedstock Pricing
- 4.3.2 Anti-Dumping and Tariff Actions on Chinese Exports
- 4.3.3 Rhodium/Iridium Catalyst Supply Risk
- 4.4 Industry Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Suppliers
- 4.7.3 Bargaining Power of Buyers
- 4.7.4 Threat of Substitutes
- 4.7.5 Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VOLUME)
- 5.1 By Derivative
- 5.1.1 Vinyl Acetate Monomer (VAM)
- 5.1.2 Purified Terephthalic Acid (PTA)
- 5.1.3 Ethyl Acetate
- 5.1.4 Acetic Anhydride
- 5.1.5 Other Derivatives
- 5.2 By Production Route
- 5.2.1 Methanol Carbonylation
- 5.2.2 Acetaldehyde Oxidation
- 5.2.3 Ethylene Oxidation
- 5.2.4 Bio-based Fermentation
- 5.3 By Application
- 5.3.1 Adhesives, Paints and Coatings
- 5.3.2 Plastics and Polymers
- 5.3.3 Food and Beverage
- 5.3.4 Textile
- 5.3.5 Medical
- 5.3.6 Other Applications
- 5.4 By Geography
- 5.4.1 Asia-Pacific
- 5.4.1.1 China
- 5.4.1.2 India
- 5.4.1.3 Japan
- 5.4.1.4 South Korea
- 5.4.1.5 ASEAN Countries
- 5.4.1.6 Rest of Asia-Pacific
- 5.4.2 North America
- 5.4.2.1 United States
- 5.4.2.2 Canada
- 5.4.2.3 Mexico
- 5.4.3 Europe
- 5.4.3.1 Germany
- 5.4.3.2 United Kingdom
- 5.4.3.3 France
- 5.4.3.4 Italy
- 5.4.3.5 NORDIC Countries
- 5.4.3.6 Rest of Europe
- 5.4.4 South America
- 5.4.4.1 Brazil
- 5.4.4.2 Argentina
- 5.4.4.3 Rest of South America
- 5.4.5 Middle-East and Africa
- 5.4.5.1 Saudi Arabia
- 5.4.5.2 South Africa
- 5.4.5.3 Rest of Middle-East and Africa
- 5.4.1 Asia-Pacific
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 Celanese Corporation
- 6.4.2 Daicel Corporation
- 6.4.3 Eastman Chemical Company
- 6.4.4 Gujarat Narmada Valley Fertilizers & Chemicals Limited
- 6.4.5 INEOS
- 6.4.6 Jiangsu SOPO (Group) Co., Ltd.
- 6.4.7 Kingboard Holdings
- 6.4.8 LyondellBasell Industries Holdings B.V.
- 6.4.9 Mitsubishi Chemical Corporation
- 6.4.10 PetroChina Company Limited
- 6.4.11 SABIC
- 6.4.12 Sekab
- 6.4.13 Shandong Hualu Hengsheng Chemical Co., Ltd.
- 6.4.14 Shanghai Huayi Energy Chemical Co., Ltd.
- 6.4.15 Sipchem Company
- 6.4.16 Tanfac Industries Ltd
- 6.4.17 Wacker Chemie AG
- 6.4.18 Yankuang Energy Group Company Limited
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment

