PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2121737

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2121737
Neuromorphic Chip - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
According to Mordor Intelligence, the neuromorphic chip market size is projected to expand from USD 0.34 billion in 2025 and USD 0.51 billion in 2026 to USD 4.08 billion by 2031, registering a CAGR of 51.57% between 2026 to 2031.
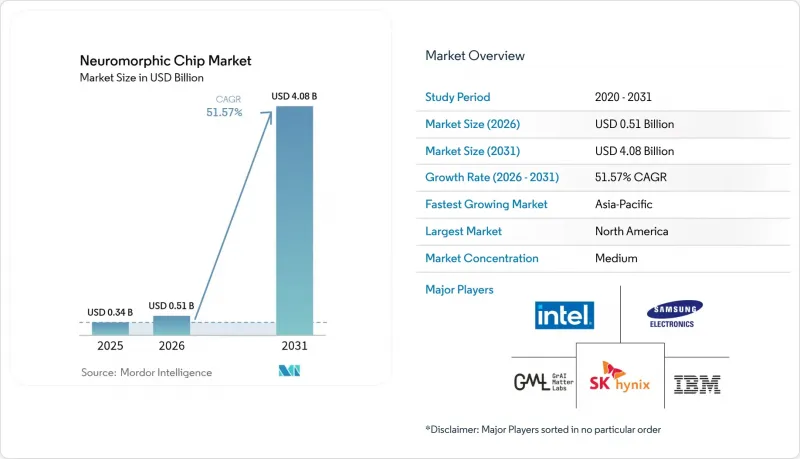
This report is Segmented by Chip Type (Analog, Digital, Mixed-Signal), Architecture (Spiking Neural Network, ReRAM-Based Architectures, Phase-Change-Memory Architectures), End-User Industry (Automotive (ADAS / AV), Consumer Electronics, Aerospace and Defense, and More), Deployment Model (Edge Devices, and Data-Centre / Cloud), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global Neuromorphic Chip Market Trends and Insights
Rising Edge AI Demand in Consumer and Automotive
Smartphone and wearable brands now embed always-on inference engines to enable voice wake-words, gesture control, and wellness analytics without draining batteries. Qualcomm's Snapdragon platforms integrate event-driven neural engines that maintain real-time responsiveness at 10 milliwatts or less, setting a benchmark that traditional DSPs cannot reach. Automotive suppliers are redesigning domain controllers around spiking neural networks that fuse radar, lidar, and camera streams with sub-10-millisecond latency. BrainChip's Akida core meets ISO 26262 functional-safety targets in in-cabin monitoring, proving that the neuromorphic chip market can satisfy both compute and safety requirements. As vehicles transition toward software-defined architectures, over-the-air updates intensify demand for re-configurable, ultra-low-power accelerators.
Datacenter Energy Crisis Favoring Ultra-Low-Power Compute
Large language model training already consumes megawatt-hours, and inference volumes grow even faster. Intel Laboratories showed that analog in-memory compute reduces multiply-accumulate energy by three orders of magnitude. IBM phase-change prototypes run synaptic operations at 10 picojoules, enabling petaflop-class racks within 1 kilowatt budgets. Regulatory pressure through voluntary carbon disclosure and efficiency certifications nudges operators toward chips that minimize joules per inference. As electricity rates rise and renewable-energy quotas tighten, data centers view the neuromorphic chip market as a direct path to capex savings in power and cooling infrastructure.
Immature Software and Toolchain Ecosystem
Enterprises encounter fragmented frameworks in which converting a convolutional network into spikes requires manual tuning of time constants and encoders, often degrading accuracy. Intel Lava and BrainChip MetaTF ease migration, yet neither supports the full layer diversity data scientists expect. The absence of benchmarks means vendors publish power claims under different workloads, complicating ROI analysis. Development teams must maintain parallel codebases for GPUs and neuromorphic targets, which stretch budgets and extend project timelines. This gap slows procurement and dampens initial enthusiasm inside otherwise receptive organizations.
Other drivers and restraints analyzed in the detailed report include:
- Government Brain-Inspired R&D Programs
- Expansion of Autonomous Vehicle Domain Controller Architectures
- Fabrication Variability of Analog NVM
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Mixed-signal devices are forecast to grow at 52.19%, beating the 51.57% baseline. In 2025, digital processors held a 43.56% share of the neuromorphic chip market, reflecting corporate comfort with deterministic control and rich software stacks. Intel Loihi 2 packs 1 billion synapses in a fully asynchronous digital mesh programmable through Python. Analog crossbars deliver a 100-fold energy edge but struggle with device drift. Mixed-signal chips layer digital control on analog synapses, harvesting the bulk of the efficiency without surrendering programmability. The segment thrives on mature 28-nanometer nodes that cost less to tape-out, giving startups a capital-light path to silicon.
The neuromorphic chip industry recognizes that pure analog prototypes require leading-edge nodes where yield penalties mount. By contrast, mixed-signal layouts tolerate larger transistors and relaxed matching rules. Innatera's Spiking Neural Processor is taped out on 40-nanometer CMOS yet beats digital rivals on microwatt wake-word detection. As edge OEMs demand annual feature upgrades, mixed-signal chips provide firmware-flexible neurons alongside resistor crossbars, anchoring long-term design wins across consumer and automotive lines.
ReRAM architectures captured 23.67% of the neuromorphic chip market in 2025 and should grow at 52.11% through 2031, aided by seamless back-end-of-line integration with standard copper interconnects. ReRAM crossbars support multi-level cells, increasing synaptic density without enlarging die area. IBM phase-change memory remains a credible alternative, posting 1 million endurance cycles and nanosecond writes. Yet ReRAM's lower formation temperature and simpler materials stack drive lower wafer cost, a decisive lever in smartphone-scale volumes.
Event-driven spiking neural networks amplify ReRAM benefits through sparse activation. Every inactive synapse draws virtually no current, driving system-level power toward the microwatt floor. Prophesee sensors supply asynchronous spikes that map directly onto these arrays, eliminating frame-based overhead. Over the forecast, roadmaps show ReRAM arrays paired with digital neuron controllers in mobile SoCs, a step that positions the neuromorphic chip market size for consumer electronics to jump once Samsung and SK hynix integrate the blocks natively.
Complete Report Scope:
- By Chip Type
- Analog
- Digital
- Mixed-Signal
- By Architecture
- Spiking Neural Network
- ReRAM-Based Architectures
- Phase-Change-Memory Architectures
- By End-User Industry
- Automotive (ADAS / AV)
- Industrial IoT and Robotics
- Consumer Electronics
- Financial Services and Cybersecurity
- Healthcare and Medical Devices
- Aerospace and Defense
- By Deployment Model
- Edge Devices
- Data-Centre / Cloud
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Rest of South America
- Europe
- United Kingdom
- Germany
- France
- Italy
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- Rest of Asia Pacific
- Middle East and Africa
- Middle East
- United Arab Emirates
- Saudi Arabia
- Rest of Middle East
- Africa
- South Africa
- Egypt
- Rest of Africa
- Middle East
- North America
Geography Analysis
North America led the neuromorphic chip market with 39.31% in 2025, buoyed by IARPA, NSF, and Department of Energy grants that subsidize early silicon. Intel co-developed Loihi generations with Sandia National Laboratories, moving quickly from academic prototypes to datacenter pilots. Canada's Vector Institute and Mila deliver algorithmic breakthroughs that feed directly into commercial toolchains, while Mexico's rising contract-manufacturing sector offers near-shore assembly capacity. The region's vertically integrated ecosystem, from materials research to system integration, creates resilience but faces competition from the Asia Pacific's manufacturing scale.
Asia Pacific is forecast to grow at 52.49% through 2031, driven by China's sovereign AI mandate, Japan's robotics cluster, and South Korea's memory leadership. China's 14th Five-Year Plan funds centers like Tsinghua's Brain-Inspired Computing Lab, which tape out domestic spiking-network processors on 14-nanometer lines. Japan's NEDO backs neuromorphic co-processors for humanoid robots, while Samsung and SK Hynix integrate ReRAM crossbars into flagship mobile SoCs. India lures assembly and test operations under its Production Linked Incentive scheme, although design IP largely remains overseas.
Europe, the Middle East, and Africa, though smaller in revenue, punch above their weight in academic output. The Human Brain Project published over 1,000 articles on cortical simulation and memristive synapses. German automotive suppliers pilot spiking chips for L3 autonomy, and U.K. graphene labs explore two-dimensional synapses for microwatt devices. Middle Eastern smart-city initiatives demand low-power analytics under harsh climates, carving a specialized niche. South African miners test predictive-maintenance sensors that learn underground, where connectivity is sparse. The spread of design, fabrication, and application hubs underscores the global interdependencies shaping the neuromorphic chip market.
- Intel Corporation
- International Business Machines Corporation
- Samsung Electronics Co., Ltd.
- SK hynix Inc.
- BrainChip Holdings Ltd
- SynSense AG
- GrAI Matter Labs SAS
- Nepes Corporation
- Qualcomm Technologies, Inc.
- Micron Technology, Inc.
- Synaptics Incorporated
- Innatera Nanosystems BV
- Prophesee SA
- MemryX Inc.
- Mythic Inc.
- Syntiant Corp.
- Gyrfalcon Technology Inc.
- Applied Brain Research Inc.
- General Vision Inc.
- Vicarious Corp.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising Edge AI Demand in Consumer and Automotive
- 4.2.2 Data-Center Energy Crisis Favoring Ultra-Low-Power Compute
- 4.2.3 Government Brain-Inspired R&D Programs
- 4.2.4 Expansion of Autonomous Vehicle Domain Controller Architectures
- 4.2.5 On-Board Satellite AI Processing Requirements
- 4.2.6 OT-Cybersecurity Anomaly Detection at Network Edge
- 4.3 Market Restraints
- 4.3.1 Immature Software and Toolchain Ecosystem
- 4.3.2 Fabrication Variability of Analog NVM
- 4.3.3 Lack of Spike-System Test and Validation Standards
- 4.3.4 Unclear Medical-Device Regulatory Path
- 4.4 Industry Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitute Products
- 4.7.5 Intensity of Competitive Rivalry
- 4.8 Emerging Use-Cases for Neuromorphic Chips
- 4.9 Impact of Macroeconomic Factors on the Market
- 4.10 Investment Analysis
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Chip Type
- 5.1.1 Analog
- 5.1.2 Digital
- 5.1.3 Mixed-Signal
- 5.2 By Architecture
- 5.2.1 Spiking Neural Network
- 5.2.2 ReRAM-Based Architectures
- 5.2.3 Phase-Change-Memory Architectures
- 5.3 By End-User Industry
- 5.3.1 Automotive (ADAS / AV)
- 5.3.2 Industrial IoT and Robotics
- 5.3.3 Consumer Electronics
- 5.3.4 Financial Services and Cybersecurity
- 5.3.5 Healthcare and Medical Devices
- 5.3.6 Aerospace and Defense
- 5.4 By Deployment Model
- 5.4.1 Edge Devices
- 5.4.2 Data-Centre / Cloud
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 South America
- 5.5.2.1 Brazil
- 5.5.2.2 Argentina
- 5.5.2.3 Rest of South America
- 5.5.3 Europe
- 5.5.3.1 United Kingdom
- 5.5.3.2 Germany
- 5.5.3.3 France
- 5.5.3.4 Italy
- 5.5.3.5 Rest of Europe
- 5.5.4 Asia Pacific
- 5.5.4.1 China
- 5.5.4.2 Japan
- 5.5.4.3 India
- 5.5.4.4 South Korea
- 5.5.4.5 Rest of Asia Pacific
- 5.5.5 Middle East and Africa
- 5.5.5.1 Middle East
- 5.5.5.1.1 United Arab Emirates
- 5.5.5.1.2 Saudi Arabia
- 5.5.5.1.3 Rest of Middle East
- 5.5.5.2 Africa
- 5.5.5.2.1 South Africa
- 5.5.5.2.2 Egypt
- 5.5.5.2.3 Rest of Africa
- 5.5.5.1 Middle East
- 5.5.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as Available, Strategic Information, Market Rank/Share for Key Companies, Products and Services, and Recent Developments)
- 6.4.1 Intel Corporation
- 6.4.2 International Business Machines Corporation
- 6.4.3 Samsung Electronics Co., Ltd.
- 6.4.4 SK hynix Inc.
- 6.4.5 BrainChip Holdings Ltd
- 6.4.6 SynSense AG
- 6.4.7 GrAI Matter Labs SAS
- 6.4.8 Nepes Corporation
- 6.4.9 Qualcomm Technologies, Inc.
- 6.4.10 Micron Technology, Inc.
- 6.4.11 Synaptics Incorporated
- 6.4.12 Innatera Nanosystems BV
- 6.4.13 Prophesee SA
- 6.4.14 MemryX Inc.
- 6.4.15 Mythic Inc.
- 6.4.16 Syntiant Corp.
- 6.4.17 Gyrfalcon Technology Inc.
- 6.4.18 Applied Brain Research Inc.
- 6.4.19 General Vision Inc.
- 6.4.20 Vicarious Corp.
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment

