PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2122662

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2122662
RF GaN - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
According to Mordor Intelligence, the RF GaN market size was valued at USD 2.01 billion in 2025 and is estimated to grow from USD 2.41 billion in 2026 to reach USD 5.90 billion by 2031, at a CAGR of 19.61% during the forecast period (2026-2031).
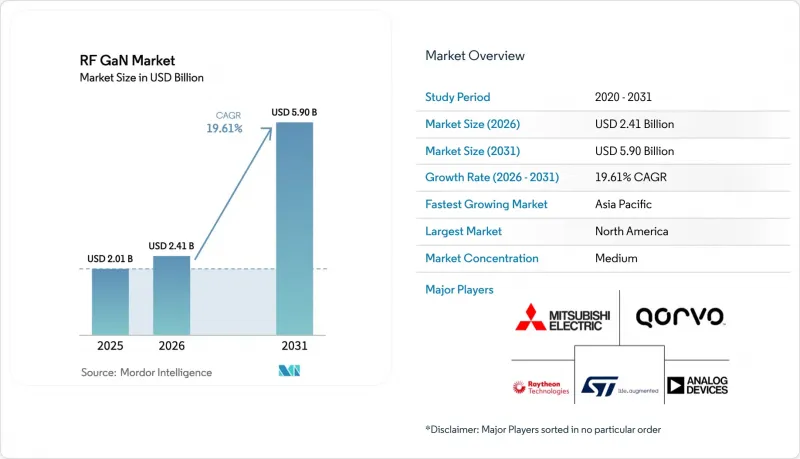
This report is Segmented by Application (Military, Telecom Infrastructure, Satellite Communication, Wired Broadband, and More), Material Type (GaN-On-Si, GaN-On-SiC, and Other Material Types), Device Type (Discrete Transistors, MMIC, Power-Amplifier Modules, and More), Frequency Band (Below 3 GHz, 3-6 GHz, 6-18 GHz, and Above 18 GHz), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global RF GaN Market Trends and Insights
Surge in Sub-6 GHz 5G mMIMO Base-Station Deployments
Mobile operators installed 1.2 million new 5G sites in 2025, of which 68% included 64-transceiver massive MIMO radios that each embed at least 64 GaN power amplifiers. Mitsubishi Electric shipped a 200-watt C-band module in June 2025, which achieved 50% drain efficiency at a 6 dB back-off, representing a 12 percentage-point improvement over the prior generation. China's operators spent CNY 87 billion on 5G radios in 2025, specifying 40% indigenous GaN content in line with Made in China 2025 targets. India's regulator mandated triple-band carrier aggregation for macro cells from January 2026, implicitly doubling the amplifier count per site. Together these mandates concentrate near-term demand in the 3.3-3.8 GHz window, keeping the RF GaN market firmly anchored in sub-6 GHz shipments.
Accelerating AESA Radar Upgrades Across Defense Platforms
Fourteen defense ministries committed USD 8.3 billion to AESA radar refresh programs during 2025, moving from gallium arsenide to GaN transmit-receive modules that double detection range while lowering fleet power draw. Raytheon began X-band APG-82(V)X deliveries for F-15EX and F-16V jets in September 2025, each array integrating 1,200 GaN MMICs. Japan's Ministry of Defense awarded Mitsubishi Electric USD 310 million in March 2025 to develop an indigenous fire-control radar for its next-generation fighter. Northrop Grumman disclosed that GaN content inside its AN/APG-83 radar rose from 22% in 2023 to 61% in 2025. Export rules under the International Traffic in Arms Regulations channel sales to allied nations, sustaining premium average selling prices that finance ongoing process R&D.
High Epitaxial-Wafer Defect Density Affecting Yield
Commercial GaN-on-SiC epitaxy posted threading dislocation densities near 5 X 108 cm-2 in 2025, about ten times higher than mature GaAs lines, depressing yields by up to 25% on high-power parts. Wolfspeed disclosed that rework consumed 8% of wafer starts at its Durham site and compressed gross margin by 220 basis points in fiscal 2025. AIXTRON and Veeco launched in-situ optical reflectometry add-ons priced at USD 1.2 million per reactor that let engineers abort defective runs early, yet fewer than one-third of reactors were retrofitted in 2025. United States export controls on advanced MOCVD tools introduced in October 2024 further limited Chinese fabs' ability to adopt these upgrades, widening the yield gap with Western suppliers. Until densities fall below 1 X 108 cm-2 the RF GaN market gains in cost will be tempered.
Other drivers and restraints analyzed in the detailed report include:
- Transition to 6-Inch and 8-Inch GaN-on-SiC Wafers Lowering USD per Watt
- GaN Front-End Adoption in LEO and GEO Satellite Payloads
- Thermal-Management Limits Above 10 W/mm in Dense Arrays
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Telecom infrastructure accounted for 46.62% of revenue in 2025 as operators supported 5.2 million 5G base stations worldwide. Satellite communication, however, is on track to register a 20.44% CAGR and will narrow the gap by 2031, powered by rising LEO constellation launches. Military programs such as AESA radar retrofits kept defense in the second position, while wired broadband nodes within DOCSIS 4.0 upgrades delivered steady but low-growth orders. Commercial radar and avionics created a small yet profitable niche, as Honeywell adopted GaN to shrink antenna size by 40%.
Operators chasing higher throughput now view Ka-band payloads as standard, which keeps amplifier counts per satellite high and secures multi-year visibility for suppliers. In contrast, RF energy applications stayed experimental although Mitsubishi Electric showcased a 70% efficient 915 MHz module for industrial ovens in June 2025. Regulatory shifts such as the United States FCC C-band repack also redirect spectrum toward 5G, indirectly boosting GaN demand in the 3.7-3.98 GHz slice. Overall, telecom dominates present consumption, yet satellite communication is likely to carry the growth banner for the RF GaN market through the forecast horizon.
GaN-on-SiC substrates held 72.73% revenue in 2025, underscoring SiC's thermal conductivity of 490 W/m K that allows junction temperatures above 200 °C without failure. GaN-on-Si remains relevant below 3 GHz where lower breakdown voltage is acceptable, but many operators are shifting to SiC to maximize power-added efficiency. The RF GaN market size advantage for GaN-on-SiC widens further at high frequencies, and the category is set for a 21.12% CAGR to 2031.
Cost pressure is easing as Wolfspeed lowered the 200-millimeter SiC wafer price from USD 850 in 2024 to USD 610 in 2025, narrowing the gap with silicon and encouraging broader adoption. Other options, such as GaN-on-diamond, showed a 40-50 °C junction reduction but, at USD 2,400 per 4-inch wafer, remain confined to premium defense applications. As foundries scale to larger diameters, SiC's performance lead, combined with falling substrate costs, will keep it the default choice for high power density designs across the RF GaN market.
Complete Report Scope:
- By Application
- Military
- Telecom Infrastructure (Backhaul, RRH, Massive MIMO, Small Cells)
- Satellite Communication
- Wired Broadband
- Commercial Radar and Avionics
- RF Energy
- By Material Type
- GaN-on-Si
- GaN-on-SiC
- Other Material Types (GaN-on-GaN, GaN-on-Diamond)
- By Device Type
- Discrete Transistors (HEMT)
- Monolithic Microwave ICs (MMIC)
- Power-Amplifier Modules
- Driver Amplifiers
- By Frequency Band
- Below 3 GHz (L, S Bands)
- 3 - 6 GHz (C Band, 5G Sub-6)
- 6 - 18 GHz (X, Ku)
- Above 18 GHz (Ka, mmWave)
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Rest of South America
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- South Korea
- India
- ASEAN
- Oceania
- Rest of Asia-Pacific
- Middle East and Africa
- Middle East
- Saudi Arabia
- UAE
- Turkey
- Rest of Middle East
- Africa
- South Africa
- North Africa
- Rest of Africa
- Middle East
- North America
Geography Analysis
North America retained 39.74% share in 2025 due to defense outlays of USD 886 billion and CHIPS Act incentives exceeding USD 900 million that underwrite capacity expansion at Wolfspeed, Skyworks, and BAE Systems. Canada added USD 88 million for radiation-hardened GaN research, and Mexico drew modest assembly investment, leveraging proximity to United States design hubs.
Asia Pacific is set for a 20.67% CAGR through 2031. China erected 900,000 5G base stations in 2025 and committed CNY 50 billion to epitaxial wafer R&D. Japan's economic ministry earmarked subsidies for wide-bandgap fabs, while India's production-linked incentive scheme covers up to 50% of capital cost, drawing interest from Tata Group. ASEAN nations, especially Vietnam and Thailand, position themselves as assembly hubs to mix lower labor cost with export privileges.
Europe held a mid-teens stake. The European Chips Act unlocked EUR 1.2 billion for pilot lines, and Infineon Technologies closed its USD 830 million GaN Systems acquisition, though focus remains mainly below 1 GHz. STMicroelectronics' Catania line accounts for sub-10% RF output yet strengthens regional capability. Middle East and Africa saw demand from satellite gateways in the United Arab Emirates and Saudi Arabia, while Latin America stays early stage with isolated defense programs such as Embraer's GaN-enabled aircraft radios.
- Aethercomm Inc.
- Ampleon Netherlands B.V.
- Analog Devices Inc.
- Broadcom Inc.
- Efficient Power Conversion Corp.
- Guerrilla RF Inc.
- HRL Laboratories LLC
- Infineon Technologies AG
- Integra Technologies Inc.
- MACOM Technology Solutions Holdings Inc.
- Mercury Systems Inc.
- Mitsubishi Electric Corp.
- NXP Semiconductors N.V.
- Northrop Grumman Corp.
- Qorvo Inc.
- Raytheon Technologies Corp.
- RFHIC Corp.
- Skyworks Solutions Inc.
- STMicroelectronics N.V.
- Sumitomo Electric Device Innovations Inc.
- Tagore Technology Inc.
- Teledyne Technologies Inc.
- Toshiba Corp.
- WIN Semiconductors Corp.
- Wolfspeed Inc.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Surge in sub-6 GHz 5G mMIMO base-station deployments
- 4.2.2 Accelerating AESA radar upgrades across defense platforms
- 4.2.3 Transition to 6-inch and 8-inch GaN-on-SiC wafers lowering $/W
- 4.2.4 GaN front-end adoption in LEO and GEO satellite payloads
- 4.2.5 Demand for ultra-wide-bandwidth PAs in mmWave backhaul
- 4.2.6 Government funding for domestic compound-semiconductor supply chains
- 4.3 Market Restraints
- 4.3.1 High epitaxial-wafer defect density affecting yield
- 4.3.2 Thermal-management limits above 10 W/mm in dense arrays
- 4.3.3 Export-control regulations on GaN devices and MOCVD tools
- 4.3.4 Competition from advanced LDMOS below 3 GHz
- 4.4 Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Bargaining Power of Suppliers
- 4.7.4 Threat of Substitute Products
- 4.7.5 Intensity of Competitive Rivalry
- 4.8 Investment Analysis
- 4.9 Impact of Macroeconomic Factors on the Market
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Application
- 5.1.1 Military
- 5.1.2 Telecom Infrastructure (Backhaul, RRH, Massive MIMO, Small Cells)
- 5.1.3 Satellite Communication
- 5.1.4 Wired Broadband
- 5.1.5 Commercial Radar and Avionics
- 5.1.6 RF Energy
- 5.2 By Material Type
- 5.2.1 GaN-on-Si
- 5.2.2 GaN-on-SiC
- 5.2.3 Other Material Types (GaN-on-GaN, GaN-on-Diamond)
- 5.3 By Device Type
- 5.3.1 Discrete Transistors (HEMT)
- 5.3.2 Monolithic Microwave ICs (MMIC)
- 5.3.3 Power-Amplifier Modules
- 5.3.4 Driver Amplifiers
- 5.4 By Frequency Band
- 5.4.1 Below 3 GHz (L, S Bands)
- 5.4.2 3 - 6 GHz (C Band, 5G Sub-6)
- 5.4.3 6 - 18 GHz (X, Ku)
- 5.4.4 Above 18 GHz (Ka, mmWave)
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 South America
- 5.5.2.1 Brazil
- 5.5.2.2 Argentina
- 5.5.2.3 Rest of South America
- 5.5.3 Europe
- 5.5.3.1 Germany
- 5.5.3.2 United Kingdom
- 5.5.3.3 France
- 5.5.3.4 Italy
- 5.5.3.5 Spain
- 5.5.3.6 Rest of Europe
- 5.5.4 Asia-Pacific
- 5.5.4.1 China
- 5.5.4.2 Japan
- 5.5.4.3 South Korea
- 5.5.4.4 India
- 5.5.4.5 ASEAN
- 5.5.4.6 Oceania
- 5.5.4.7 Rest of Asia-Pacific
- 5.5.5 Middle East and Africa
- 5.5.5.1 Middle East
- 5.5.5.1.1 Saudi Arabia
- 5.5.5.1.2 UAE
- 5.5.5.1.3 Turkey
- 5.5.5.1.4 Rest of Middle East
- 5.5.5.2 Africa
- 5.5.5.2.1 South Africa
- 5.5.5.2.2 North Africa
- 5.5.5.2.3 Rest of Africa
- 5.5.5.1 Middle East
- 5.5.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 Aethercomm Inc.
- 6.4.2 Ampleon Netherlands B.V.
- 6.4.3 Analog Devices Inc.
- 6.4.4 Broadcom Inc.
- 6.4.5 Efficient Power Conversion Corp.
- 6.4.6 Guerrilla RF Inc.
- 6.4.7 HRL Laboratories LLC
- 6.4.8 Infineon Technologies AG
- 6.4.9 Integra Technologies Inc.
- 6.4.10 MACOM Technology Solutions Holdings Inc.
- 6.4.11 Mercury Systems Inc.
- 6.4.12 Mitsubishi Electric Corp.
- 6.4.13 NXP Semiconductors N.V.
- 6.4.14 Northrop Grumman Corp.
- 6.4.15 Qorvo Inc.
- 6.4.16 Raytheon Technologies Corp.
- 6.4.17 RFHIC Corp.
- 6.4.18 Skyworks Solutions Inc.
- 6.4.19 STMicroelectronics N.V.
- 6.4.20 Sumitomo Electric Device Innovations Inc.
- 6.4.21 Tagore Technology Inc.
- 6.4.22 Teledyne Technologies Inc.
- 6.4.23 Toshiba Corp.
- 6.4.24 WIN Semiconductors Corp.
- 6.4.25 Wolfspeed Inc.
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-Need Assessment

