PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2122704

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2122704
Anti-Graffiti Coatings - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
According to Mordor Intelligence, the anti-Graffiti coatings market size is expected to grow from USD 87.18 Million in 2025 to USD 90.55 Million in 2026 and is forecast to reach USD 109.45 Million by 2031 at 3.87% CAGR over 2026-2031.
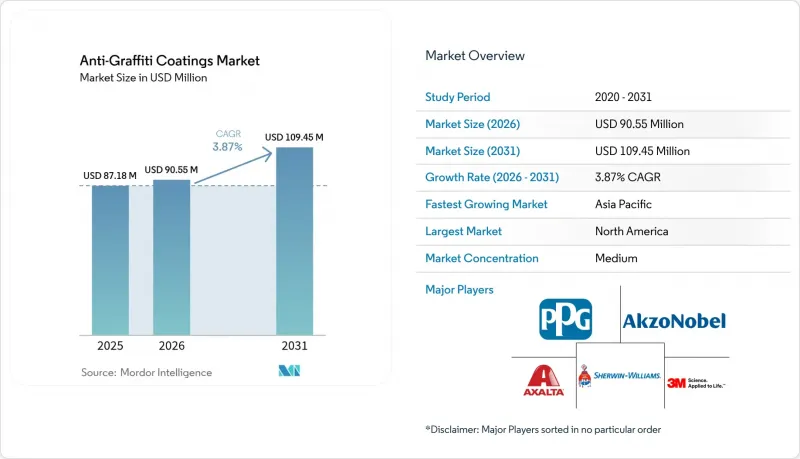
This report is Segmented by Type (Sacrificial, Semi-Sacrificial, and Non-Sacrificial), Technology (Water-Based, Solvent-Based, and Powder Coating), End-User Industry (Automotive and Transportation, Construction, and Other End-User Industries), and Geography (Asia-Pacific, North America, Europe, South America, and Middle East and Africa). The Market Forecasts are Provided in Terms of Value (USD).
Global Anti-Graffiti Coatings Market Trends and Insights
Escalating Municipality Spending on Graffiti Removal
Cities are front-loading budgets to curb soaring vandalism costs that outpace routine maintenance allocations. Portland's Emergency Ordinance 1099-2024 follows a 586% jump in graffiti complaints between 2020 and 2022, while Wellington City Council ring-fenced USD 7.57 Million for protective programmes through 2025 . Deutsche Bahn's EUR 8 Million annual outlay on cleanup has pushed the rail operator toward polysilazane barriers that tolerate repeated solvent-free wash cycles. As prevention proves cheaper than serial removal, municipal procurement increasingly favours permanent, low-VOC (Volatile Organic Compound) coatings that preserve urban aesthetics and minimise life-cycle costs. This shift anchors steady volume off-take for the anti-graffiti coatings market in public infrastructure and transit assets, underpinning suppliers' medium-term revenue visibility.
Rapid Expansion of Public Infrastructure Construction
Asia-Pacific construction booms are boosting baseline demand for surface-protection solutions. China's 2024 National Development and Reform Commission roadmap highlights "high-quality infrastructure" as a domestic-demand catalyst, accelerating anti-graffiti specification in rail, bridge, and smart-city projects. Parallel smart-mobility corridors in India and Indonesia are embedding permanent coatings into procurement standards to curb future maintenance outlays. Similar funding flows from the United States' Federal Buy Clean initiative channel more than USD 2 Billion toward low-carbon building materials, tilting preferences to water-based, Volatile Organic Compound (VOC)-compliant offerings. Contractors in emerging hubs, often operating without established cleaning fleets, view durable coatings as an upfront safeguard that lowers whole-life costs, reinforcing long-run uptake across the anti-graffiti coatings market.
Volatile Siloxane and Fluoropolymer Raw-Material Costs
Siloxane and fluoropolymer pricing swings are squeezing producer margins at a time when end-users remain price sensitive. European Chemicals Agency proposals to tighten rules on certain silicon compounds, including Silicon Dioxide (SiO2), have heightened supply-chain caution and inflated compliance expenditures. Producers are experimenting with hybrid chemistries that trim siloxane loads while safeguarding durability, yet re-engineering hurdles and certification timelines slow roll-outs. Smaller formulators reliant on spot purchases face pronounced cost pass-through risks, restraining near-term output in the anti-graffiti coatings market.
Other drivers and restraints analyzed in the detailed report include:
- Stricter Volatile Organic Compound (VOC) Norms Accelerating Water-borne Formulations
- Adoption of Anti-graffiti Powder Coatings for Smart-city Street Furniture
- Emerging Per- and polyfluoroalkyl substances (PFAS) Restrictions Affecting Fluorinated Coatings
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Non-sacrificial systems held 51.63% of anti-graffiti coatings market share in 2025 and are expanding at a 4.42% CAGR to 2031. Customers favour their one-time application and rinse-repeat cleaning tolerance that shrink life-cycle spend. Semi-sacrificial formats satisfy mid-tier budgets with moderate recoat intervals, while sacrificial films cater to historic preservation or sensitive substrates that cannot host durable polymers.
Higher upfront expenditure on non-sacrificial layers is offset by fewer closures of transit stations or public buildings for re-painting. Case studies on polyurethane-powder barriers show wash-off resilience beyond 1,000 cleaning cycles without gloss loss. These economics reinforce the premium niche, anchoring value concentration within the anti-graffiti coatings market.
Complete Report Scope:
- By Type
- Sacrificial
- Semi-Sacrificial
- Non-Sacrificial
- By Technology
- Water-Based
- Solvent-Based
- Powder Coating
- By End-User Industry
- Automotive and Transportation
- Construction
- Other End-User Industries (Industrial Equipment, Utilities)
- By Geography
- Asia-Pacific
- China
- Japan
- India
- South Korea
- ASEAN Countries
- Rest of Asia-Pacific
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Russia
- NORDIC Countries
- Rest of Europe
- South America
- Brazil
- Argentina
- Rest of South America
- Middle East and Africa
- Saudi Arabia
- South Africa
- Rest of Middle East and Africa
- Asia-Pacific
Geography Analysis
North America retained 38.90% of the Anti-Graffiti Coatings market share in 2025. Portland's Emergency Ordinance 1099-2024 and similar city mandates integrate protective coatings into annual maintenance budgets, translating to predictable recurrent orders. The region's Buy Clean clauses funnel federal funds toward low-carbon, water-based layers, pushing compliant suppliers up the preferred-vendor ladder. California's Air Quality Management District (AQMD) caps of 100 g/L Volatile Organic Compound (VOC) on non-sacrificial coatings continue to spur research and development (R&D) output, influencing product lines shipped worldwide.
Asia-Pacific is the fastest-expanding territory at 4.14% CAGR through 2031, propelled by China's infrastructure acceleration and India's 100-smart-city rollout. Urban councils specifying preventive coatings for metro pillars and pedestrian bridges aim to avoid future cleaning labour spikes. Mature markets such as Japan and South Korea sustain flow by retrofitting existing rail and highway assets with low-VOC layers in line with tightened environmental policies.
Europe grows steadily under the weight of progressive environmental regulation. France's Per- and polyfluoroalkyl substances (PFAS) embargo and the European Union (EU)'s pending wide-spectrum restriction are reshuffling resin choices and fast-tracking silicone and bio-polymer research. Germany's graffiti damage exceeding EUR 200 Million each year sharpens the financial case for permanent barriers, encouraging municipal consortiums to award long-term maintenance contracts featuring anti-graffiti clauses. South America and the Middle East & Africa, while smaller today, are carving space through rapid metro upgrades in Sao Paulo and Riyadh, positioning the anti-graffiti coatings market for multi-regional breadth.
- 3M
- AkzoNobel N.V.
- Axalta Coating Systems LLC
- BASF
- CSL Silicones Inc.
- Dulux
- Hempel A/S
- Hydron Protective Coatings Ltd
- IFS Coatings
- IGP Pulvertechnik AG
- Nano-Care Deutschland AG
- Nukote Coating Systems International
- PPG Industries Inc.
- Saint-Gobain
- Teknos Group
- The Sherwin-Williams Company
- Urban Hygiene Ltd
- W.R.Meadows, Inc.
- Wacker Chemie AG
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Escalating Municipality Spending on Graffiti Removal
- 4.2.2 Rapid Expansion of Public-infrastructure Construction
- 4.2.3 Stricter Volatile Organic Compound (VOC) Norms Accelerating Water-borne Formulations
- 4.2.4 Adoption of Anti-graffiti Powder Coatings for Smart-city Street Furniture
- 4.2.5 Convergence of Anti-graffiti & Antimicrobial Surfaces in Transit Assets
- 4.3 Market Restraints
- 4.3.1 Volatile Siloxane & Fluoropolymer Raw-material Costs
- 4.3.2 Emerging Per- and polyfluoroalkyl substances (PFAS) Restrictions Affecting Fluorinated Coatings
- 4.3.3 Adhesion Challenges on Highly Porous 3D-Printed Concrete Facades
- 4.4 Value Chain Analysis
- 4.5 Porter's Five Forces
- 4.5.1 Bargaining Power of Suppliers
- 4.5.2 Bargaining Power of Buyers
- 4.5.3 Threat of New Entrants
- 4.5.4 Threat of Substitutes
- 4.5.5 Degree of Competition
5 Market Size & Growth Forecasts (Value)
- 5.1 By Type
- 5.1.1 Sacrificial
- 5.1.2 Semi-Sacrificial
- 5.1.3 Non-Sacrificial
- 5.2 By Technology
- 5.2.1 Water-Based
- 5.2.2 Solvent-Based
- 5.2.3 Powder Coating
- 5.3 By End-User Industry
- 5.3.1 Automotive and Transportation
- 5.3.2 Construction
- 5.3.3 Other End-User Industries (Industrial Equipment, Utilities)
- 5.4 By Geography
- 5.4.1 Asia-Pacific
- 5.4.1.1 China
- 5.4.1.2 Japan
- 5.4.1.3 India
- 5.4.1.4 South Korea
- 5.4.1.5 ASEAN Countries
- 5.4.1.6 Rest of Asia-Pacific
- 5.4.2 North America
- 5.4.2.1 United States
- 5.4.2.2 Canada
- 5.4.2.3 Mexico
- 5.4.3 Europe
- 5.4.3.1 Germany
- 5.4.3.2 United Kingdom
- 5.4.3.3 France
- 5.4.3.4 Italy
- 5.4.3.5 Spain
- 5.4.3.6 Russia
- 5.4.3.7 NORDIC Countries
- 5.4.3.8 Rest of Europe
- 5.4.4 South America
- 5.4.4.1 Brazil
- 5.4.4.2 Argentina
- 5.4.4.3 Rest of South America
- 5.4.5 Middle East and Africa
- 5.4.5.1 Saudi Arabia
- 5.4.5.2 South Africa
- 5.4.5.3 Rest of Middle East and Africa
- 5.4.1 Asia-Pacific
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share(%)/Ranking Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products & Services, and Recent Developments)
- 6.4.1 3M
- 6.4.2 AkzoNobel N.V.
- 6.4.3 Axalta Coating Systems LLC
- 6.4.4 BASF
- 6.4.5 CSL Silicones Inc.
- 6.4.6 Dulux
- 6.4.7 Hempel A/S
- 6.4.8 Hydron Protective Coatings Ltd
- 6.4.9 IFS Coatings
- 6.4.10 IGP Pulvertechnik AG
- 6.4.11 Nano-Care Deutschland AG
- 6.4.12 Nukote Coating Systems International
- 6.4.13 PPG Industries Inc.
- 6.4.14 Saint-Gobain
- 6.4.15 Teknos Group
- 6.4.16 The Sherwin-Williams Company
- 6.4.17 Urban Hygiene Ltd
- 6.4.18 W.R.Meadows, Inc.
- 6.4.19 Wacker Chemie AG
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-Need Assessment
- 7.2 Introduction of Bio-based Technology Coatings

