PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2122808

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2122808
Methyl Methacrylate (MMA) Adhesives - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
According to Mordor Intelligence, the methyl methacrylate adhesives market size is expected to increase from USD 265.31 million in 2025 to USD 276.03 million in 2026 and reach USD 336.48 million by 2031, growing at a CAGR of 4.04% over 2026-2031.
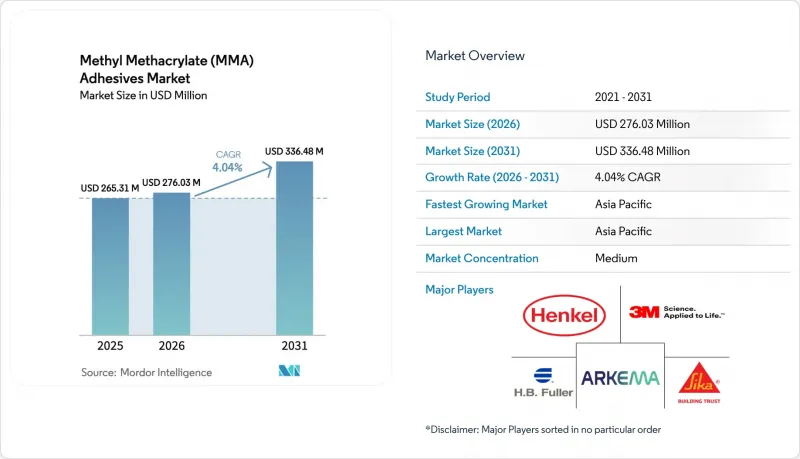
This report is Segmented by Substrate (Metals, Plastics, Composites, and Other Substrates), End-Use Industry (Transportation, Aerospace, Building and Construction, Power Generation, and Other End-User Industries), and Geography (Asia-Pacific, North America, Europe, South America, and Middle East and Africa). The Market Forecasts are Provided in Terms of Value (USD).
Global Methyl Methacrylate (MMA) Adhesives Market Trends and Insights
Light-Weighting Push Across Mobility Segments
Automakers and aircraft OEMs are eliminating mechanical fasteners to remove mass, improve range, and meet CO2 targets. Ford cut 47 kg from its 2025 F-150 Lightning by bonding aluminum to high-strength steel with MMA adhesives, realizing a 3.2% range gain. Airbus reported a 680 kg reduction on each A321neo after replacing rivets in secondary structures, saving 1.8% fuel over the aircraft life. Because every kilogram trimmed extends electric-vehicle range by roughly 20 m, MMA bonding's premium over welding is economically justified, particularly when OEMs avoid the capital outlay for new spot-welding cells. Formulators are therefore focused on 15- to 30-minute fixture times that match paced assembly lines while meeting new 50 ppm workplace-exposure limits in the EU.
Substitution of Welding/Riveting in Composite-Metal Joints
Composite content exceeds 50% on the Boeing 787 and Airbus A350, yet drilling fastener holes degrades fatigue life. NASA's 2024 test program found bonded joints extend composite fatigue life by 15%-25% compared with riveted equivalents. Spirit AeroSystems eliminated 1,200 fasteners per 737 MAX wing set, trimming USD 18,000 in build cost and 34% in assembly time after shifting to MMA adhesives in 2025. BMW achieved 28 MPa lap-shear strength when bonding carbon-fiber roofs to aluminum pillars on the iX M60, avoiding galvanic corrosion while tolerating differential thermal expansion. Aerospace certification under ISO 11003-2 keeps barriers high, locking in value once a formulation is approved.
Volatility in MMA Monomer Feedstock Prices
Spot MMA prices jumped 18% to USD 2,340 /t FOB Asia in Q2 2025 after propylene outages in China and South Korea, squeezing formulators unable to lock long-term contracts. A 15% feedstock hike lifts finished-adhesive cost by 9%-11%, but competitive pressure caps pass-through at 4%-6%, clipping gross margins 300-500 bp. Mitsubishi Chemical's 100 kt/yr Saudi plant, started in 2024, adds capacity yet still covers just 3.2% of global supply. Because only 4 of the top 15 suppliers run captive monomer production, the majority remain exposed to swings that showed a 32% coefficient of variation over 24 months.
Other drivers and restraints analyzed in the detailed report include:
- Growth of Offshore Wind-Turbine Blade Bonding
- Rapid Infrastructure Build-Out in ASEAN Prefab Construction
- Stringent VOC and Odor Exposure Limits
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Metals produced the largest slice of demand, accounting for 42.19% in 2025, because automotive and aerospace builders still rely heavily on aluminum-to-steel joints that require 18-24 MPa lap-shear strength and tolerate differing thermal expansion rates. In value terms, the metals slice of the methyl methacrylate (MMA) adhesives market size stood at USD 116.5 million in 2026. Composites are the clear growth engine, expanding at a 6.15% CAGR to 2031 as carbon-fiber wind-turbine spar caps and aircraft secondary structures proliferate. Adhesive joints eliminate galvanic-corrosion concerns while spreading loads over greater surface area, extending fatigue life in next-generation airframes.
The composites surge encapsulates a structural material shift rather than a cyclical rebound. Boeing raised composite content on the 777X to 54%, specifying MMA bonding for fuselage-panel integration that avoids the drilling damage seen with rivets. Wind turbines longer than 100 m require gap-filling adhesives that cure at ambient temperature in coastal factories lacking climate control, a niche where MMA chemistry surpasses epoxies. Plastics form a small yet rising cohort-especially ABS, polycarbonate, and acrylic in EV battery casings-because MMA joins them with minimal surface prep. Ceramics and wood remain niche uses, though ceramic-metal bonds in electronics heat sinks are attracting R&D attention.
Complete Report Scope:
- By Substrate
- Metals
- Plastics
- Composites
- Other Substrates
- By End-Use Industry
- Transportation
- Aerospace
- Building and Construction
- Power Generation (Wind and Solar)
- Other End-user Industries (Marine, Electronics and Appliances)
- By Geography
- Asia-Pacifc
- China
- India
- Japan
- South Korea
- ASEAN Countries
- Rest of Asia-Pacific
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Rest of Europe
- South America
- Brazil
- Argentina
- Rest of South America
- Middle East and Africa
- Saudi Arabia
- South Africa
- Rest of Middle East and Africa
- Asia-Pacifc
Geography Analysis
Asia-Pacific captured 46.29% of global demand in 2025 and is set to advance at 5.76% CAGR to 2031. China approved 18.2 GW of new offshore wind in 2025, each MW adding up to 12 kg of MMA usage, translating to an incremental 145-218 t per year. India built 5.9 million passenger cars in FY 2024-25, accelerating adhesive uptake to meet fuel-economy rules tightening to 118 g CO2/km by 2027. Japan's hydrogen-fuel-cell road map is spurring MMA use in carbon-fiber storage tanks that must hold 700 bar without micro-cracking. ASEAN's USD 3.1 trillion infrastructure pipeline leans heavily on prefab modules bonded with MMA, with adoption climbing to 34% of new commercial starts in 2025.
In North America, Boeing's plan to build 38 737 MAX jets per month consumes up to 11 t of adhesive monthly for secondary structures alone. The Inflation Reduction Act encourages local sourcing; Henkel's USD 65 million expansion in Connecticut adds 12 kt of annual capacity for automotive and wind clients. Canada's 5 GW offshore wind prospects will open a fresh channel when construction begins in 2027-29. Mexican auto hubs used about 3,200 t in 2025 as GM and Ford rolled out EV platforms that bond aluminum battery trays to steel underbodies.
Europe, though mature, is buoyed by 7.3 GW of offshore wind commissioned in 2025 and by OEM shifts toward adhesive bonding to trim welding costs. Volkswagen cut 340 welds on each ID.7 roof panel, saving EUR 18 per unit. The UK's latest Contracts for Difference round awarded 6.4 GW of offshore projects entering build phase from 2026. Smaller yet promising, South America rides Brazilian wind expansions, while the Middle East benefits from Saudi Arabia's NEOM city, which mandates adhesive-bonded facades in 80% of residential buildings.
- 3M
- Arkema
- BASF
- Dow
- Evonik Industries AG
- H.B. Fuller Company
- Henkel AG & Co. KGaA
- Huntsman International LLC
- IPS Corporation
- ITW Performance Polymers
- Master Bond
- Matrix Adhesives Group
- Parker Hannifin Corp
- Permabond LLC
- Scott Bader Company Ltd
- Sika AG
- Ulbrich Group
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Light-Weighting Push Across Mobility Segments
- 4.2.2 Substitution of Welding/Riveting in Composite-Metal Joints
- 4.2.3 Growth of Offshore Wind-Turbine Blade Bonding
- 4.2.4 Rapid Infrastructure Build-Out in ASEAN Prefab Construction
- 4.2.5 Increasing Demand from Marine Sector
- 4.3 Market Restraints
- 4.3.1 Volatility in MMA Monomer Feedstock Prices
- 4.3.2 Stringent VOC and Odor Exposure Limits
- 4.3.3 Cartridge Waste-Disposal Regulations in Urban Plants
- 4.4 Value Chain Analysis
- 4.5 Porter's Five Forces
- 4.5.1 Bargaining Power of Suppliers
- 4.5.2 Bargaining Power of Buyers
- 4.5.3 Threat of New Entrants
- 4.5.4 Threat of Substitutes
- 4.5.5 Industry Rivalry
5 Market Size and Growth Forecasts (Value)
- 5.1 By Substrate
- 5.1.1 Metals
- 5.1.2 Plastics
- 5.1.3 Composites
- 5.1.4 Other Substrates
- 5.2 By End-Use Industry
- 5.2.1 Transportation
- 5.2.2 Aerospace
- 5.2.3 Building and Construction
- 5.2.4 Power Generation (Wind and Solar)
- 5.2.5 Other End-user Industries (Marine, Electronics and Appliances)
- 5.3 By Geography
- 5.3.1 Asia-Pacifc
- 5.3.1.1 China
- 5.3.1.2 India
- 5.3.1.3 Japan
- 5.3.1.4 South Korea
- 5.3.1.5 ASEAN Countries
- 5.3.1.6 Rest of Asia-Pacific
- 5.3.2 North America
- 5.3.2.1 United States
- 5.3.2.2 Canada
- 5.3.2.3 Mexico
- 5.3.3 Europe
- 5.3.3.1 Germany
- 5.3.3.2 United Kingdom
- 5.3.3.3 France
- 5.3.3.4 Italy
- 5.3.3.5 Rest of Europe
- 5.3.4 South America
- 5.3.4.1 Brazil
- 5.3.4.2 Argentina
- 5.3.4.3 Rest of South America
- 5.3.5 Middle East and Africa
- 5.3.5.1 Saudi Arabia
- 5.3.5.2 South Africa
- 5.3.5.3 Rest of Middle East and Africa
- 5.3.1 Asia-Pacifc
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share(%)/Ranking Analysis
- 6.4 Company Profiles {(includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)}
- 6.4.1 3M
- 6.4.2 Arkema
- 6.4.3 BASF
- 6.4.4 Dow
- 6.4.5 Evonik Industries AG
- 6.4.6 H.B. Fuller Company
- 6.4.7 Henkel AG & Co. KGaA
- 6.4.8 Huntsman International LLC
- 6.4.9 IPS Corporation
- 6.4.10 ITW Performance Polymers
- 6.4.11 Master Bond
- 6.4.12 Matrix Adhesives Group
- 6.4.13 Parker Hannifin Corp
- 6.4.14 Permabond LLC
- 6.4.15 Scott Bader Company Ltd
- 6.4.16 Sika AG
- 6.4.17 Ulbrich Group
7 Market Opportunities and Future Outlook
- 7.1 White-space and Unmet-Need Assessment
- 7.2 Growing Applications across Construction Segments

