PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2122823

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2122823
Dental Cement - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
According to Mordor Intelligence, dental cement market size in 2026 is estimated at USD 1.63 billion, growing from 2025 value of USD 1.54 billion with 2031 projections showing USD 2.14 billion, growing at 5.62% CAGR over 2026-2031.
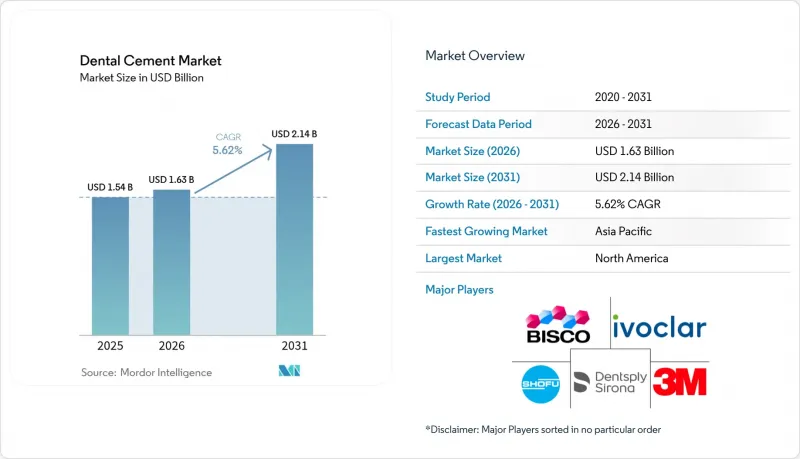
This report Segments the Industry Into by Product Type (Temporary and Permanent ), by Material Type (Glass Ionomer, Zinc Oxide Eugenol, Zinc Phosphate and More), by Application (Pulpal Protection, Luting & Bonding and More), by End User (Hospitals, Dental Clinics, Other End Users), and Geography (North America, Europe, Asia-Pacific and More). The Market Forecasts are Provided in Terms of Value (USD).
Global Dental Cement Market Trends and Insights
Rising Prevalence of Dental Caries and Edentulism
Untreated dental caries affected nearly 3.5 billion people in 2024, establishing a persistent clinical workload that sustains the dental cement market. Aging demographics elevate edentulism rates and heighten demand for durable prosthodontic solutions that rely on high-strength permanent cements. The global economic burden-USD 387 billion in direct costs and USD 323 billion in indirect costs-reinforces the need for cements that minimize retreatment cycles. Manufacturers that demonstrate bio-activity, fluoride release, and simplified workflows strengthen adoption among cost-sensitive providers within the dental cement market.
Increasing Orthodontic & Prosthodontic Procedure Volumes
Surveys indicate 20.6% of young adults intend to pursue aligner therapy, intensifying demand for cements compatible with ceramic brackets and clear-aligner attachments. Prosthodontics is scaling as CAD/CAM and 3-D printing shorten chair time and elevate aesthetics, driving need for cements that bond to zirconia, lithium-disilicate, and polymer-infiltrated ceramics. Integration of robotics and AI in prosthodontics raises performance benchmarks for bond strength and marginal integrity. These factors reinforce long-term demand trajectories in the dental cement market.
High Price Sensitivity Among Small Dental Clinics
Ninety-five percent of independent practices reported higher supply costs in 2024, while hygienist wages increased 26.6% between 2018 and 2023, eroding margins. These clinics often substitute premium bio-active cements with lower-cost alternatives, slowing penetration in price-elastic regions. Insurance reimbursement ceilings exacerbate procurement trade-offs, prompting practices to evaluate total cost of care when selecting cement systems. In emerging markets, the dynamic limits volume growth for advanced formulations, moderating overall expansion in the dental cement market.
Other drivers and restraints analyzed in the detailed report include:
- Growth of Cosmetic / Aesthetic Dentistry
- Regulatory Push Toward Mercury-Free, Fluoride-Releasing Restoratives
- Stringent ISO 4049 & FDA 510(k) Performance Validations
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Permanent products held 71.80% of the dental cement market share in 2025, anchoring overall revenue due to their role in definitive crowns, bridges, and implant restorations. Enhanced bio-active formulations such as ACTIVA BioACTIVE release fluoride, calcium, and phosphate ions, promoting remineralization and mitigating secondary caries risk. Universal self-adhesive chemistries simplify clinical workflows by eliminating separate primers, reducing chair time for high-volume practices.
Temporary cements, although smaller in revenue, are forecast to expand at a 6.15% CAGR as multi-stage implant cases and complex rehabilitations proliferate. Demand is further buoyed by the rise of same-day CAD/CAM workflows that use temporary restorations for occlusal verification before final placement. Innovations in eugenol-free, resin-reinforced temporary cements improve stability without compromising retrievability, enhancing patient experience and clinic efficiency within the dental cement market.
Complete Report Scope:
- By Type
- Permanent
- Temporary
- By Material
- Zinc-Oxide Eugenol
- Zinc Phosphate
- Polycarboxylate
- Glass Ionomer
- Resin-Based
- Others
- By Application
- Pulpal Protection
- Luting & Bonding
- Restorations
- Surgical Dressing
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- South Korea
- Australia
- Rest of Asia-Pacific
- Middle East and Africa
- GCC
- South Africa
- Rest of Middle East and Africa
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
North America led with 39.05% of the dental cement market share in 2025, underpinned by advanced dental infrastructure, high insurance penetration, and widespread adoption of digital dentistry. Expansion of dental service organizations is standardizing procurement protocols and accelerating uptake of premium bio-active systems. Regulatory clarity provided by FDA 510(k) pathways, despite added stringency, encourages early commercial launches, particularly for universal adhesive and dual-cure products.
Asia-Pacific delivers the fastest 6.90% CAGR, propelled by growing middle-class populations and heightened awareness campaigns. India hosts roughly 65,000 dental clinics and a USD 1.7 billion dental ecosystem, fuelling demand for restorative materials that balance performance with affordability. China's rapid urbanization raises restorative procedure volumes, while Japan and South Korea contribute through advanced materials innovation and insurance support for geriatric care. Nonetheless, price sensitivity dictates tiered portfolio strategies as clinics weigh premium features against budget constraints in the dental cement market.
Europe confronts immediate material transition challenges following the January 2025 mercury amalgam ban, instigating accelerated adoption of mercury-free, fluoride-releasing cements environment. Germany, France, and the United Kingdom spearhead demand given robust prosthodontic training programs and consumer preference for aesthetic treatments. Regulatory harmonization via ISO 106 dentistry standards elevates product quality thresholds, favoring manufacturers with documented biocompatibility and long-term clinical data.
- 3M
- Dentsply Sirona
- Danaher (Envista - Kerr)
- Ivoclar Vivadent
- GC Corporation
- SHOFU Dental
- Coltene Holding
- Kuraray Noritake Dental
- BISCO
- Medental International
- VOCO
- Tokuyama Dental
- Ultradent Products
- Septodont
- SDI
- Pulpdent
- DenMat Holdings
- DMG Chem-Pharma
- FGM Dental
- Kuraray America
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising prevalence of dental caries and edentulism
- 4.2.2 Increasing orthodontic & prosthodontic procedure volumes
- 4.2.3 Growth of cosmetic / aesthetic dentistry
- 4.2.4 Regulatory push toward mercury-free, fluoride-releasing restoratives (under-reported)
- 4.2.5 Rapid emergence of bio-active & nano-hybrid cement technologies (under-reported)
- 4.3 Market Restraints
- 4.3.1 High price sensitivity among small dental clinics
- 4.3.2 Stringent ISO 4049 & FDA 510(k) performance validations
- 4.3.3 Supply-chain crunch in specialty monomers & rare-earth fillers (under-reported)
- 4.3.4 Environmental scrutiny on eugenol & Bis-GMA disposal (under-reported)
- 4.4 Value / Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Suppliers
- 4.7.3 Bargaining Power of Buyers
- 4.7.4 Threat of Substitutes
- 4.7.5 Competitive Rivalry
5 Market Size & Growth Forecasts
- 5.1 By Type
- 5.1.1 Permanent
- 5.1.2 Temporary
- 5.2 By Material
- 5.2.1 Zinc-Oxide Eugenol
- 5.2.2 Zinc Phosphate
- 5.2.3 Polycarboxylate
- 5.2.4 Glass Ionomer
- 5.2.5 Resin-Based
- 5.2.6 Others
- 5.3 By Application
- 5.3.1 Pulpal Protection
- 5.3.2 Luting & Bonding
- 5.3.3 Restorations
- 5.3.4 Surgical Dressing
- 5.4 By Geography
- 5.4.1 North America
- 5.4.1.1 United States
- 5.4.1.2 Canada
- 5.4.1.3 Mexico
- 5.4.2 Europe
- 5.4.2.1 Germany
- 5.4.2.2 United Kingdom
- 5.4.2.3 France
- 5.4.2.4 Italy
- 5.4.2.5 Spain
- 5.4.2.6 Rest of Europe
- 5.4.3 Asia-Pacific
- 5.4.3.1 China
- 5.4.3.2 Japan
- 5.4.3.3 India
- 5.4.3.4 South Korea
- 5.4.3.5 Australia
- 5.4.3.6 Rest of Asia-Pacific
- 5.4.4 Middle East and Africa
- 5.4.4.1 GCC
- 5.4.4.2 South Africa
- 5.4.4.3 Rest of Middle East and Africa
- 5.4.5 South America
- 5.4.5.1 Brazil
- 5.4.5.2 Argentina
- 5.4.5.3 Rest of South America
- 5.4.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Market Share Analysis
- 6.3 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products & Services, and Recent Developments)
- 6.3.1 3M
- 6.3.2 Dentsply Sirona
- 6.3.3 Danaher (Envista - Kerr)
- 6.3.4 Ivoclar Vivadent
- 6.3.5 GC Corporation
- 6.3.6 SHOFU Dental
- 6.3.7 Coltene Holding
- 6.3.8 Kuraray Noritake Dental
- 6.3.9 BISCO
- 6.3.10 Medental International
- 6.3.11 VOCO GmbH
- 6.3.12 Tokuyama Dental
- 6.3.13 Ultradent Products
- 6.3.14 Septodont
- 6.3.15 SDI Limited
- 6.3.16 Pulpdent
- 6.3.17 DenMat Holdings
- 6.3.18 DMG Chem-Pharma
- 6.3.19 FGM Dental
- 6.3.20 Kuraray America
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-need Assessment

