PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2123324

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2123324
Head-Up Display - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
According to Mordor Intelligence, the head-Up display market size is expected to grow from USD 2.96 billion in 2025 to USD 3.83 billion in 2026 and is forecast to reach USD 10 billion by 2031 at 21.16% CAGR over 2026-2031, underscoring a steep expansion curve for this cockpit technology.
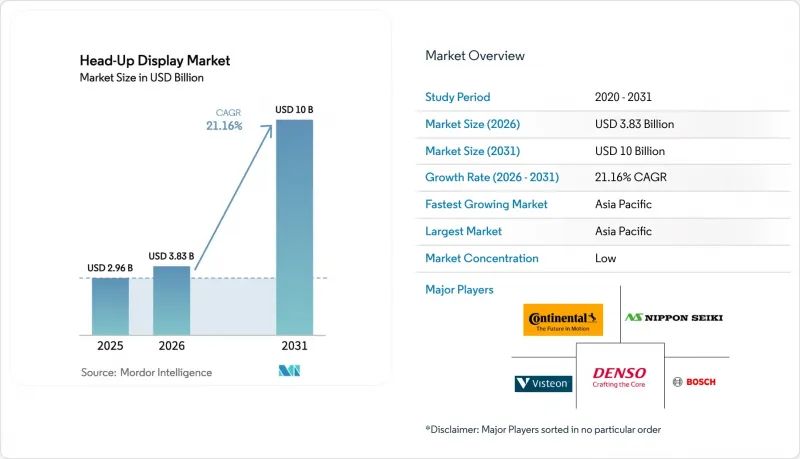
This report is Segmented by HUD Type (Windshield-Based HUD, Combiner-Based HUD, Augmented Reality HUD, and Conventional HUD), Dimension Type (2D HUD, and 3D HUD), Vehicle Class (Commercial Vehicles, and Passenger Vehicles), Sales Channel (OEM-Fitted, and Aftermarket), Application (Automotive, Military and Civil Aviation, and More), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global Head-Up Display Market Trends and Insights
Rising Integration of Augmented Reality HUDs in Mid-Range Vehicles
Chinese and European automakers are pushing AR projection from luxury lines into vehicles priced between USD 30,000 and USD 50,000, resetting buyer expectations in the head-up display market. Waveguide optics now shrink projector volume to under 1 liter, freeing dashboard space and lowering material cost below the USD 300 price point that unlocks mass-market adoption. Xpeng's G7 launch in June 2025, using Huawei's AR-HUD, projects an 87-inch virtual image at more than 12,000 nits brightness, proof that premium specifications can arrive early in mid-segment crossovers. Hyundai and Zeiss are developing a full-windshield holographic HUD for mainstream Tucson and Santa Fe models, aiming for 2027 production and signaling that the technology curve will continue to bend toward volume platforms. As attachment rates rise, tier-1 suppliers, in the head-up display market, must balance optical innovation with aggressive cost engineering to secure program awards across multiple price tiers.
Stringent Safety Regulations Mandating Driver Information Systems
UN Regulation 171 specifies handover prompts and driver-availability confirmations that benefit from gaze-aligned visual alerts, making HUDs a compliance accelerant in Level 2 and Level 3 automation programs. In the United States, FMVSS 127 requires collision-warning symbols to reside within a tight sight-line envelope, a target naturally met by windshield projection. Euro NCAP's Driver Engagement Protocol, released in March 2025, awards higher ratings to vehicles that display automation status via augmented reality overlays, making safety scoring a competitive marketing lever. These mandates are arriving quickly, forcing OEMs to integrate HUD hardware during base-platform development rather than as an optional afterthought. Suppliers that can certify luminance, ghost-image, and eyebox parameters under ISO/TS 21957 now win preferred-vendor status in new model programs across three continents in HUD market.
Persistent High System Cost for Full-Windshield AR HUDs
Full-windshield projection demands holographic optical elements, laser diode arrays, and continuous driver-eye tracking, driving the bill of materials above USD 1,000 and restricting adoption to ultra-luxury models. BMW's Panoramic Vision, applied as a projection film across the entire windshield, remains an extra-cost option rather than standard equipment, illustrating OEM caution in absorbing these costs. Even with waveguides, production windshields must meet tight distortion limits, raising glass-sourcing expenses and extending validation schedules. The price barrier is especially severe in India, where ADAS penetration was only 8.3% in early 2025, leaving little budget headroom for premium cockpit features. Until component pricing falls sharply, mass-market vehicles will continue to rely on smaller windshield zones or combiner-based solutions.
Other drivers and restraints analyzed in the detailed report include:
- Accelerated Adoption of Electric and Software-Defined Vehicles
- Component Cost Reduction through Waveguide and MicroLED Optics
- Growing Competition from Smart Glasses and Mixed Reality Headsets
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Windshield-integrated projection held 56.00% of 2025 revenue share in the head-up display market, as OEMs favored its larger virtual image and cleaner dashboard layout. That dominance will continue, yet the augmented reality subset is forecast to log a 19.40% CAGR through 2031, adding sensor-anchored arrows, hazard framing, and lane cues that elevate situational awareness. The head-up display market size for windshield units will therefore rise in absolute terms even as AR gains mix, creating dual demand streams for both conventional and holographic designs
AR HUD demand is reinforced by BMW's plan to equip every Neue Klasse vehicle with a 3D overlay option by late 2025, setting a de facto standard for premium interiors. Tier-1 suppliers now quote sub-USD 300 bill-of-materials targets for waveguide designs, enabling mid-segment adoption without sacrificing margin. Combiner-type add-ons will linger in price-sensitive geographies, yet their share will erode as OEMs push integrated solutions that can be updated over the air and calibrated to ADAS sensors.
Two-dimensional imaging retained a 61.50% share in 2025 in the head-up display market, yet 3D HUDs are projected to compound at 21.30% annually as Level 2 and Level 3 automation expand. Depth-separated layers present battery charge, speed, and automation mode close to the driver, while turn arrows and obstacle boxes appear 10-20 m ahead, cutting refocus time.
BMW's 3D Head-Up Display demonstrates how dual-plane holography works in production, integrating with driver-monitor cameras to adapt imagery as head position shifts. Suppliers must therefore couple optics expertise with real-time gaze tracking and GPU-based rendering. Those that can do so within EV power budgets will earn an outsized share of upcoming model awards, lifting the head-up display market share for 3D solutions over the forecast window.
Complete Report Scope:
- By HUD Type
- Windshield-Based HUD
- Combiner-Based HUD
- Augmented Reality HUD
- By Dimension Type
- 2D HUD
- 3D HUD
- By Vehicle Class
- Commercial Vehicles
- Passenger Vehicles
- By Sales Channel
- OEM-Fitted
- Aftermarket
- By Application
- Automotive
- Military and Civil Aviation
- Others (Industrial, Wearable, and other Displays)
- Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Rest of South America
- Europe
- United Kingdom
- Germany
- France
- Rest of Europe
- Asia-Pacific
- China
- Japan
- South Korea
- India
- Rest of Asia-Pacific
- Middle East
- GCC
- Rest of Middle East
- Africa
- South Africa
- Rest of Africa
- North America
Geography Analysis
Asia-Pacific held 38.90% of global revenue in 2025 and is forecast to grow at a 12.30% CAGR through 2031, buoyed by China's electric-vehicle production boom and Japan's export strength in optoelectronics. Local brands like Xpeng, NIO, and Li Auto embed large AR images to stand out in a hypercompetitive domestic arena, accelerating feature diffusion down the price ladder. South Korea's display ecosystem supplies waveguides and MicroLEDs at scale, compressing cost curves for regional automakers.
North America benefits from high luxury penetration and early software-defined architectures, although Section 301 tariffs on Chinese optics add 25% landed cost, prompting dual sourcing from Europe and Southeast Asia. U.S. federal rules on collision-warning visualization mandate HUD-friendly sight-line placement, nudging OEMs toward integrated projection. Canada's parts suppliers align with these programs to keep assembly plants fully utilized despite tariff turbulence.
Europe marries stringent safety scoring with prestige brands that view cockpit digitalization as a hallmark. Euro NCAP's 2025 engagement protocol rewards AR overlays, pushing Volkswagen, Mercedes-Benz, and BMW to accelerate full-windshield roadmaps. Yet the region also grapples with higher homologation costs for advanced optics. Emerging markets in the Middle East and Africa explore HUD for autonomous shuttle pilots, but harsh climate conditions and price sensitivity keep uptake modest for now.
- Denso Corporation
- Nippon Seiki Co., Ltd.
- Panasonic Automotive Systems
- Visteon Corporation
- Continental AG
- Robert Bosch GmbH
- Valeo SE
- BAE Systems PLC
- Thales Group
- Garmin Ltd.
- Elbit Systems Ltd.
- Pioneer Corporation
- SaaB AB
- Hudway LLC
- Collins Aerospace
- LG Display Co., Ltd.
- Harman International
- WayRay AG
- Envisics Ltd.
- Texas Instruments Incorporated
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 NTRODUCTION
- 1.1 Study Assumptions
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Industry Supply-Chain Analysis
- 4.3 Porter's Five Forces Analysis
- 4.3.1 Threat of New Entrants
- 4.3.2 Bargaining Power of Buyers
- 4.3.3 Bargaining Power of Suppliers
- 4.3.4 Threat of Substitute Products
- 4.3.5 Intensity of Competitive Rivalry
- 4.4 Impact of Macroeconomic Factors on the Market
- 4.5 Technological Outlook
- 4.6 Regulatory Landscape
5 MARKET DRIVERS
- 5.1 Rising Integration of Augmented Reality HUDs in Mid-Range Vehicles
- 5.2 Stringent Safety Regulations Mandating Driver Information Systems
- 5.3 Accelerated Adoption of Electric and Software-Defined Vehicles
- 5.4 Component Cost Reduction through Waveguide and MicroLED Optics
- 5.5 Monetization of HUD Software via Subscription-Based Feature Unlocks
- 5.6 Automotive Tier-1 Semiconductor Co-Design Partnerships Shortening HUD Development Cycles
6 MARKET RESTRAINTS
- 6.1 Persistent High System Cost for Full-Windshield AR HUDs
- 6.2 Limited Field of View and Windshield Compatibility Constraints
- 6.3 Tariff-Driven Optics and IC Supply Risks in North America
- 6.4 Growing Competition from Smart Glasses and Mixed Reality Headsets
7 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 7.1 By HUD Type
- 7.1.1 Windshield-Based HUD
- 7.1.2 Combiner-Based HUD
- 7.1.3 Augmented Reality HUD
- 7.2 By Dimension Type
- 7.2.1 2D HUD
- 7.2.2 3D HUD
- 7.3 By Vehicle Class
- 7.3.1 Commercial Vehicles
- 7.3.2 Passenger Vehicles
- 7.4 By Sales Channel
- 7.4.1 OEM-Fitted
- 7.4.2 Aftermarket
- 7.5 By Application
- 7.5.1 Automotive
- 7.5.2 Military and Civil Aviation
- 7.5.3 Others (Industrial, Wearable, and other Displays)
- 7.6 Geography
- 7.6.1 North America
- 7.6.1.1 United States
- 7.6.1.2 Canada
- 7.6.1.3 Mexico
- 7.6.2 South America
- 7.6.2.1 Brazil
- 7.6.2.2 Argentina
- 7.6.2.3 Rest of South America
- 7.6.3 Europe
- 7.6.3.1 United Kingdom
- 7.6.3.2 Germany
- 7.6.3.3 France
- 7.6.3.4 Rest of Europe
- 7.6.4 Asia-Pacific
- 7.6.4.1 China
- 7.6.4.2 Japan
- 7.6.4.3 South Korea
- 7.6.4.4 India
- 7.6.4.5 Rest of Asia-Pacific
- 7.6.5 Middle East
- 7.6.5.1 GCC
- 7.6.5.2 Rest of Middle East
- 7.6.6 Africa
- 7.6.6.1 South Africa
- 7.6.6.2 Rest of Africa
- 7.6.1 North America
8 COMPETITIVE LANDSCAPE
- 8.1 Strategic Moves
- 8.2 Market Share Analysis
- 8.3 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for Key Companies, Products and Services, and Recent Developments)
- 8.3.1 Denso Corporation
- 8.3.2 Nippon Seiki Co., Ltd.
- 8.3.3 Panasonic Automotive Systems
- 8.3.4 Visteon Corporation
- 8.3.5 Continental AG
- 8.3.6 Robert Bosch GmbH
- 8.3.7 Valeo SE
- 8.3.8 BAE Systems PLC
- 8.3.9 Thales Group
- 8.3.10 Garmin Ltd.
- 8.3.11 Elbit Systems Ltd.
- 8.3.12 Pioneer Corporation
- 8.3.13 SaaB AB
- 8.3.14 Hudway LLC
- 8.3.15 Collins Aerospace
- 8.3.16 LG Display Co., Ltd.
- 8.3.17 Harman International
- 8.3.18 WayRay AG
- 8.3.19 Envisics Ltd.
- 8.3.20 Texas Instruments Incorporated
9 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 9.1 White-Space and Unmet-Need Assessment

