PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2123438

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2123438
Rubber Conveyor Belt - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
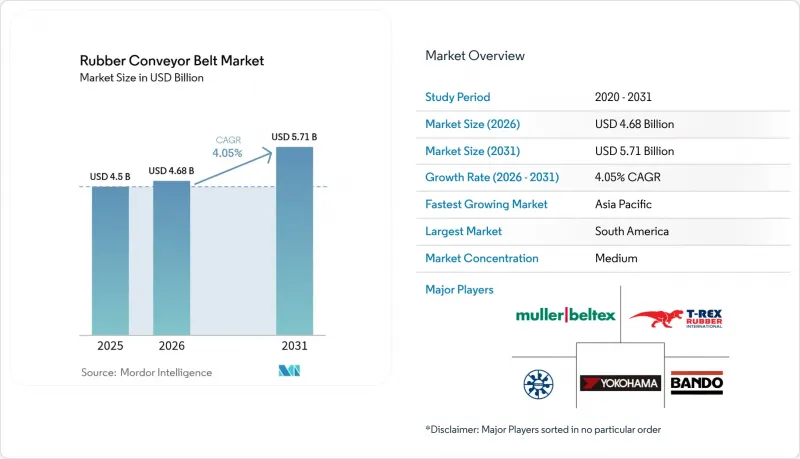
According to Mordor Intelligence, rubber conveyor belt market size in 2026 is estimated at USD 4.68 billion, growing from 2025 value of USD 4.5 billion with 2031 projections showing USD 5.71 billion, growing at 4.05% CAGR over 2026-2031.
This report is Segmented by Belt Type (Heat-Resistant, Oil-Resistant and More), Belt Weight, Reinforcement Material (Textile / Fabric Carcass, Steel Cord and Solid-Woven), End-User Industry (Logistics & Warehousing, Mining & Quarrying and More), and by Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global Rubber Conveyor Belt Market Trends and Insights
Surge in High-Temperature Battery-Metals Processing in Asia Boosting Heat-Resistant Belts
Cathode and precursor plants across China, Korea, and Indonesia increasingly operate reactors above 200°C, driving rapid uptake of graphene-nanotube-enhanced belts that combine thermal stability with static dissipation. These belts allow processors to raise throughput without adding cooling capacity, and the resulting productivity gain is convincing vertically integrated miners to lock in multi-year supply agreements. A fresh inference is that early certification of high-heat compounds now serves as a proxy for project schedule reliability.
Automated Micro-Fulfilment Warehouses in North America Driving Lightweight Belt Demand
Urban micro-fulfilment centers occupy footprints under 10,000 sq ft and rely on compact lightweight belts that twist, climb, and stop within millimetres. Operators switching from multi-ply to single-ply constructions report energy savings exceeding 20%, highlighting how belt mass influences total operating cost. Because labour shortages persist, gains in picking accuracy linked to low-stretch fabrics directly elevate revenue per square foot, placing materials science at the heart of warehouse economics.
Expansion of Solar-PV Manufacturing Clusters in India Requiring Oil-Resistant Belts
A planned 6 GW solar-module plant in Odisha will employ oil-resistant belts to handle plasticisers and encapsulants that degrade conventional covers. Pairing nitrile blends with abrasion-resistant carcasses prevents delamination, cutting unplanned downtime. This linkage between specialty chemistry and renewable-energy rollout underscores how national industrial policy can redirect rubber conveyor belt market size toward premium variants.
Other drivers and restraints analyzed in the detailed report include:
- "Pit-to-Plant" Conveyor Retrofits in South American Copper Mines Elevating Replacement Cycle
- EU 2023/1115 Mandating Flame-Retardant Belts in Recycling Plants
- IoT-Enabled Condition-Monitoring Unlocking Pay-Per-Ton Service Contracts
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Heat-resistant belts held 28.65% of the rubber conveyor belt market share in 2025. Advances in silica-rich compounds let these belts run continuously above 200 °C, enabling kiln operators to raise furnace set-points and unlock throughput gains. Fewer thermal cracks mean shorter maintenance shutdowns, an outcome that expands effective plant availability. Fire-resistant variants are forecast to grow at a 5.65% CAGR between 2026-2031, fuelled by underground-mine safety codes and EU recycling mandates. Belts achieving Type A or B certification under CAN/CSA-M422 command premiums, and many sites now specify only these grades, elevating barriers for non-certified competitors.
Medium-weight belts provided 44.35% of the rubber conveyor belt market size in 2025. Polyester-nylon carcasses balance strength and flexibility, letting parcel hubs extend belt life without upgrading drives. The resulting energy savings and lower structural-steel requirements reinforce payback, especially where electricity tariffs are high. Heavy-weight belts are projected to post a 5.32% CAGR as mines adopt longer overland conveyors. Goodyear's extra-stiff polyester/nylon designs minimise stretch on multi-kilometre flights, keeping sag within design limits. Lower elongation allows single-flight layouts that reduce the number of transfer points, cutting dust emissions and maintenance hours.
Complete Report Scope:
- By Belt Type
- Heat-Resistant
- Oil-Resistant
- Fire-Resistant
- Chemical-Resistant
- General-Purpose
- By Belt Weight
- Lightweight
- Medium-Weight
- Heavy-Weight
- By Reinforcement Material
- Textile / Fabric Carcass
- Steel Cord
- Solid-Woven
- By End-user Industry
- Logistics and Warehousing
- Mining and Quarrying
- Manufacturing (Discrete and Process)
- Metal Processing and Steel Mills
- Power Generation (Thermal and Biomass)
- Food and Beverage
- Construction and Aggregates
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Rest of South America
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- South Korea
- India
- Australia
- New Zealand
- Rest of Asia-Pacific
- Middle East and Africa
- United Arab Emirates
- Saudi Arabia
- South Africa
- Rest of Middle East and Africa
- North America
Geography Analysis
Asia dominated with 33.55% of 2025 revenue, propelled by China's large manufacturing base and India's infrastructure push. Access to natural rubber feedstock from Thailand and Malaysia buffers cost shocks, giving regional producers an input advantage. Policy incentives for battery-metal refining and solar-module manufacturing channel belt demand toward heat- and oil-resistant variants, effectively concentrating growth in specialised niches.
South America is forecast to record the highest 6.07% CAGR to 2031. Major copper projects in Chile, Peru, and Brazil are replacing haul trucks with overland conveyors, driving large orders for heavy-duty steel-cord belts. Antamina's USD 2 billion life-extension dedicates substantial capital to new conveyors, and suppliers that offer sidewall or steep-angle designs are capturing premium contracts. The region's commitment to renewable power for mines further raises interest in low-stretch belts that cut energy draw.
North America and Europe retain significant shares, but for different reasons. North American warehouses prioritise predictive uptime and thus purchase sensor-equipped belts, while European factories focus on low-nitrosamine formulations to meet health standards. The Middle East and Africa remain nascent yet promising: rail projects and iron-ore mines require belts that withstand high heat and abrasive dust, pushing buyers toward blended synthetic-natural rubbers with UV-stable covers.
- Bridgestone Corporation
- Continental AG (ContiTech and Phoenix)
- The Yokohama Rubber Co. Ltd.
- Fenner Dunlop Holdings Ltd. (Michelin Conveyor Solutions)
- Bando Chemical Industries Ltd.
- Sempertrans (Semperit AG)
- Dunlop Conveyor Belting
- Qingdao Rubber Six Conveyor Belt Co.
- Zhejiang Double Arrow Rubber Co.
- Oriental Rubber Industries Pvt. Ltd.
- Oxford Rubbers Pvt. Ltd.
- Muller Beltex B.V.
- T-Rex Rubber International B.V.
- Mitsuboshi Belting Ltd.
- Wuxi Boton Belt Co. Ltd.
- Truco Group
- Smiley Monroe Ltd.
- GRT Rubber Technologies
- Continental Belting Pvt. Ltd.
- Probelt Global Ltd.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Surge in High-Temperature Battery-Metals Processing in Asia Boosting Heat-Resistant Belts
- 4.2.2 Automated Micro-Fulfillment Warehouses in North America Driving Lightweight Belt Demand
- 4.2.3 Pit-to-Plant Conveyor Retrofits in South American Copper Mines Elevating Replacement Cycle
- 4.2.4 EU 2023/1115 Mandating Flame-Retardant Belts in Recycling Plants
- 4.2.5 Expansion of Solar-PV Manufacturing Clusters in India Requiring Oil-Resistant Belts
- 4.2.6 IoT-Enabled Condition-Monitoring Unlocking Pay-Per-Ton Service Contracts
- 4.3 Market Restraints
- 4.3.1 Volatility in Butadiene and Carbon Black Prices Compressing Margins
- 4.3.2 PVC and Modular Belt Substitution in European Food Processing
- 4.3.3 Certification Lead-Times for UL/CSA Flame Tests in North America
- 4.3.4 EU Scrutiny of Nitrosamine Exposure During Vulcanization
- 4.4 Value / Supply-Chain Analysis
- 4.5 Regulatory Outlook
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Buyers/Consumers
- 4.7.3 Bargaining Power of Suppliers
- 4.7.4 Threat of Substitute Products
- 4.7.5 Intensity of Competitive Rivalry
- 4.8 Investment Analysis (Capex, MandA, VC Funding)
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Belt Type
- 5.1.1 Heat-Resistant
- 5.1.2 Oil-Resistant
- 5.1.3 Fire-Resistant
- 5.1.4 Chemical-Resistant
- 5.1.5 General-Purpose
- 5.2 By Belt Weight
- 5.2.1 Lightweight
- 5.2.2 Medium-Weight
- 5.2.3 Heavy-Weight
- 5.3 By Reinforcement Material
- 5.3.1 Textile / Fabric Carcass
- 5.3.2 Steel Cord
- 5.3.3 Solid-Woven
- 5.4 By End-user Industry
- 5.4.1 Logistics and Warehousing
- 5.4.2 Mining and Quarrying
- 5.4.3 Manufacturing (Discrete and Process)
- 5.4.4 Metal Processing and Steel Mills
- 5.4.5 Power Generation (Thermal and Biomass)
- 5.4.6 Food and Beverage
- 5.4.7 Construction and Aggregates
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 South America
- 5.5.2.1 Brazil
- 5.5.2.2 Argentina
- 5.5.2.3 Rest of South America
- 5.5.3 Europe
- 5.5.3.1 Germany
- 5.5.3.2 United Kingdom
- 5.5.3.3 France
- 5.5.3.4 Italy
- 5.5.3.5 Spain
- 5.5.3.6 Rest of Europe
- 5.5.4 Asia-Pacific
- 5.5.4.1 China
- 5.5.4.2 Japan
- 5.5.4.3 South Korea
- 5.5.4.4 India
- 5.5.4.5 Australia
- 5.5.4.6 New Zealand
- 5.5.4.7 Rest of Asia-Pacific
- 5.5.5 Middle East and Africa
- 5.5.5.1 United Arab Emirates
- 5.5.5.2 Saudi Arabia
- 5.5.5.3 South Africa
- 5.5.5.4 Rest of Middle East and Africa
- 5.5.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Strategic Moves (Partnerships, Expansions, M&A)
- 6.2 Market Share Analysis
- 6.3 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.3.1 Bridgestone Corporation
- 6.3.2 Continental AG (ContiTech and Phoenix)
- 6.3.3 The Yokohama Rubber Co. Ltd.
- 6.3.4 Fenner Dunlop Holdings Ltd. (Michelin Conveyor Solutions)
- 6.3.5 Bando Chemical Industries Ltd.
- 6.3.6 Sempertrans (Semperit AG)
- 6.3.7 Dunlop Conveyor Belting
- 6.3.8 Qingdao Rubber Six Conveyor Belt Co.
- 6.3.9 Zhejiang Double Arrow Rubber Co.
- 6.3.10 Oriental Rubber Industries Pvt. Ltd.
- 6.3.11 Oxford Rubbers Pvt. Ltd.
- 6.3.12 Muller Beltex B.V.
- 6.3.13 T-Rex Rubber International B.V.
- 6.3.14 Mitsuboshi Belting Ltd.
- 6.3.15 Wuxi Boton Belt Co. Ltd.
- 6.3.16 Truco Group
- 6.3.17 Smiley Monroe Ltd.
- 6.3.18 GRT Rubber Technologies
- 6.3.19 Continental Belting Pvt. Ltd.
- 6.3.20 Probelt Global Ltd.
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK

