PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2123786

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2123786
Cough Remedies - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
According to Mordor Intelligence, the cough remedies market size is expected to grow from USD 11.15 billion in 2025 to USD 11.82 billion in 2026 and is forecast to reach USD 22.65 billion by 2031 at 6.04% CAGR over 2026-2031.
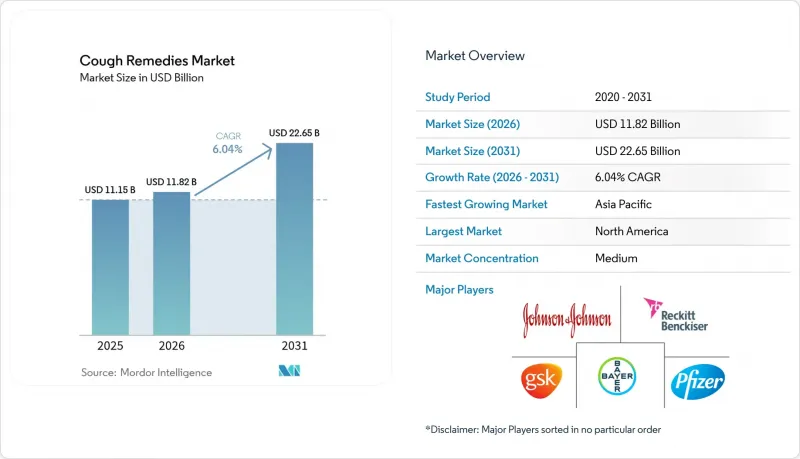
This report is Segmented by Product Type (Antitussives, Expectorants, Mucolytics, and More), Dosage Form (Syrup/Linctus, Tablets & Capsules, and More), Age Group (Pediatrics & Adolescents, Adults, and Geriatrics), Distribution Channel (Retail Pharmacies, and More), and Geography (North America, Europe, Asia-Pacific, and More). The Market Forecasts are Provided in Terms of Value (USD).
Global Cough Remedies Market Trends and Insights
Growing Global Burden of Respiratory Diseases
More than 569 million people lived with chronic respiratory ailments in 2023, and respiratory infections remained the fourth-leading global cause of mortality. Urban air pollution in megacities such as Delhi and Beijing is driving up COPD and asthma incidence, while aging populations in Europe and Japan are expanding the pool of people requiring long-term cough control. Drug makers are answering by reformulating legacy products to limit side effects and by launching multi-symptom combinations that address allergic rhinitis or post-viral irritation, thereby increasing per-episode spending.
Expanding Over-The-Counter Drug Accessibility
Regulators increasingly view pharmacist-guided OTC access as a path to relieve overstretched clinics. The U.S. Food and Drug Administration authorized several bronchodilator inhalers for non-prescription sale in 2024, and Japan's health ministry broadened OTC expectorant categories in 2025. Lower barriers cut time-to-market for generics and let manufacturers divert marketing budgets from physician detailing to consumer-centric digital campaigns.
Safety Concerns Around Opioid- and Codeine-Based Formulations
The FDA and European regulators tightened warnings on codeine cough syrups after sustained reports of misuse and respiratory depression, culminating in shelf withdrawals by several U.K. and German retailers in 2025. Dextromethorphan, though non-opioid, now faces age-restriction laws in multiple U.S. states due to adolescent abuse cases. Manufacturers are accelerating pivots to honey-based suppressants and botanical alternatives, although evidence standards remain under debate.
Other drivers and restraints analyzed in the detailed report include:
- Growth of E-Pharmacies and Digital Retail Platforms
- Adoption of AI-Based Symptom-Triage Apps Driving Targeted Self-Medication
- Supply-Chain Vulnerability to Climate-Related Botanical Shortages
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Bronchodilators are projected to rise at a 8.54% CAGR, well above the overall cough remedies market. OTC approval of low-dose beta-agonist inhalers in Japan and South Korea lets COPD patients manage mild flare-ups without clinic visits, moving a traditionally prescription category into retail space. Expectorants accounted for 32.65% of 2025 revenue, led by guaifenesin syrups and herbal variants such as licorice and ivy. Antitussives face codeine-related headwinds, prompting reformulation with honey, marshmallow, and other naturals. Combination cold-and-cough packs are proliferating as retailers favor SKUs that deliver multi-symptom coverage within limited shelf space.
Second-order impacts include rising R&D around abuse-deterrent polymers for dextromethorphan and extended-release bead technology that keeps blood levels stable overnight. Differential positioning is clear: evidence-backed bronchodilators and mucolytics appeal to physicians, whereas botanically formulated expectorants and antitussives attract wellness-oriented consumers. Flexible brand architecture that addresses both cohorts is becoming a strategic necessity.
Syrups still accounted for 39.54% of the cough remedies market in 2025, yet gummy and chewable formats are forecast to expand by 8.76% annually as child-friendly flavors curb dosing resistance. Tablets and capsules dominate adult usage because portability offsets slower onset, and lozenges fill the niche for throat-soothing menthol or benzocaine. Rapid-dissolve herbal film strips have received pediatric approvals in India and parts of Southeast Asia, offering sublingual uptake and eliminating the need to swallow.
Investment momentum is strong: Reckitt Benckiser commissioned new gummy lines in 2025, and Haleon piloted orally disintegrating tablets for its Robitussin franchise. Contract manufacturers with expertise in pectin-based or vegan gelatin command premium valuations as brands outsource specialized production.
Complete Report Scope:
- By Product Type
- Antitussives (Opioid & Non-Opioid)
- Expectorants
- Mucolytics
- Bronchodilators
- Antihistamines
- Decongestants
- Combination Medications
- Other Product Types
- By Dosage Form
- Syrup / Linctus
- Tablets & Capsules
- Lozenges / Pastilles
- Nasal Drops / Sprays
- Gummies & Confectionery
- Balms / Inhalers
- By Age Group
- Pediatrics & Adolescents (Below 18 Years)
- Adults (18-60 Years)
- Geriatrics (Above 60 Years)
- By Distribution Channel
- Retail Pharmacies
- Hospital / Clinic Pharmacies
- Online / E-Pharmacies
- Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- Australia
- South Korea
- Rest of Asia-Pacific
- Middle East & Africa
- GCC
- South Africa
- Rest of Middle East & Africa
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
North America generated 42.76% of global revenue in 2025, underpinned by high health-spending elasticity, brand loyalty to heritage labels, and extensive pharmacy networks. Growth is steady rather than explosive as the region approaches saturation, yet innovation in naturals and digital-ecosystem tie-ins helps sustain premium price points. The FDA's move to allow OTC bronchodilators opened a previously out-of-reach secondary prevention segment, while Canada's inclusion of certain cough syrups in public drug plans widened access for low-income groups.
Asia-Pacific is the fastest-expanding region, projected to grow at a 7.54% CAGR to 2031, and now contributes a rising share of total cough remedies market revenue. Urban air pollution and smartphone ubiquity spur both incidence and digital-first purchasing behaviors. China's dual structure separates traditional Chinese medicine (TCM) dominance in rural areas from Western synthetic medicine preferred by urban millennials. In India, Ayurvedic leaders leverage rural distribution muscle, while multinationals cluster around e-commerce growth in metros. Mature Japan and South Korea see demand lift from aging COPD patients and national insurance systems that reimburse select OTC respiratory therapies. Regulatory heterogeneity across ASEAN continues to complicate product registration, but ongoing harmonization efforts promise smoother pan-regional launches within three years.
Europe's scene blends strict pharmacovigilance with a strong herbal tradition, especially in Germany, where ivy leaf and thyme syrups share shelf space with synthetic brands. The European Medicines Agency's 2025 clampdown on codeine shortened the lifecycles of legacy products, shifting volume to naturals and combination packs. South America and the Middle East & Africa remain smaller contributors today, yet Gulf Cooperation Council retail expansion and Mercosur regulatory alignment are setting a foundation for mid-term acceleration. Currency volatility in Brazil and Argentina gives domestic producers a price advantage over imports, while Africa's nascent e-pharmacy models aim to bypass infrastructure gaps and counterfeit risks alike.
- AstraZeneca
- Bayer
- Boehringer Ingelheim
- Boiron Group
- Church & Dwight Co.
- Cipla
- Dabur
- Engelhard Arzneimittel GmbH & Co. KG
- GlaxoSmithKline
- Haleon Plc
- Himalaya Wellness Co.
- Hisamitsu Pharmaceutical Co.
- Johnson & Johnson
- Novartis SA
- Otsuka Pharmaceutical Co.
- Perrigo Company
- Pfizer
- Prestige Consumer Healthcare
- Procter & Gamble
- Reckitt Benckiser Group
- Sanofi
- Sun Pharmaceuticals Industries
- Takeda Pharmaceutical Co.
- Tris Pharma Inc.
- Viatris
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope Of The Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Growing Global Burden of Respiratory Diseases
- 4.2.2 Expanding Over-The-Counter Drug Accessibility
- 4.2.3 Rising Consumer Preference for Self-Care Healthcare
- 4.2.4 Growth of E-Pharmacies and Digital Retail Platforms
- 4.2.5 Adoption of AI-Based Symptom-Triage Apps Driving Targeted Self-Medication
- 4.2.6 Emergence of Rapid-Dissolve Herbal Film Strips for Pediatrics
- 4.3 Market Restraints
- 4.3.1 Stringent Regulatory Framework for Active Pharmaceutical Ingredients
- 4.3.2 Safety Concerns Around Opioid- and Codeine-Based Formulations
- 4.3.3 Supply-Chain Vulnerability to Climate-Related Botanical Shortages
- 4.3.4 Rising Consumer Skepticism Toward Synthetic Cough Suppressants
- 4.4 Value / Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Threat Of New Entrants
- 4.7.2 Bargaining Power Of Buyers
- 4.7.3 Bargaining Power Of Suppliers
- 4.7.4 Threat Of Substitutes
- 4.7.5 Competitive Rivalry
5 Market Size & Growth Forecasts (Value, USD)
- 5.1 By Product Type
- 5.1.1 Antitussives (Opioid & Non-Opioid)
- 5.1.2 Expectorants
- 5.1.3 Mucolytics
- 5.1.4 Bronchodilators
- 5.1.5 Antihistamines
- 5.1.6 Decongestants
- 5.1.7 Combination Medications
- 5.1.8 Other Product Types
- 5.2 By Dosage Form
- 5.2.1 Syrup / Linctus
- 5.2.2 Tablets & Capsules
- 5.2.3 Lozenges / Pastilles
- 5.2.4 Nasal Drops / Sprays
- 5.2.5 Gummies & Confectionery
- 5.2.6 Balms / Inhalers
- 5.3 By Age Group
- 5.3.1 Pediatrics & Adolescents (Below 18 Years)
- 5.3.2 Adults (18-60 Years)
- 5.3.3 Geriatrics (Above 60 Years)
- 5.4 By Distribution Channel
- 5.4.1 Retail Pharmacies
- 5.4.2 Hospital / Clinic Pharmacies
- 5.4.3 Online / E-Pharmacies
- 5.5 Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 Europe
- 5.5.2.1 Germany
- 5.5.2.2 United Kingdom
- 5.5.2.3 France
- 5.5.2.4 Italy
- 5.5.2.5 Spain
- 5.5.2.6 Rest of Europe
- 5.5.3 Asia-Pacific
- 5.5.3.1 China
- 5.5.3.2 Japan
- 5.5.3.3 India
- 5.5.3.4 Australia
- 5.5.3.5 South Korea
- 5.5.3.6 Rest of Asia-Pacific
- 5.5.4 Middle East & Africa
- 5.5.4.1 GCC
- 5.5.4.2 South Africa
- 5.5.4.3 Rest of Middle East & Africa
- 5.5.5 South America
- 5.5.5.1 Brazil
- 5.5.5.2 Argentina
- 5.5.5.3 Rest of South America
- 5.5.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Market Share Analysis
- 6.3 Company Profiles {(Includes Global Level Overview, Market Level Overview, Core Segments, Financials as Available, Strategic Information, Market Rank/Share for Key Companies, Products & Services, and Recent Developments)}
- 6.3.1 AstraZeneca Plc
- 6.3.2 Bayer AG
- 6.3.3 Boehringer Ingelheim GmbH
- 6.3.4 Boiron Group
- 6.3.5 Church & Dwight Co.
- 6.3.6 Cipla
- 6.3.7 Dabur
- 6.3.8 Engelhard Arzneimittel GmbH & Co. KG
- 6.3.9 GSK Plc
- 6.3.10 Haleon Plc
- 6.3.11 Himalaya Wellness Co.
- 6.3.12 Hisamitsu Pharmaceutical Co.
- 6.3.13 Johnson & Johnson
- 6.3.14 Novartis SA
- 6.3.15 Otsuka Pharmaceutical Co.
- 6.3.16 Perrigo Company Plc
- 6.3.17 Pfizer Inc.
- 6.3.18 Prestige Consumer Healthcare Inc.
- 6.3.19 Procter & Gamble Co.
- 6.3.20 Reckitt Benckiser Group Plc
- 6.3.21 Sanofi S.A
- 6.3.22 Sun Pharmaceutical Industries Ltd.
- 6.3.23 Takeda Pharmaceutical Co.
- 6.3.24 Tris Pharma Inc.
- 6.3.25 Viatris Inc.
7 Market Opportunities & Future Outlook
- 7.1 White-Space & Unmet-Need Assessment

