PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2124092

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2124092
Emotion Analytics - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
According to Mordor Intelligence, the emotion analytics market size is estimated at USD 5.02 billion in 2026, and is expected to reach USD 7.70 billion by 2031, at a CAGR of 8.93% during the forecast period (2026-2031).
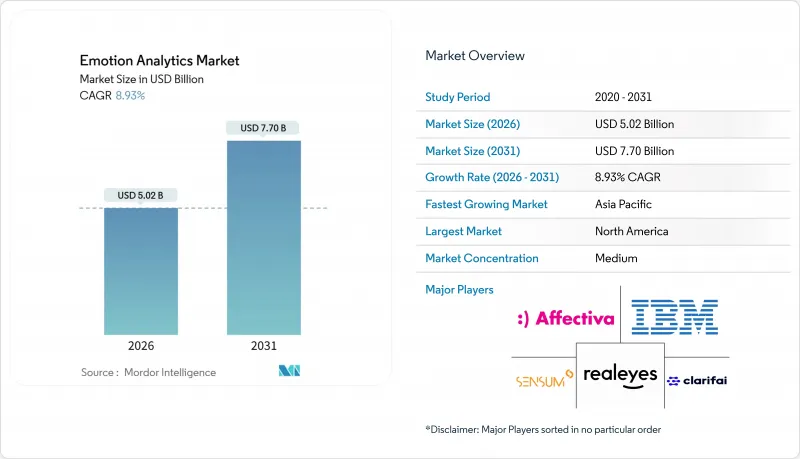
This report is Segmented by Deployment (On-Premise, Cloud, and More), Component (Software, Hardware, and Services), Analytics Modality (Facial Emotion Recognition, Video-Based Multimodal, and More), Application (Customer Service and Contact Centers, Product and Market Research, and More), and Geography. The Market Forecasts are in Value (USD)
Global Emotion Analytics Market Trends and Insights
Proliferation of IoT Wearables and Smart Devices
Wearable emotion-sensing hardware has scaled from laboratory prototypes to enterprise rollouts, exemplified by the Emotiv EPOC X, a 14-channel electroencephalography headset priced at USD 999 that now ships for workplace stress audits and user experience trials. The BIOPAC Research Ring combines galvanic skin response, photoplethysmography, electrocardiogram, temperature, and accelerometer streams into a single form factor, delivering continuous affect tracking without chest straps or facial cameras. A December 2025 Nature Scientific Data paper introduced the LLaMAC dataset that fuses Epoc-X and Empatica E4 signals with synchronized video and audio to train multimodal emotion models. Physiological signals, such as heart rate variability and skin conductance, exhibit greater cross-population consistency than facial cues, thereby reducing demographic bias. On-device inference further limits latency and data-leak risk by removing the need to stream raw biosignals to cloud servers.
Advances in Deep-Learning-Based Computer Vision and Natural Language Processing
Transformer architectures and self-supervised pre-training have reduced the need for labeled data, allowing vendors to fine-tune foundation models on call-center audio, clinical interviews, or in-cabin driver videos with far fewer annotations than their convolutional predecessors. Google Cloud's Conversational Insights surfaces sentiment, intent, and escalation cues from live audio, while Microsoft Azure AI offers pre-built sentiment APIs that parse text, speech, and video, reducing barriers for firms lacking machine-learning staff. Real-time emotion routing lowers handle time and boosts throughput in contact centers, turning potential churn into loyalty gains. Text analysis also tracks brand perception across social media, product reviews, and surveys within minutes. Together, these advances extend affective computing from isolated pilots to routine business workflows.
Stringent Data-Privacy Regulations (GDPR, CPRA, etc.)
General Data Protection Regulation Article 9 treats biometric inference as sensitive data, demanding explicit consent, purpose limitation, and strict retention windows. The California Privacy Rights Act imposes similar rules on biometric identifiers, adding deletion rights and algorithmic-decision explanations. The forthcoming European Union Artificial Intelligence Act will categorize school and workplace emotion analytics as high risk, requiring conformity assessments and post-market monitoring. Compliance overhead raises deployment costs and delays procurement for small firms. Privacy-preserving tools such as federated learning and homomorphic encryption mitigate exposure but add latency and compute expense, slowing global rollouts.
Other drivers and restraints analyzed in the detailed report include:
- Demand for Hyper-Personalized Customer Engagement Tools
- Regulatory Mandate for Driver-Monitoring Systems (EU GSR 2024)
- Bias and Accuracy Issues in Facial-Emotion Data Sets
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Edge and on-device deployment is projected to advance at a 10.11% CAGR between 2026 and 2031 as enterprises push inference closer to sensors to satisfy data-sovereignty mandates and millisecond-level latency targets. Cloud architectures still held 54.57% of the emotion analytics market share in 2025 thanks to elastic compute and centralized model updates. However, round-trip delays make cloud impractical for safety-critical driver monitoring or tele-mental-health sessions that require sub-second feedback. On-premise stacks appeal to banks and hospitals that ban biometric data egress, yet they demand capital outlays for local accelerators and skilled machine-learning staff.
Technical progress is lowering the hurdles to run models at the edge. The open-source BioGAP-Ultra platform, published in 2025, processes electroencephalography, electromyography, electrocardiogram, and photoplethysmography streams on low-power microcontrollers, proving that accurate emotion inference can run without cloud connectivity. Federated-learning toolkits let thousands of devices co-train a shared model while keeping raw data local, cutting bandwidth cost and helping firms comply with General Data Protection Regulation Article 9. As chip makers add neural-processing units to standard system-on-chip designs and model-compression methods shrink footprints, the economic gap between edge and cloud continues to close.
Hardware sensors, including cameras, electroencephalography headsets, galvanic skin response rings, and electrocardiogram modules, are forecast to grow at a 9.43% CAGR through 2031, the fastest rate among all component groups. Software layers (software development kits, application programming interfaces, and managed dashboards) captured 45.72% of the emotion analytics market size in 2025, reflecting the early ease of spinning up cloud APIs. Service offerings that bundle integration and custom model training expand in parallel as buyers seek turnkey rollouts.
Regulation and wearable adoption explain hardware momentum. EU driver-monitoring rules push automakers to install infrared cameras in every new cabin. In healthcare and corporate wellness, the Emotiv Epoc X 14-channel electroencephalography headset ships with pre-trained stress and engagement metrics, lowering the entry bar for non-specialist teams. The BIOPAC Research Ring fuses galvanic skin response, photoplethysmography, electrocardiogram, temperature, and accelerometer streams in a finger-worn form factor, giving researchers a multimodal option when privacy policies restrict video capture. Ongoing sensor miniaturization and rising production volume are set to bring hardware from labs to consumer wearables and ambient-intelligence ceilings.
Complete Report Scope:
- By Deployment
- On-Premise
- Cloud-based
- Edge/On-Device
- By Component
- Software (SDK/API)
- Hardware (Sensors/Camera)
- Services (Integration and Managed)
- By Analytics Modality
- Facial Emotion Recognition
- Video-based Multimodal
- Speech and Voice Tone
- Text and Sentiment
- Bio-signal (EEG/ECG/GSR) Multimodal
- By Application
- Customer Service and Contact Centers
- Product and Market Research
- Healthcare and Well-being
- Automotive and Transportation
- Education and E-Learning
- Gaming and Entertainment
- Security and Public Safety
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Rest of South America
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- South Korea
- ASEAN
- Rest of Asia-Pacific
- Middle East
- Saudi Arabia
- United Arab Emirates
- Rest of Middle East
- Africa
- South Africa
- Nigeria
- Rest of Africa
- North America
Geography Analysis
North America accounted for 36.64% of revenue in 2025, driven by early pilots, venture funding, and cloud credits from hyperscale providers. Asia-Pacific is projected to log an 11.61% CAGR through 2031, the steepest regional trajectory. China promotes emotion analytics within intelligent-vehicle programs and smart-city cameras, while Japan invests in eldercare robots that track affect to improve engagement. India's business-process-outsourcing hubs embed sentiment dashboards into quality-assurance workflows, and South Korean electronics firms integrate mood-sensing capabilities into smartphones and televisions.
Europe is growing more slowly because vendors must demonstrate compliance with both the General Data Protection Regulation (Article 9) and the forthcoming Artificial Intelligence Act. Suppliers that package federated-learning pipelines and homomorphic encryption gain procurement preference.
South America, the Middle East, and Africa report early pilots in retail, hospitality, and public safety, yet bandwidth and infrastructure gaps temper near-term contributions. Overall, the regional revenue mix is poised to diversify as the Asia-Pacific narrows the gap with North America over the forecast window.
- Affectiva Inc.
- Realeyes OU
- IBM Corporation
- Clarifai Inc.
- Sensum Ltd.
- Beyond Verbal Communication Ltd.
- Noldus Information Technology BV
- Sentiance NV
- Lexalytics Inc.
- Deloitte Touche Tohmatsu Ltd.
- Gorilla Technology Group Inc.
- Microsoft Corporation
- Google LLC
- Amazon Web Services Inc.
- Apple Inc.
- NEC Corporation
- Intel Corporation
- NVISO SA
- Sightcorp BV
- Kairos Inc.
- Entropik Technologies Pvt Ltd.
- iMotions A/S
- CrowdEmotion Ltd.
- Cogito Corporation
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Proliferation of IoT Wearables and Smart Devices
- 4.2.2 Advances in Deep-Learning-based Computer Vision and NLP
- 4.2.3 Demand for Hyper-personalised Customer Engagement Tools
- 4.2.4 Regulatory Mandate for Driver-monitoring Systems (EU GSR 2024)
- 4.2.5 Emergence of Empathetic AI in Tele-mental-health Platforms
- 4.2.6 Edge-compute Frameworks for Privacy-preserving Analytics
- 4.3 Market Restraints
- 4.3.1 Stringent Data-privacy Regulations (GDPR, CPRA, etc.)
- 4.3.2 Bias and Accuracy Issues in Facial-emotion Data Sets
- 4.3.3 High Latency/Bandwidth Cost in Real-time Video Analytics
- 4.3.4 Ethical Backlash Against Emotion Surveillance in Schools
- 4.4 Industry Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Deployment
- 5.1.1 On-Premise
- 5.1.2 Cloud-based
- 5.1.3 Edge/On-Device
- 5.2 By Component
- 5.2.1 Software (SDK/API)
- 5.2.2 Hardware (Sensors/Camera)
- 5.2.3 Services (Integration and Managed)
- 5.3 By Analytics Modality
- 5.3.1 Facial Emotion Recognition
- 5.3.2 Video-based Multimodal
- 5.3.3 Speech and Voice Tone
- 5.3.4 Text and Sentiment
- 5.3.5 Bio-signal (EEG/ECG/GSR) Multimodal
- 5.4 By Application
- 5.4.1 Customer Service and Contact Centers
- 5.4.2 Product and Market Research
- 5.4.3 Healthcare and Well-being
- 5.4.4 Automotive and Transportation
- 5.4.5 Education and E-Learning
- 5.4.6 Gaming and Entertainment
- 5.4.7 Security and Public Safety
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 South America
- 5.5.2.1 Brazil
- 5.5.2.2 Argentina
- 5.5.2.3 Rest of South America
- 5.5.3 Europe
- 5.5.3.1 Germany
- 5.5.3.2 United Kingdom
- 5.5.3.3 France
- 5.5.3.4 Italy
- 5.5.3.5 Spain
- 5.5.3.6 Rest of Europe
- 5.5.4 Asia-Pacific
- 5.5.4.1 China
- 5.5.4.2 Japan
- 5.5.4.3 India
- 5.5.4.4 South Korea
- 5.5.4.5 ASEAN
- 5.5.4.6 Rest of Asia-Pacific
- 5.5.5 Middle East
- 5.5.5.1 Saudi Arabia
- 5.5.5.2 United Arab Emirates
- 5.5.5.3 Rest of Middle East
- 5.5.6 Africa
- 5.5.6.1 South Africa
- 5.5.6.2 Nigeria
- 5.5.6.3 Rest of Africa
- 5.5.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market Level Overview, Core Segments, Financials as Available, Strategic Information, Market Rank/Share for Key Companies, Products and Services, and Recent Developments)
- 6.4.1 Affectiva Inc.
- 6.4.2 Realeyes OU
- 6.4.3 IBM Corporation
- 6.4.4 Clarifai Inc.
- 6.4.5 Sensum Ltd.
- 6.4.6 Beyond Verbal Communication Ltd.
- 6.4.7 Noldus Information Technology BV
- 6.4.8 Sentiance NV
- 6.4.9 Lexalytics Inc.
- 6.4.10 Deloitte Touche Tohmatsu Ltd.
- 6.4.11 Gorilla Technology Group Inc.
- 6.4.12 Microsoft Corporation
- 6.4.13 Google LLC
- 6.4.14 Amazon Web Services Inc.
- 6.4.15 Apple Inc.
- 6.4.16 NEC Corporation
- 6.4.17 Intel Corporation
- 6.4.18 NVISO SA
- 6.4.19 Sightcorp BV
- 6.4.20 Kairos Inc.
- 6.4.21 Entropik Technologies Pvt Ltd.
- 6.4.22 iMotions A/S
- 6.4.23 CrowdEmotion Ltd.
- 6.4.24 Cogito Corporation
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-Need Assessment

