PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2124164

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2124164
RF Front End Module - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
According to Mordor Intelligence, the RF front-end module market size is expected to grow from USD 29.25 billion in 2025 to USD 33.06 billion in 2026 and is forecast to reach USD 60.99 billion by 2031 at 13.02% CAGR over 2026-2031.
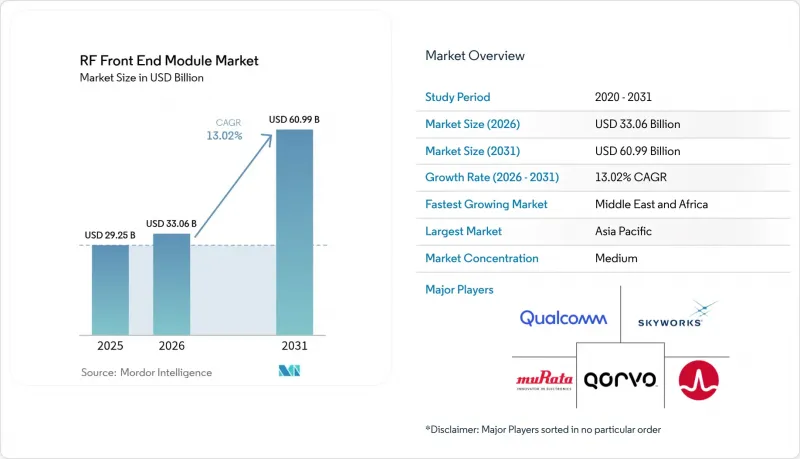
This report is Segmented by Component (Power Amplifiers, Duplexers and Diplexers, Filters, Switches, Low-Noise Amplifiers, and Antenna Tuners), Application (Consumer Electronics, Automotive, Wireless Communication, Industrial, Aerospace and Defense, and Other Applications), Frequency Range (Sub-6 GHz, and More), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global RF Front End Module Market Trends and Insights
Explosive 5G Design-Wins in Sub-6 GHz Smartphones
Carrier rollouts prioritize blanket coverage, making sub-6 GHz the volume engine for the RF front end module market. Samsung's adoption of the SKY5 platform trimmed board area by 30% while boosting battery endurance. Device makers now rate RF performance alongside camera quality when defining premium tiers. Tight footprints, multi-band carrier aggregation, and stricter SAR limits favor consolidated FEMs over discrete chains. Suppliers with algorithm-assisted envelope tracking add power efficiency, a point that resonates with sustainability targets. The result is a virtuous cycle in which every design win feeds production scale that, in turn, lowers per-unit cost.
Rapid mmWave Adoption in Fixed-Wireless Access (FWA) CPE
Verizon's service footprint grew to 40 million homes in 2024, confirming the economic logic of mmWave FWA. CPE devices accept bigger antennas, so each install embeds four to eight mmWave RF chains-up to 4X the smartphone content. Higher bill-of-materials value per node lifts the RF front end module market even with moderate unit volumes. Policy makers allocate spectrum preferentially to fixed services, reducing interference risk and facilitating beam-steering antennas that remain stationary. Suppliers that master thermal dissipation in outdoor units secure sizable margins, because mmWave PAs still command premium ASPs.
Looming IP Shortages for BAW Filter Patents
Foundational BAW patents near expiry, yet follow-on innovations have plateaued. Few suppliers hold the residual know-how for GHz-range Q-factor leadership, so licensing fees climb. OEMs trying to add new bands must either pay premiums or switch to TC-SAW, which can underperform in high-temperature use. Patent cliffs motivate defensive litigation that diverts R&D funds. Smaller entrants face high barriers, concentrating bargaining power with incumbents and slowing price erosion in the filter slice of the RF front end module market.
Other drivers and restraints analyzed in the detailed report include:
- OEM Push for Integrated Modem-to-Antenna Platforms
- GaAs Wafer Capacity Expansion in Taiwan and China
- Tight Gallium Supply Chain Amid Export Restrictions
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Filters controlled a 33.78% share of the RF front-end module market in 2025 and remain indispensable for band proliferation. Antenna tuners, however, post a category-leading 13.98% CAGR as impedance-matching across a fragmented spectrum turns into a design must-have. The RF front-end module market size for hybrid FEMs is projected to climb steadily because integrating switches, LNAs, and duplexers lowers insertion loss and simplifies thermal layout. Power amplifiers face ASP compression as OEMs bundle them with controllers, though GaN processes preserve margin in high-power niches. Switches enjoy steady pull from carrier aggregation, especially as 3-CC downlink becomes mainstream in mid-band devices.
Low-noise amplifiers ride coverage-extension campaigns in rural zones, where receiver sensitivity outweighs peak data rate. Discrete duplexers stay relevant for legacy LTE bands, but next-gen time-division duplex lowers their attach rate in select 5G frequencies. Qorvo's 2024 FEM line shaved 40% PCB footprint versus prior discrete builds, highlighting how form-factor wins can substitute for raw component performance. As a result, component vendors recalibrate roadmaps to favor highly integrated SIPs, aligning with OEM procurement strategies that reward module-level cost per function.
Complete Report Scope:
- By Component
- Power Amplifiers (PA)
- Duplexers and Diplexers
- Filters (SAW, BAW, TC-SAW)
- Switches
- Low-Noise Amplifiers (LNA)
- Antenna Tuners
- Integrated/Hybrid FEMs
- By Application
- Consumer Electronics (Smartphones, Wearables)
- Automotive (ADAS, V2X Communication)
- Wireless Communication (5G, Wi-Fi 6/6E)
- Industrial
- Aerospace and Defense
- Others Applications
- By Frequency Range
- Sub-6 GHz (FR1)
- mmWave (24-47 GHz, FR2)
- More than 47 GHz (6G R&D bands)
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Chile
- Rest of South America
- Europe
- United Kingdom
- Germany
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- South Korea
- Australia
- Singapore
- Malaysia
- Rest of Asia-Pacific
- Middle East and Africa
- Middle East
- Saudi Arabia
- United Arab Emirates
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Nigeria
- Rest of Africa
- Middle East
- North America
Geography Analysis
Asia-Pacific maintained 56.88% share of the RF front end module market in 2025, powered by China's handset output and South Korea's dense 5G builds. Integrated supply chains encompass raw gallium refining, wafer fabrication, and module assembly, yielding cost and cycle-time advantages few regions can match. Japan's USD 10 trillion semiconductor program strengthens local ecosystem resilience and funds compound semiconductor pilot lines.
North America leverages defense budgets and early 5G adoption to sustain high-performance design leadership. MACOM's USD 345 million GaN expansion joins multiple advanced-packaging initiatives aimed at closing the manufacturing gap with Asia. However, component imports still dominate the volume of consumer devices, exposing OEMs to cross-border logistics risk.
Middle East and Africa posts a 13.95% CAGR as operators bypass 4G and leapfrog to standalone 5G. Government digital-economy strategies fund towers and spectrum, but device affordability dictates a sub-6 GHz focus. Europe enjoys demand from the automotive and Industry 4.0, where GDPR and supply-chain sovereignty push brands to source locally. South America and emerging ASEAN markets absorb technology transfer as suppliers chase untapped subscriber growth.
- Skyworks Solutions, Inc.
- Qorvo, Inc.
- Murata Manufacturing Co., Ltd.
- Qualcomm Technologies, Inc.
- Broadcom Inc.
- NXP Semiconductors N.V.
- Infineon Technologies AG
- Taiyo Yuden Co., Ltd.
- TDK Corporation
- Skyworks Aerolab Pte. Ltd.
- Wisol Co., Ltd.
- Akoustis Technologies, Inc.
- Resonant Inc.
- pSemi Corporation
- Maxscend Microelectronics Co., Ltd.
- Unisoc (Shanghai) Technologies Co., Ltd.
- Jiangsu Hengxin Technology Co., Ltd.
- Kyocera Corporation
- RFHIC Corporation
- MACOM Technology Solutions Holdings, Inc.
- WIN Semiconductors Corp.
- Silterra Malaysia Sdn. Bhd.
- Optimum Semiconductor Technologies Inc.
- Finwave Semiconductor, Inc.
- UMC RF Solution Business Unit
- Tower Semiconductor Ltd.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Explosive 5G design-wins in sub-6 GHz smartphones
- 4.2.2 Rapid mmWave adoption in fixed wireless access (FWA) CPE
- 4.2.3 OEM push for integrated modem-to-antenna platforms
- 4.2.4 GaAs wafer capacity expansion in Taiwan and China
- 4.2.5 Defense demand for GaN-based AESA radar modules
- 4.2.6 "Right-to-Repair" laws extending handset lifecycles (under-radar)
- 4.3 Market Restraints
- 4.3.1 Looming IP shortages for BAW filter patents
- 4.3.2 Talent gap in mmWave packaging engineers (under-radar)
- 4.3.3 Tight gallium supply chain amid export restrictions
- 4.3.4 On-device AI reducing RF Tx duty-cycle (under-radar)
- 4.4 Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Suppliers
- 4.7.3 Bargaining Power of Buyers
- 4.7.4 Threat of Substitutes
- 4.7.5 Industry Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Component
- 5.1.1 Power Amplifiers (PA)
- 5.1.2 Duplexers and Diplexers
- 5.1.3 Filters (SAW, BAW, TC-SAW)
- 5.1.4 Switches
- 5.1.5 Low-Noise Amplifiers (LNA)
- 5.1.6 Antenna Tuners
- 5.1.7 Integrated/Hybrid FEMs
- 5.2 By Application
- 5.2.1 Consumer Electronics (Smartphones, Wearables)
- 5.2.2 Automotive (ADAS, V2X Communication)
- 5.2.3 Wireless Communication (5G, Wi-Fi 6/6E)
- 5.2.4 Industrial
- 5.2.5 Aerospace and Defense
- 5.2.6 Others Applications
- 5.3 By Frequency Range
- 5.3.1 Sub-6 GHz (FR1)
- 5.3.2 mmWave (24-47 GHz, FR2)
- 5.3.3 More than 47 GHz (6G R&D bands)
- 5.4 By Geography
- 5.4.1 North America
- 5.4.1.1 United States
- 5.4.1.2 Canada
- 5.4.1.3 Mexico
- 5.4.2 South America
- 5.4.2.1 Brazil
- 5.4.2.2 Argentina
- 5.4.2.3 Chile
- 5.4.2.4 Rest of South America
- 5.4.3 Europe
- 5.4.3.1 United Kingdom
- 5.4.3.2 Germany
- 5.4.3.3 France
- 5.4.3.4 Italy
- 5.4.3.5 Spain
- 5.4.3.6 Rest of Europe
- 5.4.4 Asia-Pacific
- 5.4.4.1 China
- 5.4.4.2 Japan
- 5.4.4.3 India
- 5.4.4.4 South Korea
- 5.4.4.5 Australia
- 5.4.4.6 Singapore
- 5.4.4.7 Malaysia
- 5.4.4.8 Rest of Asia-Pacific
- 5.4.5 Middle East and Africa
- 5.4.5.1 Middle East
- 5.4.5.1.1 Saudi Arabia
- 5.4.5.1.2 United Arab Emirates
- 5.4.5.1.3 Turkey
- 5.4.5.1.4 Rest of Middle East
- 5.4.5.2 Africa
- 5.4.5.2.1 South Africa
- 5.4.5.2.2 Nigeria
- 5.4.5.2.3 Rest of Africa
- 5.4.5.1 Middle East
- 5.4.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 Skyworks Solutions, Inc.
- 6.4.2 Qorvo, Inc.
- 6.4.3 Murata Manufacturing Co., Ltd.
- 6.4.4 Qualcomm Technologies, Inc.
- 6.4.5 Broadcom Inc.
- 6.4.6 NXP Semiconductors N.V.
- 6.4.7 Infineon Technologies AG
- 6.4.8 Taiyo Yuden Co., Ltd.
- 6.4.9 TDK Corporation
- 6.4.10 Skyworks Aerolab Pte. Ltd.
- 6.4.11 Wisol Co., Ltd.
- 6.4.12 Akoustis Technologies, Inc.
- 6.4.13 Resonant Inc.
- 6.4.14 pSemi Corporation
- 6.4.15 Maxscend Microelectronics Co., Ltd.
- 6.4.16 Unisoc (Shanghai) Technologies Co., Ltd.
- 6.4.17 Jiangsu Hengxin Technology Co., Ltd.
- 6.4.18 Kyocera Corporation
- 6.4.19 RFHIC Corporation
- 6.4.20 MACOM Technology Solutions Holdings, Inc.
- 6.4.21 WIN Semiconductors Corp.
- 6.4.22 Silterra Malaysia Sdn. Bhd.
- 6.4.23 Optimum Semiconductor Technologies Inc.
- 6.4.24 Finwave Semiconductor, Inc.
- 6.4.25 UMC RF Solution Business Unit
- 6.4.26 Tower Semiconductor Ltd.
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-need Assessment

