PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2124975

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2124975
Semiconductor Front End Equipment - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
According to Mordor Intelligence, the semiconductor front-end equipment market size was valued at USD 107.95 billion in 2025 and estimated to grow from USD 115.86 billion in 2026 to reach USD 163.99 billion by 2031, at a CAGR of 7.2% during the forecast period (2026-2031).
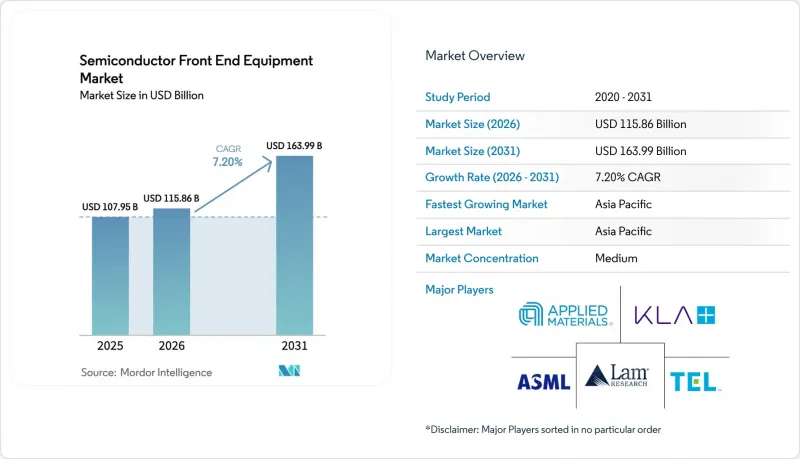
This report is Segmented by Equipment Type (Lithography, Etch, Deposition and Thin-Film, and More), End-User Industry (Foundry and Logic, IDM, Memory DRAM and NAND, and Specialty Analog and Power), Wafer Size (300mm, 200mm, and 150mm and <=100mm), Process Node Technology (<=5nm, 6-16nm, 28-65nm, and >65nm Mature), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global Semiconductor Front End Equipment Market Trends and Insights
AI-Accelerated Node Migration To Below 3 nm
Foundries are significantly accelerating their node-transition cycles, introducing nanosheet processes into production years ahead of their previously established roadmaps. This rapid advancement is evident in TSMC's N2 ramp, Intel's 18A line, and Samsung's 2 nm gate-all-around flow, all of which require approximately 30% more etch and deposition steps compared to their FinFET predecessors. These additional steps have led to a notable increase in the tool count per production line. Furthermore, only ASML has the capability to supply the essential EUV scanners required for these advanced layers. However, ASML's production capacity is limited, with a 2026 ceiling of approximately 90 units, which imposes significant constraints on fab start-ups and their ability to scale operations effectively.
HBM-Driven TSV And Deep-Silicon Etch Intensity Spike
Memory producers have significantly increased their orders for deep-reactive-ion etchers and copper-fill deposition tools, driven by the advancements in HBM3E packages, which now stack up to 12 dies. This stacking capability translates into tens of thousands of high-aspect-ratio vias per wafer, necessitating the use of advanced manufacturing tools. Both Lam Research's Flex platform and Applied Materials' Sym3 Y chamber have reported substantial double-digit order growth within this segment, highlighting the growing demand for these technologies in the memory production market.
Precision Optics Supply Bottlenecks Inflating Lead-Times
All EUV mirror sets globally are manufactured exclusively by Carl Zeiss SMT. The company's production facility in Oberkochen has the capacity to produce 40 assemblies annually for standard EUV systems and approximately 10 assemblies per year for High-NA tools. This limited production capacity results in scanner lead times that can extend up to 30 months, creating significant bottlenecks in the supply chain. Furthermore, any disruption in the production process could severely impact timelines, delaying the ramp-up of sub-2 nm technology by as much as 18 months. Recognizing these risks, ASML is actively pursuing dual sourcing strategies by collaborating with Japanese optics firms to ensure a more robust and reliable supply chain.
Other drivers and restraints analyzed in the detailed report include:
- Massive State-Backed Fab Build-Out In China
- High-NA EUV Roll-Out Spawning Actinic Metrology Demand
- Tightening Export Controls On Advanced Lithography
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
In 2025, lithography tools accounted for 28.94% of the revenue, buoyed by assertive foundry and memory strategies. These tools play a critical role in the semiconductor manufacturing process, enabling precise patterning required for advanced chip designs. High-NA EUV platforms, each carrying a price tag close to USD 380 million, are set to expand at an 11.72% CAGR, propelling the semiconductor front-end equipment market tied to patterning technologies. The increasing demand for these platforms highlights their importance in meeting the growing complexity of semiconductor devices. Following closely, etch systems claimed a 22% share, driven by the rising prominence of gate-all-around structures and enhanced plasma steps for backside power delivery. These systems are essential for achieving the intricate designs required in modern chips. Deposition tools held a 19% stake, underscoring the growing adoption of ALD for high-k dielectrics. The wider use of ALD reflects the industry's shift towards materials and processes that enhance device performance and efficiency. Meanwhile, inspection and metrology climbed to a 12% share, even as overlay budgets tightened. This growth indicates the increasing need for precise quality control and measurement in semiconductor manufacturing.
Legacy categories, including ion implantation, CMP, cleaning, track-coat developers, and thermal processing, accounted for the remaining 18% of expenditures. These categories, while mature, remain vital to the overall semiconductor manufacturing ecosystem. Vendors entrenched in these established domains grapple with ASP pressures from swiftly advancing Chinese rivals, who can slash prices by as much as 25%. The competitive pricing from Chinese competitors poses significant challenges for multinational suppliers. As a result, global suppliers are redirecting R&D investments towards more lucrative offerings like EUV, TSV, and actinic inspection. This strategic shift aims to capitalize on higher-margin opportunities and maintain a competitive edge in the evolving semiconductor market.
In 2025, TSMC, Samsung Foundry, and Intel spearheaded the foundry and logic houses, accounting for 46.21% of the total expenditure. These companies have consistently led the market due to their advanced manufacturing capabilities and significant investments in cutting-edge technologies. Meanwhile, the memory segment, dominated by SK Hynix, Samsung, and Micron, is poised for the swiftest growth at a 10.40% CAGR, buoyed by HBM capacity expansions. This rapid growth in the memory sector is not only driving advancements in technology but also bolstering the market share of TSV etch, copper fill, and wafer-bonding tools in the semiconductor front-end equipment arena. These tools are critical for enabling the production of high-performance memory solutions.
Texas Instruments and Infineon, pivoting their lines for automotive analog and power chips, propelled integrated device manufacturers to capture 18% of the expenditures. This shift highlights the growing importance of automotive applications in the semiconductor industry, particularly as vehicles become increasingly reliant on advanced electronic systems. Meanwhile, a surge in demand for electric-vehicle inverters bolstered specialty analog and power customers, who claimed the remaining 12%. This demand underscores the expanding role of electric vehicles in shaping the semiconductor market. The ongoing divergence in equipment focus, prioritizing leading-edge lithography for logic and TSV and deposition for memory, continues to influence supplier strategies. Suppliers are adapting their roadmaps to address these distinct priorities, ensuring they remain competitive in a rapidly evolving market landscape.
Complete Report Scope:
- By Equipment Type
- Lithography Equipment
- Etch Equipment
- Deposition and Thin-Film Equipment
- Ion Implantation Equipment
- CMP Equipment
- Cleaning Equipment
- Inspection and Metrology
- Track, Coater and Developer
- Thermal Processing
- By End-User Industry
- Foundry and Logic
- IDM, Integrated Device Manufacturer
- Memory, DRAM and NAND
- Specialty Analog and Power
- By Wafer Size
- 300 mm
- 200 mm
- 150 mm and = 100 mm
- By Process Node Technology
- = 5 nm
- 6-16 nm
- 28-65 nm
- > 65 nm (Mature)
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Rest of South America
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- New Zealand
- Rest of Asia-Pacific
- Middle East and Africa
- Middle East
- United Arab Emirates
- Saudi Arabia
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Nigeria
- Kenya
- Rest of Africa
- Middle East
- North America
Geography Analysis
In 2025, the Asia-Pacific region maintained its dominance with a substantial 55.17% market share, primarily driven by Taiwan's advanced semiconductor hubs, South Korea's significant memory expansions, and India's proactive establishment of subsidy-supported fabs. Taiwan alone accounted for approximately 25% of the global demand for semiconductor tools, with its N2, N2P, and A16 production lines making substantial investments in EUV lithography and actinic metrology technologies. Meanwhile, South Korea's capital expenditures were heavily focused on advancing HBM and 2 nm processes, channeling significant orders toward TSV, dielectric etch, and copper fill technologies to enhance production capabilities.
North America followed as the second-largest contributor, securing a 22% revenue share in the global market. The region's growth was significantly influenced by major projects such as Intel's developments in Ohio, Arizona, and Oregon, Texas Instruments' establishment of 300 mm analog production lines, and GlobalFoundries' expansion efforts in Malta. These initiatives have collectively reshaped the regional supply chain, prompting equipment vendors to respond by setting up local manufacturing modules and service hubs. This strategic move aims to capitalize on the incentives provided under the CHIPS Act, further strengthening the region's position in the global semiconductor market.
Europe held an approximate 12% market share, with its focus centered on specialty analogs, power semiconductor sectors, and pioneering research initiatives for High-NA EUV technologies. Companies like STMicroelectronics and Infineon emphasized the development of cost-efficient mature nodes to remain competitive, while collaborations between imec and ASML advanced next-generation actinic metrology solutions. Although South America, the Middle East, and Africa remained minor contributors to the global market, initiatives backed by Saudi Arabia indicate potential long-term growth. However, realizing this growth will depend on addressing critical ecosystem challenges, including the development of skilled labor, access to water resources, and the availability of reliable utilities.
- Applied Materials Inc.
- KLA Corporation
- ASML Holding N.V.
- Lam Research Corporation
- Tokyo Electron Limited
- Nikon Corporation
- Canon Inc.
- SCREEN Holdings Co., Ltd.
- ASM International N.V.
- Advantest Corporation
- Disco Corporation
- Lasertec Corporation
- Axcelis Technologies Inc.
- Onto Innovation Inc.
- Veeco Instruments Inc.
- AMETEK Inc.
- Plasma-Therm LLC
- NAURA Technology Group Co., Ltd.
- Advanced Micro-Fab Equipment (AMEC) Inc.
- Shanghai Micro Electronics Equipment (SMEE) Co., Ltd.
- Ebara Corporation
- TEL Semes Co., Ltd.
- ULVAC Inc.
- ACCRETECH Inc. (Tokyo Seimitsu)
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 AI-Accelerated Node Migration to Below 3 nm
- 4.2.2 Massive State-Backed Fab Build-Out in China
- 4.2.3 5G and IoT Device Rebound Lifting Mature-Node Demand
- 4.2.4 HBM-Driven TSV and Deep-Silicon Etch Intensity Spike
- 4.2.5 High-NA EUV Roll-Out Spawning Actinic Metrology Demand
- 4.2.6 India's Greenfield 300 mm Fabs (CHIPS-Linked) 2026-29
- 4.3 Market Restraints
- 4.3.1 Precision Optics Supply Bottlenecks Inflating Lead-Times
- 4.3.2 Tightening Export Controls on Advanced Lithography
- 4.3.3 Back-Side Power-Delivery Defect Hurdles Delaying Tools
- 4.3.4 Net-Zero Fab Mandates Raising Wet-Bench TCO
- 4.4 Industry Value-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Bargaining Power of Buyers
- 4.7.2 Bargaining Power of Suppliers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Equipment Type
- 5.1.1 Lithography Equipment
- 5.1.2 Etch Equipment
- 5.1.3 Deposition and Thin-Film Equipment
- 5.1.4 Ion Implantation Equipment
- 5.1.5 CMP Equipment
- 5.1.6 Cleaning Equipment
- 5.1.7 Inspection and Metrology
- 5.1.8 Track, Coater and Developer
- 5.1.9 Thermal Processing
- 5.2 By End-User Industry
- 5.2.1 Foundry and Logic
- 5.2.2 IDM, Integrated Device Manufacturer
- 5.2.3 Memory, DRAM and NAND
- 5.2.4 Specialty Analog and Power
- 5.3 By Wafer Size
- 5.3.1 300 mm
- 5.3.2 200 mm
- 5.3.3 150 mm and = 100 mm
- 5.4 By Process Node Technology
- 5.4.1 = 5 nm
- 5.4.2 6-16 nm
- 5.4.3 28-65 nm
- 5.4.4 > 65 nm (Mature)
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 South America
- 5.5.2.1 Brazil
- 5.5.2.2 Argentina
- 5.5.2.3 Rest of South America
- 5.5.3 Europe
- 5.5.3.1 Germany
- 5.5.3.2 United Kingdom
- 5.5.3.3 France
- 5.5.3.4 Italy
- 5.5.3.5 Spain
- 5.5.3.6 Rest of Europe
- 5.5.4 Asia Pacific
- 5.5.4.1 China
- 5.5.4.2 Japan
- 5.5.4.3 South Korea
- 5.5.4.4 India
- 5.5.4.5 Australia
- 5.5.4.6 New Zealand
- 5.5.4.7 Rest of Asia-Pacific
- 5.5.5 Middle East and Africa
- 5.5.5.1 Middle East
- 5.5.5.1.1 United Arab Emirates
- 5.5.5.1.2 Saudi Arabia
- 5.5.5.1.3 Turkey
- 5.5.5.1.4 Rest of Middle East
- 5.5.5.2 Africa
- 5.5.5.2.1 South Africa
- 5.5.5.2.2 Nigeria
- 5.5.5.2.3 Kenya
- 5.5.5.2.4 Rest of Africa
- 5.5.5.1 Middle East
- 5.5.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)
- 6.4.1 Applied Materials Inc.
- 6.4.2 KLA Corporation
- 6.4.3 ASML Holding N.V.
- 6.4.4 Lam Research Corporation
- 6.4.5 Tokyo Electron Limited
- 6.4.6 Nikon Corporation
- 6.4.7 Canon Inc.
- 6.4.8 SCREEN Holdings Co., Ltd.
- 6.4.9 ASM International N.V.
- 6.4.10 Advantest Corporation
- 6.4.11 Disco Corporation
- 6.4.12 Lasertec Corporation
- 6.4.13 Axcelis Technologies Inc.
- 6.4.14 Onto Innovation Inc.
- 6.4.15 Veeco Instruments Inc.
- 6.4.16 AMETEK Inc.
- 6.4.17 Plasma-Therm LLC
- 6.4.18 NAURA Technology Group Co., Ltd.
- 6.4.19 Advanced Micro-Fab Equipment (AMEC) Inc.
- 6.4.20 Shanghai Micro Electronics Equipment (SMEE) Co., Ltd.
- 6.4.21 Ebara Corporation
- 6.4.22 TEL Semes Co., Ltd.
- 6.4.23 ULVAC Inc.
- 6.4.24 ACCRETECH Inc. (Tokyo Seimitsu)
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment

