PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2124423

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2124423
Middle-East And Africa Wood Coatings - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
According to Mordor Intelligence, the Middle East and Africa wood coatings market size is expected to grow from USD 404.53 million in 2025 to USD 416.09 million in 2026 and is forecast to reach USD 479.22 million by 2031 at 2.86% CAGR over 2026-2031.
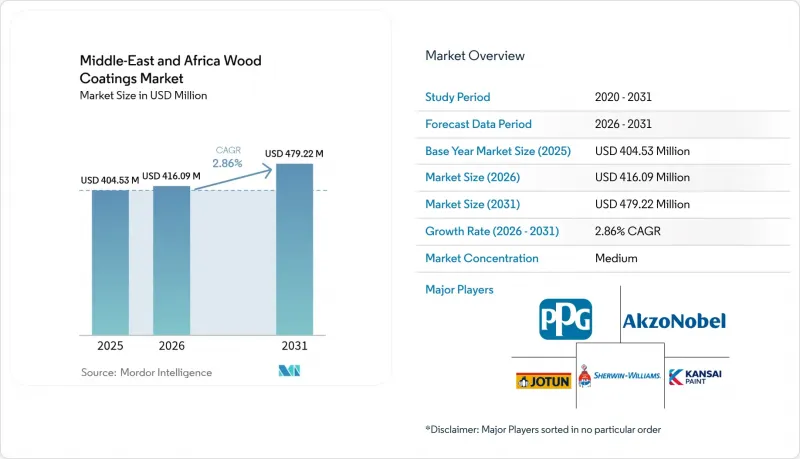
This report is Segmented by Resin Type (Polyurethane, Polyester, Nitrocellulose, and More), Technology (Water-Borne, Solvent-Borne, UV Cured, and Powder), Application (Furniture and Fixtures, Doors and Windows, and More), and Geography (South Africa, Egypt, Morocco, Nigeria, Algeria, Kenya, Saudi Arabia, UAE, and More). Market Forecasts are Provided in Terms of Value (USD).
Middle-East And Africa Wood Coatings Market Trends and Insights
Surge in GCC and East Africa Construction Pipeline
Public capital outlays are reshaping demand across building types. Saudi Arabia's Public Investment Fund has directed USD 40 billion to projects that prioritize wood-intensive hospitality interiors, driving the specification of marine-grade polyurethane that withstands 90% humidity. Kenya's affordable-housing program, which stipulates the use of locally sourced timber for the joinery, boosted interior-wood demand. Ethiopian customs tariffs discourage waterborne primer imports, so solvent lines remain dominant despite Addis Ababa's real estate boom. Formulators therefore operate dual production lines to serve both high-performance Gulf projects and cost-sensitive East African housing.
Expansion of Regional Furniture Manufacturing Hubs
Morocco exported USD 358 million in furniture during 2024, led by Casablanca and Tangier plants that have adopted two-component polyurethane to meet European scratch-resistance standards. Kenya's furniture sector, valued at USD 452 million, continues to struggle with a shortage of kiln-dried timber; reject rates for UV-cured finishes remain high, reinforcing nitrocellulose's dominance. South Africa's Western Cape manufacturers pivoted to engineered wood, reducing solvent emissions by 35% in line with provincial air-quality plans. Export-oriented hubs demand consistent, compliant coatings, whereas small workshops in Kenya and South Africa often prioritize price over performance.
Stringent VOC / REACH-Like Regulations
Egypt's 250 g/L cap disqualified many nitrocellulose lines, forcing import of water-borne alternatives at 15-20% higher cost. Morocco now requires VOC declarations for exports to Europe, adding testing overhead that small workshops struggle to absorb. South African authorities issued 14 compliance notices in 2024; non-compliant plants faced shutdown threats. GCC projects increasingly request LEED-aligned low-VOC coatings, pushing water-borne penetration from 30% in 2022 to 48% in 2024. Capital costs for spray-line retrofits remain a hurdle, so many Kenyan and Nigerian shops keep solvent products despite lower margins.
Other drivers and restraints analyzed in the detailed report include:
- Regulatory Shift Toward Water-Borne Systems
- Tourism Mega-Projects Demanding Premium Wood Finishes
- Petro-Resin Price Volatility
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Polyurethane captured 59.10% of the Middle-East and Africa wood coatings market share in 2025 and is rising at a 2.94% CAGR through 2031. Contractors in Jeddah, Doha, and Dubai routinely specify two-component PU for exterior joinery where 90% humidity threatens delamination. Polyester, which holds around 10.20%, remains popular in dry, inland Saudi regions, but exhibits brittleness under thermal cycling. Nitrocellulose fell to 10% because Egypt's VOC cap forced exporters to drop legacy formulas. Water-borne polyurethane dispersions, marketed under the Bayhydur and Laromer brands, experienced double-digit growth in North Africa after distributors highlighted their EU compliance. UV-cured acrylics are expanding fast thanks to digital printing at Turkish and Egyptian MDF plants.
Polyurethane's premium tier coexists with a value tier of single-component acrylics and residual nitrocellulose, which dominate the East African domestic furniture market. The bifurcation pressures vendors to run parallel supply chains. Over the forecast horizon, polyurethane's share may inch higher as Gulf tourism projects multiply, while nitrocellulose continues to retreat in export-oriented clusters.
Complete Report Scope:
- By Resin Type
- Polyurethane
- Polyester
- Nitrocellulose
- Acrylics
- Others
- By Technology
- Water-borne
- Solvent-borne
- UV cured
- Powder
- By Application
- Furniture and Fixtures
- Doors and Windows
- Cabinets
- Others
- By Geography
- South Africa
- Egypt
- Morocco
- Nigeria
- Algeria
- Kenya
- Saudi Arabia
- United Arab Emirates
- Iran
- Rest of Middle East and Africa
List of Companies Covered in this Report:
- Akzo Nobel N.V.
- Asian Paints Ltd.
- Caparol Paints (DAW SE)
- Crown Paints Kenya PLC
- Hempel A/S
- IVM Chemicals SRL
- Jotun
- Kansai Paint Co., Ltd.
- KAPCI Coatings
- Mas Paints
- National Paints Factories Co. Ltd.
- Nippon Paint Holdings Co., Ltd.
- PPG Industries Inc.
- Ritver
- RPM International Inc.
- Sipes Egypt
- The Sherwin-Williams Company
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Surge in GCC and East-Africa construction pipeline
- 4.2.2 Expansion of regional furniture manufacturing hubs
- 4.2.3 Regulatory shift toward water-borne systems
- 4.2.4 Tourism mega-projects demanding premium wood finishes
- 4.2.5 Rise of digital-printing on engineered wood
- 4.3 Market Restraints
- 4.3.1 Stringent VOC / REACH-like regulations
- 4.3.2 Petro-resin price volatility
- 4.3.3 Shortage of kiln-dried timber supply
- 4.4 Value Chain Analysis
- 4.5 Porter's Five Forces
- 4.5.1 Bargaining Power of Suppliers
- 4.5.2 Bargaining Power of Consumers
- 4.5.3 Threat of New Entrants
- 4.5.4 Threat of Substitutes
- 4.5.5 Degree of Competition
5 Market Size and Growth Forecasts (Value)
- 5.1 By Resin Type
- 5.1.1 Polyurethane
- 5.1.2 Polyester
- 5.1.3 Nitrocellulose
- 5.1.4 Acrylics
- 5.1.5 Others
- 5.2 By Technology
- 5.2.1 Water-borne
- 5.2.2 Solvent-borne
- 5.2.3 UV cured
- 5.2.4 Powder
- 5.3 By Application
- 5.3.1 Furniture and Fixtures
- 5.3.2 Doors and Windows
- 5.3.3 Cabinets
- 5.3.4 Others
- 5.4 By Geography
- 5.4.1 South Africa
- 5.4.2 Egypt
- 5.4.3 Morocco
- 5.4.4 Nigeria
- 5.4.5 Algeria
- 5.4.6 Kenya
- 5.4.7 Saudi Arabia
- 5.4.8 United Arab Emirates
- 5.4.9 Iran
- 5.4.10 Rest of Middle East and Africa
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share(%)/Ranking Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 Akzo Nobel N.V.
- 6.4.2 Asian Paints Ltd.
- 6.4.3 Caparol Paints (DAW SE)
- 6.4.4 Crown Paints Kenya PLC
- 6.4.5 Hempel A/S
- 6.4.6 IVM Chemicals SRL
- 6.4.7 Jotun
- 6.4.8 Kansai Paint Co., Ltd.
- 6.4.9 KAPCI Coatings
- 6.4.10 Mas Paints
- 6.4.11 National Paints Factories Co. Ltd.
- 6.4.12 Nippon Paint Holdings Co., Ltd.
- 6.4.13 PPG Industries Inc.
- 6.4.14 Ritver
- 6.4.15 RPM International Inc.
- 6.4.16 Sipes Egypt
- 6.4.17 The Sherwin-Williams Company
7 Market Opportunities and Future Outlook
- 7.1 White-space and Unmet-need Assessment

