PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2124432

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2124432
Tire Cord Fabrics - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
According to Mordor Intelligence, the tire cord fabrics market size was valued at 1.56 kilotons in 2025 and estimated to grow from 1.6 kilotons in 2026 to reach 1.85 kilotons by 2031, at a CAGR of 2.88% during the forecast period (2026-2031).
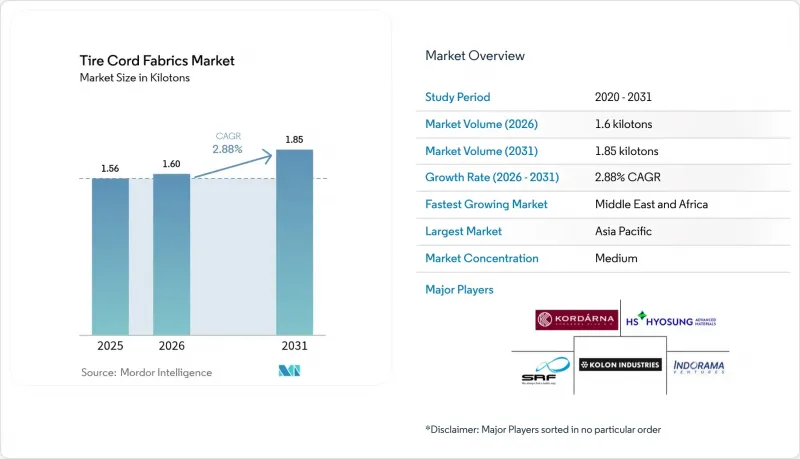
This report is Segmented by Fiber (Nylon, Polyester, Rayon, Aramid, Glass, and PVA), Tire Type (Bias/Diagonal, Semi-Radial, and Radial), Vehicle Type (Automotive, Aircrafts, Industrial Products, and Others), and Geography (Asia-Pacific, North America, Europe, South America, and Middle-East and Africa). The Market Forecasts are Provided in Terms of Volume (Tons).
Global Tire Cord Fabrics Market Trends and Insights
Rising Global Vehicle Production and Parc Expansion
Industry-wide vehicle output recovery is driving bulk orders for reinforcement textiles as tire factories rebuild inventories that ran down during recent supply-chain disruptions. Heavy-duty trucks, buses, and trailers consume greater quantities of cord fabric per tire than passenger cars, magnifying demand gains. A steadily expanding global vehicle parc sustains replacement volumes, especially in emerging economies where ownership rates continue to climb despite macroeconomic headwinds. Electrification programs in logistics fleets add incremental pull because electric trucks require stiffer carcasses and higher cord density. Parallel capacity additions at leading tire makers create a synchronized upswing that underpins medium-term growth for the tire cord fabrics market.
Rapid Radial-Tire Adoption in Emerging Markets
Across India and Southeast Asia, bias-ply tires are giving way to radial designs that need roughly 40% more cord fabric per unit. Government fuel-efficiency mandates and user demand for longer service life accelerate the changeover. Farm-equipment segments amplify the effect because IF and VF radial technologies require stronger carcasses built with high-tensile cords. The conversion progresses through 2030, producing a durable volume tailwind that compensates for mature demand profiles in North America and Europe. Suppliers capable of ramping polyester and nylon output near local tire clusters are best placed to capture this share.
Petrochemical Feedstock Price Volatility
Polyester and nylon rely on paraxylene, adipic acid, and caprolactam, all of which fluctuate with crude-oil cycles. Sudden surges compress margins for cord weavers, while sharp declines discourage upstream investment, creating supply-security risks. China's dominant position in fiber intermediates means regional outages or trade tensions can translate quickly into global price swings. Although large tire companies can hedge, smaller fabric producers face working-capital stress that may constrain near-term supply.
Other drivers and restraints analyzed in the detailed report include:
- Lightweight HMLS and Hybrid-Cord Demand for Lower Rolling Resistance
- Adoption of RFF "Green" Adhesion Chemistries
- Cyclical Over-/Under-Capacity in Auto Production
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Polyester retained 42.05% of tire cord fabrics market share in 2025 owing to its cost-to-performance balance across passenger and commercial tires. The segment's favorable economics, abundant feedstock, and compatibility with automated weaving underpin its leadership. Aramid, while accounting for a smaller volume base, records a 3.14% CAGR through 2031, powered by EV and ultra-high-performance fitments that demand heat resistance and tensile strength beyond polyester's ceiling. Nylon sustains relevance in bias constructions and specialty off-road tires but confronts gradual volume erosion as radial penetration rises. Rayon continues to retreat because of supply constraints and shorter fatigue life, whereas glass and PVA cord niches stay stable in industrial and aircraft applications. Sustainability imperatives encourage trials of bio-derived polyesters and recycled monomer streams, positioning innovators to redefine fiber hierarchies later in the decade.
Polyester's HMLS grades help leading producers lock in long-term contracts with global tire OEMs, cushioning them against raw-material swings. Aramid suppliers command premium margins and often integrate backward into fiber precursor chemistries to secure supply. Hybrid cords combining polyester with aramid or glass enable tailored stiffness for fine-tuned ride comfort, offering an avenue for differentiated growth.
Complete Report Scope:
- By Fiber
- Nylon
- Polyester
- Rayon
- Aramid
- Glass
- PVA
- By Tire Type
- Bias / Diagonal
- Semi-Radial
- Radial
- By Vehicle Type
- Automotive
- Aircrafts
- Industrial Products
- Others
- By Geography
- Asia-Pacific
- China
- India
- Japan
- South Korea
- ASEAN Countries
- Rest of Asia-Pacific
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Russia
- Nordic Countries
- Rest of Europe
- South America
- Brazil
- Argentina
- Rest of South America
- Middle-East and Africa
- Saudi Arabia
- Turkey
- South Africa
- Rest of Middle-East and Africa
- Asia-Pacific
Geography Analysis
Asia-Pacific's 48.10% share in 2025 reflects production clusters that co-locate petrochemical feedstocks, high-speed weaving mills, and major tire plants. China combines scale with rising competency in HMLS polyester and RFF dipping, while India's automotive growth adds a deep domestic consumption layer. Southeast Asian economies such as Thailand and Indonesia extend the supply chain with export-oriented tire plants, helping the region anchor the tire cord fabrics market.
The Middle East and Africa records a 2.96% CAGR, the fastest worldwide. Governments channel oil revenue into diversification programs that include tire and component production. Saudi Arabia's industrial zones attract foreign joint ventures, while Morocco leverages trade pacts with the EU and the United States to become a North-African export base. Turkey and South Africa, with established auto sectors, provide additional anchor points for growth.
North America and Europe remain innovation hubs where regulatory pressure for low-rolling-resistance and sustainable materials drives demand for advanced cord solutions. High adoption of EVs, stringent fuel-economy standards, and early trials of airless tires shape premium specifications that ripple back through global supply chains. Latin America grows steadily on agricultural equipment demand, but currency volatility and economic cycles inject periodic softness. Overall, shifting geographic footprints prompt cord suppliers to balance low-cost manufacturing with proximity to high-spec customers, ensuring the tire cord fabrics market keeps diversifying regionally.
- Beihai Fiberglass
- Bekaert
- Benninger AG
- Century Enka Limited
- Cordenka GmbH & Co KG
- Cordus
- Far Eastern Group
- Firestone Fibers & Textiles
- GURIS
- HYOSUNG ADVANCED MATERIALS
- Indorama Ventures Public Company Limited
- Kolon Industries Inc.
- KORDRNA Plus a.s.
- Milliken & Company
- Oerlikon Management AG
- SRF Limited
- TEIJIN LIMITED
- TORAY INDUSTRIES, INC
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising global vehicle production and parc expansion
- 4.2.2 Rapid radial-tire adoption in emerging markets
- 4.2.3 Higher EV-related tire-replacement frequency
- 4.2.4 Lightweight HMLS and hybrid-cord demand for lower RR
- 4.2.5 Adoption of RFF "green" adhesion chemistries
- 4.3 Market Restraints
- 4.3.1 Petrochemical feedstock price volatility
- 4.3.2 Cyclical over-/under-capacity in auto production
- 4.3.3 Rise of airless / non-pneumatic tire concepts
- 4.4 Value Chain Analysis
- 4.5 Porter's Five Forces
- 4.5.1 Threat of New Entrants
- 4.5.2 Bargaining Power of Buyers
- 4.5.3 Bargaining Power of Suppliers
- 4.5.4 Threat of Substitute Products
- 4.5.5 Degree of Competition
5 Market Size and Growth Forecasts (Volume)
- 5.1 By Fiber
- 5.1.1 Nylon
- 5.1.2 Polyester
- 5.1.3 Rayon
- 5.1.4 Aramid
- 5.1.5 Glass
- 5.1.6 PVA
- 5.2 By Tire Type
- 5.2.1 Bias / Diagonal
- 5.2.2 Semi-Radial
- 5.2.3 Radial
- 5.3 By Vehicle Type
- 5.3.1 Automotive
- 5.3.2 Aircrafts
- 5.3.3 Industrial Products
- 5.3.4 Others
- 5.4 By Geography
- 5.4.1 Asia-Pacific
- 5.4.1.1 China
- 5.4.1.2 India
- 5.4.1.3 Japan
- 5.4.1.4 South Korea
- 5.4.1.5 ASEAN Countries
- 5.4.1.6 Rest of Asia-Pacific
- 5.4.2 North America
- 5.4.2.1 United States
- 5.4.2.2 Canada
- 5.4.2.3 Mexico
- 5.4.3 Europe
- 5.4.3.1 Germany
- 5.4.3.2 United Kingdom
- 5.4.3.3 France
- 5.4.3.4 Italy
- 5.4.3.5 Russia
- 5.4.3.6 Nordic Countries
- 5.4.3.7 Rest of Europe
- 5.4.4 South America
- 5.4.4.1 Brazil
- 5.4.4.2 Argentina
- 5.4.4.3 Rest of South America
- 5.4.5 Middle-East and Africa
- 5.4.5.1 Saudi Arabia
- 5.4.5.2 Turkey
- 5.4.5.3 South Africa
- 5.4.5.4 Rest of Middle-East and Africa
- 5.4.1 Asia-Pacific
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share/Ranking Analysis
- 6.4 Company Profiles (includes Global-level Overview, Market-level Overview, Core Segments, Financials, Strategic Info, Market Rank/Share, Products and Services, Recent Developments)
- 6.4.1 Beihai Fiberglass
- 6.4.2 Bekaert
- 6.4.3 Benninger AG
- 6.4.4 Century Enka Limited
- 6.4.5 Cordenka GmbH & Co KG
- 6.4.6 Cordus
- 6.4.7 Far Eastern Group
- 6.4.8 Firestone Fibers & Textiles
- 6.4.9 GURIS
- 6.4.10 HYOSUNG ADVANCED MATERIALS
- 6.4.11 Indorama Ventures Public Company Limited
- 6.4.12 Kolon Industries Inc.
- 6.4.13 KORDRNA Plus a.s.
- 6.4.14 Milliken & Company
- 6.4.15 Oerlikon Management AG
- 6.4.16 SRF Limited
- 6.4.17 TEIJIN LIMITED
- 6.4.18 TORAY INDUSTRIES, INC
7 Market Opportunities and Future Outlook
- 7.1 White-space and Unmet-Need Assessment

