PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2124595

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2124595
Europe Personal Care Appliances - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
According to Mordor Intelligence, the Europe personal care appliances market size market is expected to grow from USD 12.96 billion in 2025 to USD 13.52 billion in 2026 and is forecast to reach USD 16.68 billion by 2031 at 4.29% CAGR over 2026-2031.
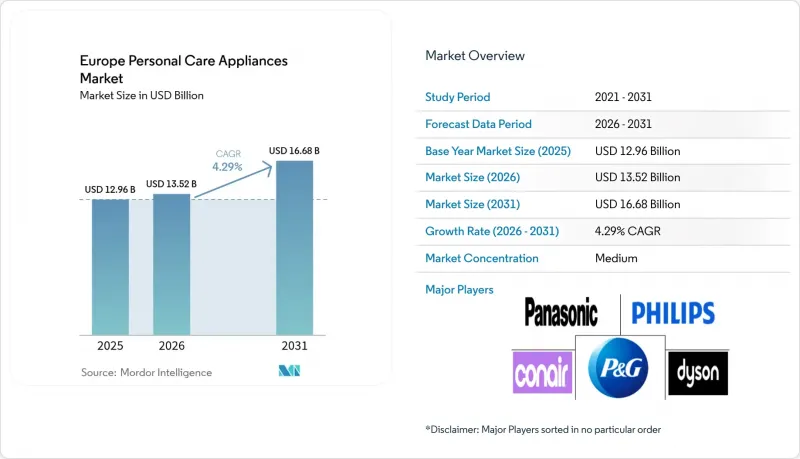
This report is Segmented by Product Type (Shaving and Grooming, Styling, Beauty Appliances, and More), Gender (Men, Women, and Unisex), Operation (Corded and Cordless), Distribution Channel (Supermarkets/Hypermarkets, Specialty Stores, Online Stores, and Other Distribution Channels), and Geography (Spain, United Kingdom, Germany, and More). The Market Forecasts are Provided in Terms of Value (USD).
Europe Personal Care Appliances Market Trends and Insights
Growing Awareness of Personal Grooming and Hygiene
Consumer consciousness around personal grooming has intensified beyond traditional hygiene maintenance toward comprehensive wellness routines that integrate skincare, oral care, and styling regimens. This shift drives premiumization across product categories, with manufacturers like Procter & Gamble introducing USD 380 electric toothbrushes to capture higher-value consumer segments while offsetting tariff-related cost pressures. The trend particularly benefits oral care appliances, which maintain the largest segment share at 46.05%, as consumers increasingly recognize the connection between oral health and overall wellness. German consumers exemplify this evolution, with 67% prioritizing sustainability in appliance purchases and 81% valuing durability and quality over price considerations. This awareness expansion creates opportunities for brands to justify premium pricing through enhanced functionality and health-focused marketing narratives.
Technological Advancements Including IoT, AI, and Smart Features
Smart connectivity and artificial intelligence integration are transforming personal care appliances from standalone tools into interconnected wellness ecosystems that provide personalized recommendations and usage optimization. The EU's ReCiPSS project demonstrated the commercial viability of IoT-enabled appliances through 333 sensor-equipped washing machines across Denmark, Netherlands, Slovenia, and Sweden, generating EUR 90,000-150,000 in annual revenues while enabling predictive maintenance and energy optimization . This technology foundation supports the cordless segment's 6.25% CAGR growth, as manufacturers integrate smart charging algorithms, usage pattern recognition, and app-based control systems. Panasonic's latest product lineup exemplifies this trend with USB-C charging, beard sensors, and nanoe(TM) moisture technology that adapts to environmental conditions. The convergence of IoT capabilities with personal care creates data-driven value propositions that enhance customer retention and enable subscription-based service models.
Competition From Manual Grooming Alternatives
Traditional manual grooming tools maintain competitive pressure on electric appliances through superior affordability, zero maintenance requirements, and established consumer habits that resist technological adoption. This constraint particularly affects price-sensitive segments and regions experiencing economic uncertainty, with France projecting only 0.4% consumer durables growth in 2025 and Germany facing continued market contraction after a 2.7% decline in 2023. The challenge intensifies in oral care, where manual toothbrushes cost significantly less than electric alternatives while delivering adequate cleaning results for many consumers. Manual alternatives also avoid the complexity of charging, replacement parts, and potential technical failures that can frustrate users. Manufacturers counter this restraint through value-focused positioning, extended warranties, and subscription models that reduce upfront costs while demonstrating long-term savings and superior health outcomes.
Other drivers and restraints analyzed in the detailed report include:
- Influence of Social Media and Celebrity Endorsements
- Adoption of Rechargeable and Cordless Appliances
- Limited Product Differentiation in Some Segments
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Oral care appliances command 45.42% market share in 2025, establishing the segment's foundational role in European personal care routines, while styling appliances emerge as the fastest-growing category at 4.72% CAGR through 2031. The oral care segment's dominance reflects heightened health consciousness and professional dental care integration, with Philips leading sustainability initiatives through 70% bio-based brush head plastics and comprehensive recycling programs spanning 420 collection points across the UK. Styling appliances benefit from social media influence and professional-grade technology adoption, as consumers seek salon-quality results for home use. Shaving and grooming products maintain steady performance through premiumization strategies, while beauty appliances capture niche segments focused on skincare integration and LED therapy applications.
The segment dynamics reflect broader technological convergence, with manufacturers integrating smart sensors, app connectivity, and personalized algorithms across product categories. EU Medical Device Regulation compliance increasingly affects beauty appliances that incorporate optical radiation or invasive features, requiring enhanced safety documentation and clinical evidence. Other products, including foot massagers and nail care tools, contribute incremental growth through wellness trend alignment and aging population demographics. The product portfolio expansion strategy enables brands to capture larger wallet share while reducing dependence on single-category performance fluctuations.
Unisex products dominate with 54.11% market share in 2025, yet men-specific appliances achieve superior 5.61% CAGR growth through 2031, reflecting evolving gender dynamics in personal care consumption patterns. The unisex leadership demonstrates successful product design that transcends traditional gender boundaries, enabling household sharing and reducing purchase complexity for couples and families. Men's segment acceleration reflects expanding grooming routines beyond basic shaving toward comprehensive skincare, hair styling, and wellness applications. Women's segment maintains steady performance through premium positioning and technology integration, particularly in hair care and beauty device categories.
This segmentation evolution aligns with broader social trends toward gender-inclusive marketing and product development, as brands recognize the limitations of binary categorization in contemporary consumer behavior. Regulatory compliance factors minimally impact gender segmentation, though product safety standards apply equally across all demographic targets. The trend toward unisex products creates economies of scale in manufacturing and marketing while enabling brands to address diverse household needs through streamlined product portfolios rather than duplicative gender-specific offerings.
Complete Report Scope:
- By Product Type
- Shaving and Grooming
- Shavers
- Trimmers
- Epilator
- Styling
- Hair Straightener
- Hair Dryer
- Hair Curler/Rollers
- Others Styling Products
- Beauty Appliances
- Oral Care
- Others
- Shaving and Grooming
- By Gender
- Men
- Women
- Unisex
- By Operation
- Corded
- Cordless
- By Distribution Channel
- Supermarkets / Hypermarkets
- Specialty Stores
- Online Retail Stores
- Other Distribution Channels
- By Geography
- Germany
- United Kingdom
- Italy
- France
- Spain
- Netherlands
- Poland
- Belgium
- Sweden
- Rest of Europe
List of Companies Covered in this Report:
- Procter & Gamble
- Koninklijke Philips N.V.
- Spectrum Brands Holdings Inc.
- Conair LLC
- JAB Holding Company (Coty Inc.)
- Dyson
- Havells India Ltd.
- Helen of Troy Limited
- Braun GmbH
- Beiersdorf AG
- Remington Products Company, LLC
- Panasonic Corporation
- BSH Hausgerate GmbH
- Electrolux AB
- Groupe SEB
- Rowenta
- Valera AG
- Philips Oral Healthcare
- Colgate-Palmolive Company
- Henkel AG & Co. KGaA
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Growing Awareness of Personal Grooming and Hygiene
- 4.2.2 Technological Advancements Including loT, AI, and Smart Features
- 4.2.3 Influence of Social Media and Celebrity Endorsements
- 4.2.4 Adoption of Rechargeable and Cordless Appliances
- 4.2.5 Rising Demand for At-Home Grooming Solutions
- 4.2.6 Trend Towards Unisex and Gender-Inclusive Products
- 4.3 Market Restraints
- 4.3.1 Competition From Manual Grooming Alternatives
- 4.3.2 Limited Product Differentiation in Some Segments
- 4.3.3 Proliferation of Counterfeit Products
- 4.3.4 Consumer Resistance to Premium Pricing
- 4.4 Consumer Behaviour Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Advancement
- 4.7 Porter's Five Forces
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Bargaining Power of Suppliers
- 4.7.4 Threat of Substitutes
- 4.7.5 Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Product Type
- 5.1.1 Shaving and Grooming
- 5.1.1.1 Shavers
- 5.1.1.2 Trimmers
- 5.1.1.3 Epilator
- 5.1.2 Styling
- 5.1.2.1 Hair Straightener
- 5.1.2.2 Hair Dryer
- 5.1.2.3 Hair Curler/Rollers
- 5.1.2.4 Others Styling Products
- 5.1.3 Beauty Appliances
- 5.1.4 Oral Care
- 5.1.5 Others
- 5.1.1 Shaving and Grooming
- 5.2 By Gender
- 5.2.1 Men
- 5.2.2 Women
- 5.2.3 Unisex
- 5.3 By Operation
- 5.3.1 Corded
- 5.3.2 Cordless
- 5.4 By Distribution Channel
- 5.4.1 Supermarkets / Hypermarkets
- 5.4.2 Specialty Stores
- 5.4.3 Online Retail Stores
- 5.4.4 Other Distribution Channels
- 5.5 By Geography
- 5.5.1 Germany
- 5.5.2 United Kingdom
- 5.5.3 Italy
- 5.5.4 France
- 5.5.5 Spain
- 5.5.6 Netherlands
- 5.5.7 Poland
- 5.5.8 Belgium
- 5.5.9 Sweden
- 5.5.10 Rest of Europe
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 Procter & Gamble
- 6.4.2 Koninklijke Philips N.V.
- 6.4.3 Spectrum Brands Holdings Inc.
- 6.4.4 Conair LLC
- 6.4.5 JAB Holding Company (Coty Inc.)
- 6.4.6 Dyson
- 6.4.7 Havells India Ltd.
- 6.4.8 Helen of Troy Limited
- 6.4.9 Braun GmbH
- 6.4.10 Beiersdorf AG
- 6.4.11 Remington Products Company, LLC
- 6.4.12 Panasonic Corporation
- 6.4.13 BSH Hausgerate GmbH
- 6.4.14 Electrolux AB
- 6.4.15 Groupe SEB
- 6.4.16 Rowenta
- 6.4.17 Valera AG
- 6.4.18 Philips Oral Healthcare
- 6.4.19 Colgate-Palmolive Company
- 6.4.20 Henkel AG & Co. KGaA
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK

